Connect with us

Economy & Market

Decline of PE Investments in Real Estate | A reality or an illusion?

Published

on

Shares

Amid concerns over the decline (5 per cent YOY in FY18) in private equity (PE) investments entering India, the impact on real estate appears to be nearly four-folds higher (19 per cent YOY). While the numbers spin a gloomy picture for inflows, a detailed analysis reveals that large one-off deals such as the Hiranandani – Brookfield deal and the DLF-GIC deal skewed the numbers in FY17. Therefore, it might be incorrect to believe that PE investments in FY 18 are on a declining trend. This whitepaper is an attempt to capture the true picture of PE capital in Indian realty and looks at the quintessential question – is the decline of PE investments in real estate a reality or an illusion?
The lifeline of capital movement, PE investments in India, saw a slowdown in FY18 following the staggering growth trajectory over the recent past. While overall PE investments dropped by 5 per cent YOY, funds foraying into the real estate sector declined by significant 19 per cent YOY during this period. Investments in sectors other than realty however, held steady.Did investments into real estate actually decline?
At one glance, the decline of 19 per cent YOY in investments could reflect turbulence in the real estate sector. But when we delve deeper and dissect the flow of funds, it provides a different picture. During FY17, there have been several large ticket brownfield transactions particularly in commercial real estate covering office and retail assets (malls). For example, the $1.4 billion DLF-GIC deal and $1 billion Hiranandani-Brookfield deal which elevated the total investments for FY17. Such transactions do not happen often due to the sheer size of assets that are involved in the transactions, as those assets have a long gestation period and take more than a decade to mature and become operationally efficient.
If we look at table 2, the PE investments have been on an increasing trend since FY15 and the strong momentum which was observed in FY17 has sustained in FY18.Commercial r.e. more attractive for equity investments
The structural reforms introduced by the government over the past 2-3 years have helped the real estate sector in India to move towards a relatively transparent environment. This transformation has attracted a significant number of organised players. The process is still on and shall stabilize in short to medium term. We believe that the reforms have brought in a paradigm shift in the sector and made it more conducive for investors. Taking cognizance of these reforms, investors have invested around USD 24 billion in the form of debt and equity into real estate since FY15.
Among the asset classes, residential sector is reeling under pressure for the last 3-4 years but commercial real estate is moving from strength to strength. While the office market is maintaining its robust annual transaction volumes, retail spaces, particularly select shopping centres in tier I and II cities are catching the attention of international funds. Warehousing is one of the most promising sectors in India. The implementation of the Goods and Services Act (GST), continued government focus on building industrial corridors and the unabated growth of the Indian consumption market have whipped up the growth potential of the sector.
While the PE investments into residential asset between FY15 and FY18 were primarily in the form of structured debt courtesy inherent risk of the sector, those into commercial assets were in the form of equity. Out of $24 billion, around $10 billion (42 per cent) was in the form of equity investments into commercial assets such as prime office assets and select retail malls.
The last couple of years have seen unprecedented interest for good quality rent yielding office and retail assets in cities across India among global financial institutions such as the private equity giants, sovereign funds and wealth funds. This demand coupled with scarcity in supply of good quality assets, strong performance of the office sector, reduced interest rate regime, decline in risk expectations on account of reforms and a strong bench of long term investors did result in compression of capitalisation (cap) rate for good quality commercial assets from 9-11 per cent to 7.5-9 per cent during the last three to four years.Would the cap rate compression in commercial assets continue?
Despite the compression in cap rates, investors’ appetite for quality space seems undeterred. Investors entering the market today are expecting the cap rates to compress further up to 150 bps in the years to come. The projections are also in sync with the estimated exit time. They are hoping to get dual benefits – primarily from the growth in rental income and secondly from compression in cap rates.
On the rental front, we are optimistic about the growth prospects, as there has been a significant crunch in the supply of good quality office space across major cities in India. Vacancy rates in some of the most sought after business districts in India such as the Bandra-Kurla Complex, Lower Parel in Mumbai, Outer Ring Road in Bengaluru and DLF Cyber City in NCR have shrunk to single digit levels. These prime business districts have limited scope for substantial new supply. The supply crunch coupled with strong occupier demand has been driving up the rentals for good quality office space. With business environment in India improving and the country’s GDP growth rate expected to improve in the coming years, the occupier demand would strengthen. This would provide tailwinds for future office rental growth.
The oversupply of retail assets (malls) coupled by strata title sales of malls in India led to underperformance and closure of a large number of properties. Select retail assets which survived and were successful are witnessing strong occupier demand and rental growth. These particular retail assets are attracting investors’ attention at par with or in some cases higher than that witnessed in case for office assets. The demand is primarily driven by scope for better rental growth. Unlike office assets, which generally have a standard rental appreciation clause of 15 per cent every three years on the base rent, retail assets come with revenue sharing opportunities, in addition to the escalation on base rent. There is a significant potential for mall revenues to grow on account of the rising consumer demand and ongoing structural changes taking shape in select malls to accommodate new anchors and entertainment options in order to remain relevant against the competition from online retail. Hence, with respect to the expectation of rental growth in office and retail assets the investors would be able to achieve their desired objective.
However, with respect to expectations of cap rate compression, one needs to be cautious. Globally, the days of zero/low interest rates regimes are coming towards an end. The U.S. fed has ended its quantitative easing program and has already hiked the rates several times and has indicated of more hikes in the coming years. This has led to increase in cost of funds globally. Even in India the reducing interest rate regime prevailing for the last three years is likely to end soon and so is the case with Government Securities (G-sec) yields.
We believe that our economy is at the bottom of the current interest rate cycle and going forward the rates would start hardening. The government breaching of fiscal deficit targets currently, have already put upwards pressure on G-sec yields. Further additional factors such as expectation of higher inflation, weakened capital reserve position of banks owing to NPAs, treasury losses on bank’s G-sec holdings and the early sign of pick up in credit growth have been pushing banks to raise lending rates. With election in several states and the general election approaching, the volatility would be higher in the next two years.
While it is too early to comment on the extent of rise in lending rates and G-sec yields, in the short term they are likely to have an impact on the current trend of cap rate compression. If the rise in lending rates and G-sec goes up beyond 100-150 bps the expectation of returns from real estate investments would go up. Thus, particularly in the short-term, the case for cap rate compression would weaken and it may hold steady or increase marginally to keep the spread constant. Overall the institutional investor may have to rely more on rental growth to make up for their expected returns from their investments in the near future.
When it comes to long-term perspective, India’s macro-economic fundamentals and GDP growth outlook remain strong on the back of settling of the ongoing structural reforms and completion of mega infrastructure projects in the next five years. In turn, as the economy matures the perceived risk pertaining to invest in India is likely to come down. With the Reserve Bank of India’s continuous focus on keeping the inflation under 4 per cent and government’s efforts for fiscal consolidation, the cap rates are going to see required compression. Hence, investors with longer investment horizons like endowment funds, sovereign funds, pension funds and insurance companies would achieve returns at par with their expectations. A note of caution: unforeseen catastrophe like global financial crisis of 2007-08 should not repeat, current low intensity trade war should not exacerbate
and India should have a stable government beyond 2019.

Continue Reading
Click to comment

Leave a Reply

Your email address will not be published. Required fields are marked *

Economy & Market

Leonard Unveils Dual-Head Robotic Arm for Hazardous Industrial Demolition

Published

on

By

Shares

 Leonard unveils Descender Duo, a dual-head robotic demolition arm designed to improve industrial safety and reduce shutdown time by up to 50 per cent.

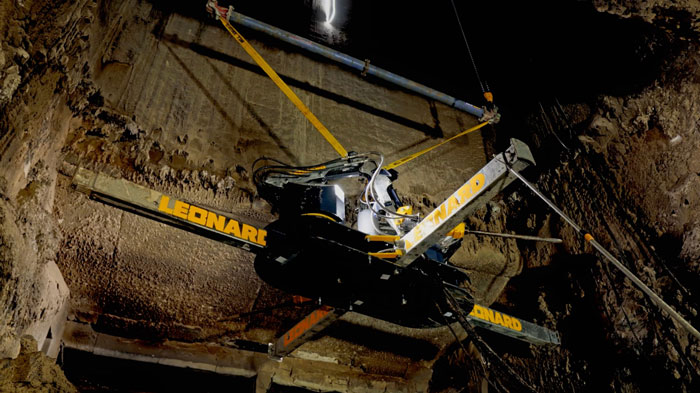
Industrial robotics and refractory services specialist Leonard has launched Descender Duo, a dual-head robotic demolition arm designed to improve safety, accelerate maintenance and reduce shutdown times in hazardous industrial environments. The system made its debut at Lisahally Power Station in Northern Ireland, removing 25 tonnes of slag material within hours.

Developed for the cement, metals, waste-to-energy and petrochemical industries, Descender Duo enables remote-controlled refractory demolition, anchor cutting and welding, and refractory spraying inside boilers, calciners and silos. Its vertical-access design eliminates the need for personnel to enter confined, high-risk spaces during these operations.

Weighing less than two tonnes, the pre-assembled system requires an access opening of just 1.2 m². Supported by an external overhead hoist, it uses electrically operated hydraulic stabilising legs to secure itself inside vessels. The robotic arm offers 360-degree rotation and is suited to vessels approximately 9 m in diameter, with its operating reach extendable through strategically positioned access points.

Equipped with two independently controlled robotic heads, Descender Duo can perform identical or different tasks simultaneously, including refractory demolition, anchor cutting and spraying. Its remote-control system incorporates live camera feeds, allowing operators to monitor operations without entering hazardous environments.

According to Leonard, the technology can deliver time savings of up to 50 per cent compared with manual methods. Its ability to operate at temperatures exceeding 100°C allows maintenance to begin as early as 24 hours after burner shutdown. An all-electric power supply further supports cleaner and more cost-efficient operations.

First Deployment Demonstrates Shutdown Efficiency

The system was first deployed at Burmeister & Wain Scandinavian Contractor’s (BWSC) Lisahally Power Station in Londonderry, Northern Ireland. The facility generates electricity from grade C waste wood, supplying approximately 40,000 homes and businesses.

Leonard and BWSC collaborated to develop a customised solution for the plant’s 26-metre furnace, where extensive external pipework created significant access challenges.

Mark Leonard, Managing Director, Leonard, said, “It required new thinking and rather than step away from the problem we were committed to solving it for the customer, with the customer. We’re relentless in our approach to tackling complex challenges, head-on. We took our years of cement plant experience, coupled with our working knowledge of the BWSC plant, and designed, engineered and tested a completely new vertical solution within just seven weeks from that initial conversation with the customer. That solution was the Descender Duo as we know it today.”

Traditionally, the furnace required a cooling period of up to 36 hours before preparatory work could begin, followed by manual slag removal using rope-access personnel. With Descender Duo, work commenced just 24 hours after shutdown, reducing downtime by up to one day.

The deployment removed 25 tonnes of slag within hours, eliminated the need for at least six workers to enter the hazardous furnace interior and saved 26 hours in the shutdown programme.

“The effectiveness exceeded expectation,” said Martin Doran, Plant Manager at Lisahally Power Station.

“When the Descender Duo concept was first discussed, we had to spend some time with the team from Leonard looking at how it was going to be moved into the furnace. Every site is different and that presented its own challenges, but nothing that the team couldn’t overcome. Once it was installed we were hugely impressed by its efficiency.”

Expanding Industrial Robotics Applications

Descender Duo joins Leonard’s existing portfolio of robotic maintenance solutions, including the Axis horizontal-access arm, Nano confined-space access arm, Charger cement mill media recharging system and Calibre cement mill media grading system.

Headquartered in Northern Ireland, Leonard provides robotic refractory demolition, installation, inspection and industrial maintenance services across the cement, metals, energy, biomass, glass and civil engineering sectors.

Formerly known as G Leonard, the company has more than 35 years of industry experience and operates across Europe, North America, the Middle East, Africa and Asia-Pacific.

The latest innovation reinforces Leonard’s focus on replacing hazardous manual processes with robotic systems that improve workforce safety, enhance operational efficiency and minimise industrial downtime.


Continue Reading

Concrete

Martin Engineering Appoints Ashwini Khunte as India General Manager

Published

on

By

Shares

Martin Engineering names Ashwini Khunte India General Manager to strengthen operations and drive growth across key bulk material handling sectors.

Pune

Martin Engineering, a global provider of bulk material handling solutions, has appointed Ashwini Khunte as General Manager of its India business, strengthening its leadership as the company expands its presence across the country’s cement, mining, steel, power and infrastructure sectors.

Khunte brings more than a decade of experience with Martin Engineering, having joined its Indian operations in 2013 as a Design Engineer, shortly after the company established its presence in the country in 2012.

A mechanical engineer by qualification, she spent her initial five years developing bulk material handling solutions in collaboration with the company’s operations team. During this period, she gained extensive experience addressing operational challenges in the steel, cement and coal industries. She subsequently moved into project engineering, managing major engineering, procurement and construction (EPC) and original equipment manufacturer (OEM) projects from initial enquiry to commissioning. Her responsibilities later expanded to overseeing Martin Engineering’s conveyor product portfolio in India, involving customer engagement, technical presentations and site visits across heavy industries.

In 2024, Khunte was promoted to Head of Sales & Marketing for the company’s Europe, Middle East, Africa and India (EMEAI) region. The position broadened her international market exposure and strengthened her strategic and commercial leadership capabilities.

Commenting on her appointment, Ashwini Khunte, General Manager, Martin Engineering India, said: “India represents a tremendous opportunity for Martin Engineering. The country’s continued investment in cement, mining, steel, power and infrastructure is creating increasing demand for safer, cleaner and more productive bulk material handling, and that’s exactly what we do. My priority will be to build on the strong foundations already established in India, while continuing to develop our people, strengthen customer relationships and bring practical solutions to the challenges faced by our industry.”

Robert Whetstone, Area Vice President – EMEAI, Martin Engineering, highlighted Khunte’s technical expertise, market understanding and leadership experience.

“Ashwini brings an exceptional combination of technical understanding, customer knowledge and commercial leadership. She has grown as Martin Engineering has grown, and has consistently demonstrated outstanding capability to transform her expertise into practical solutions. Her knowledge of the Indian market, together with her international experience, makes her ideally suited to lead our India business through its next stage of growth for years to come.”

Since establishing its Indian business in 2012, Martin Engineering has expanded its local workforce, manufacturing capabilities and dealership network. The company supplies conveyor products, transfer point solutions, material flow aids, training and technical support to bulk material handling industries. Khunte’s appointment positions the company to further strengthen customer relationships and expand its solutions portfolio in India’s growing industrial and infrastructure markets.

Continue Reading

Concrete

Fornnax Wins AIRIA’s Special Export Award for Rubber Machinery in 2025-26

Published

on

By

Shares

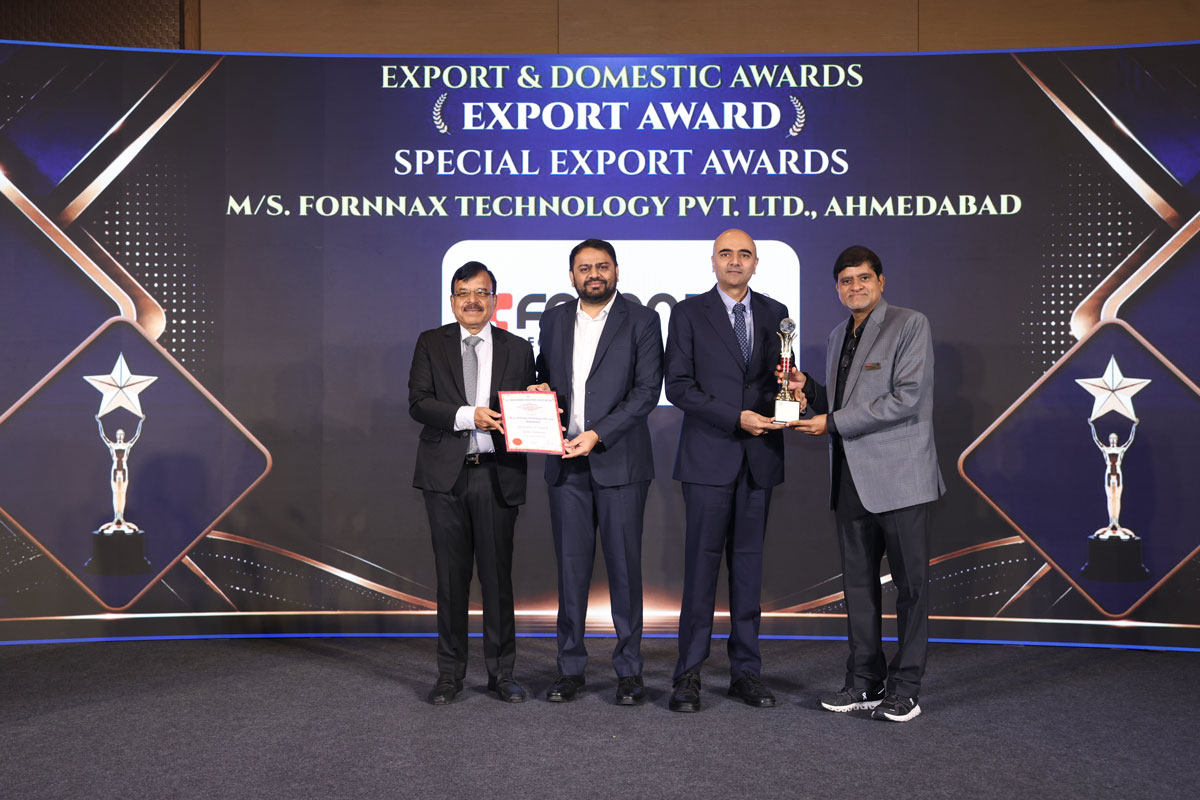
Fornnax Technology Pvt. Ltd. has been honoured with the Special Export Award – Rubber Machinery for 2025–26 by the All-India Rubber Industries Association (AIRIA), in recognition of its highest exports of tyre recycling plants to the European region.

With more than a decade of experience in India’s tyre recycling industry, Fornnax has contributed to the development of advanced recycling technologies and infrastructure. The company currently holds a 90% market share in India’s domestic tyre recycling sector, while exports account for 30% of its business, spanning markets such as Europe, Australia and the GCC.

The award marks another milestone for Fornnax, whose tyre recycling lines and advanced shredding technologies are supporting the growth of the circular economy in India and international markets.

Commenting on the recognition, Mr. Jignesh Kundaria, Founder and Director of Fornnax, said:

“This honour from AIRIA is a reflection of an incredible journey we have undertaken over the years. When we started Fornnax, there was no established recycling industry in India to follow. We chose to build for the future instead. Today, when you see India’s tyre recycling sector, it has already transformed into a dynamic, high-growth industry and we are extremely proud to have played our part in building it.”

Unlike standalone equipment suppliers, Fornnax focuses on developing complete, high-capacity recycling infrastructure. Its integrated systems combine multiple stages of shredding and size reduction to enable efficient, continuous operations. This system-level engineering approach helps recycling operators improve throughput, equipment reliability and operational consistency.

The recognition reinforces Fornnax’s commitment to developing engineering technologies that contribute to a more efficient and circular recycling ecosystem.

Looking ahead, the company aims to expand its international presence while continuing to develop advanced shredding and recycling solutions to address the growing volumes and evolving requirements of the global recycling industry.

For more information, visit: www.fornnax.com

Continue Reading

Video Thumbnail
▶

    SIGN-UP FOR OUR GENERAL NEWSLETTER

    Trending News

    SUBSCRIBE TO THE NEWSLETTER


    Don't miss out on valuable insights and opportunities to connect with like minded professionals.


      This will close in 0 seconds