Connect with us

Economy & Market

Developing economies & response to pandemic

Published

on

Shares

In these unprecedented times of COVID-19, the health impact coupled with the economic headwinds, leaves many of the developing economies vulnerable, but some are coping with the impact better than the others; those that are doing better have firstly a robust primary health care system that is able to take the additional impact of health "overload" and coupled to that they have a close knit localised "controlled" programme of identifying, isolating and providing affordable health care which forms the backbone of the recovery. More importantly, these economies have been able to find traction between a ‘central’ (larger) outlook on response with the "local" administration of the response, health and economic included.

Emerging and developing economies have several contending issues at hand, sharp drop in trade and tourism, dampened capital flows, much tighter credit conditions, ebbing remittances and of course a debt pile that blunts the fiscal expansion prospects. A few of them have to still solve banking woes, stemming from NPAs and some of the sectors to which the banking system owes its loans to have slowed due to lack of demand.

East Asia is now slated to grow at a scant 0.5 per cent, South Asia will contract by 2.7 per cent, Sub-Saharan Africa by 2.8 per cent, Middle East and North Africa by 4.2 per cent, Central Asia by 4.7 per cent and Latin America by 7.2 per cent.

These were the last numbers from the World Bank (June 2020). Are there some success stories within these grim tales, some stand out like Vietnam or Indonesia while India has been able to keep the mortality rates very low, which is also commendable. Vietnam has dealt with the pandemic with exemplary dexterity by eliminating the spreading roots, while Indonesia has taken a twin program of fighting the pandemic together with focus on job creation.

Vietnam’s first case was reported in early January’20 but in no time the country was ready with a comprehensive plan to respond to the health crisis, first with a proactive plan on "target testing" with three degrees of "contact tracing" for each positive case with large Government centers providing quarantining arrangements and in no time the borders were closed for all foreigners. With the full experience of SARS, Vietnam had the infrastructure and the processes fully tried and tested but its vibrant primary health infrastructure had enormous room to expand in times of crisis; health care expenditure increased by 9 per cent year on year per capita after SARS, EBOLA and ZIKA, making most of the health statistics far better than most developed nations.

The biggest success story can be summarized by Vietnam’s ability to provide Test results within 80 minutes, which many of the developed nations took five to six days, which made the testing useless. This is also the reason that Vietnam could test 1,000 people for each tested positive case, which is the highest in the world; Vietnam today has about 1,000 detected cases and have reported only two deaths so far.

Economic response to any pandemic must start with the focusing on the heath sector and past pandemics were taken as a learning opportunity, those who have done better this time have actually sharpened this focus with an unprecedented preparedness.

The others on this list are Indonesia, who have now merged their disaster recovery task force with the National Economic Recovery taskforce under the Economic Affairs Minister and the full focus on State Owned Enterprises to take the economy out of the unemployment crisis is a distinguishing feature of the recovery. Also Indonesia has factored in a long and arduous battle with the virus and have taken long term view of things to come. Their response to the recent job losses is directed to long term strategy to capitalise on the recent apathy of many global firms to stay anchored to supply chains deeply embedded in China. The other centralised focus has been to direct credit assistance to micro, small and medium enterprises. This diversity of credit assistance that touches vast sections of people and business is a distinguishing feature for Indonesia.

Finding a balance between two potentially competing forces, health and economic interests is one of the key drivers of success.

ABOUT THE AUTHOR:
Procyon Mukherjee
works as Chief Procurement Officer at LafargeHolcim India. The ideas presented are his personal and have no connection to the beliefs of the company where he works.

Continue Reading
Click to comment

Leave a Reply

Your email address will not be published. Required fields are marked *

Concrete

UltraTech becomes first Indian cement firm to cross 2 GW green energy

Published

on

By

Shares

UltraTech Cement has crossed 2 GW of captive green energy capacity, with renewables and waste heat recovery meeting 48 per cent of its power needs.

Mumbai

UltraTech Cement Limited has surpassed 2 GW of installed green energy capacity for captive use, becoming the first cement company in India to achieve the milestone. The Aditya Birla Group company commissioned 116.55 MW of wind capacity at its Inter-State Transmission System-connected wind-solar hybrid project in Barmer, Rajasthan, along with 10 MW of Waste Heat Recovery System capacity at Sarlanagar Cement Works in Karnataka.

With these additions, UltraTech’s cumulative installed green energy capacity has reached 2,024 MW. This includes 1,580 MW of renewable energy capacity and 444 MW of waste heat recovery capacity, together meeting around 48 per cent of the company’s current power requirements.

The company said the milestone reflects the progress of its long-term energy transition strategy. In FY27 so far, nearly one-third of UltraTech’s 76 manufacturing units in India have maintained green energy utilisation above 50 per cent of their electricity requirements, while five units have crossed 95 per cent.

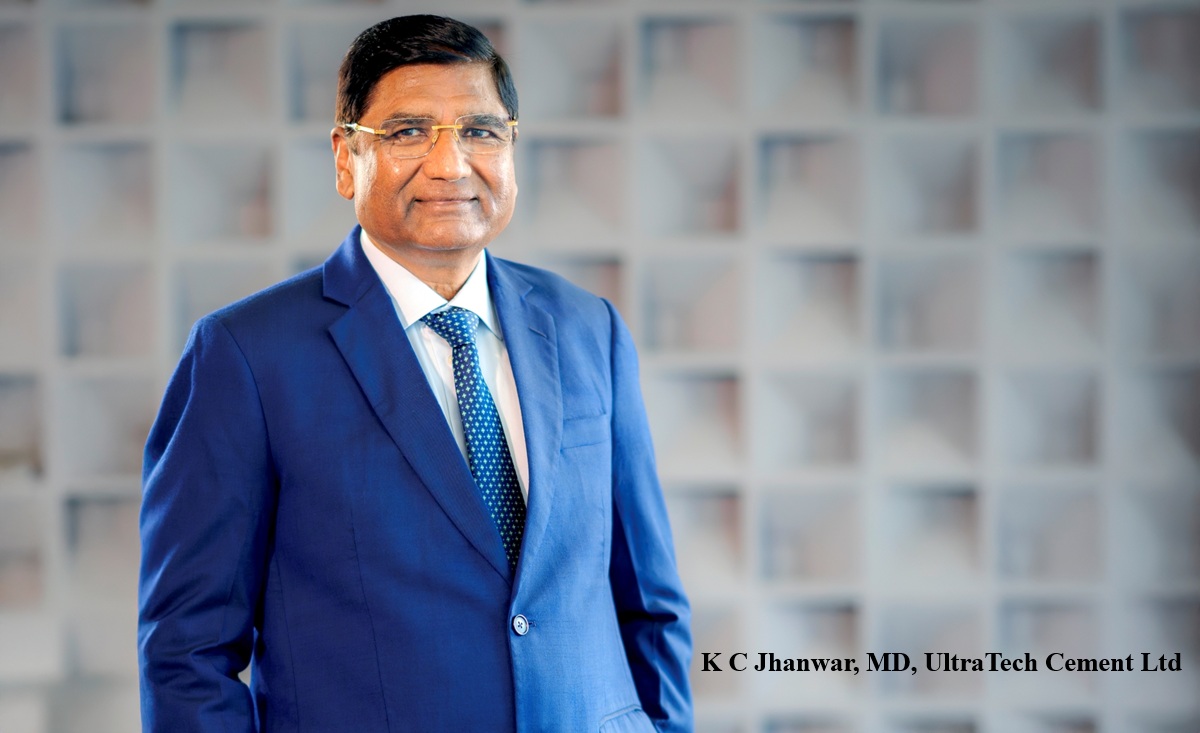
K C Jhanwar, Managing Director, UltraTech Cement Limited, said, “Crossing the 2 GW green energy milestone is the result of a strategy we have pursued consistently over the past decade. Cement is an energy-intensive, hard-to-abate sector, and showing that reliability and growth can go hand in hand with a rapid shift to green energy sets a benchmark for the industry. With nearly half of our power needs now met through green energy, we are significantly less exposed to fossil fuel supply constraints and power price volatility. As we scale up renewables, waste heat recovery and battery storage across our operations, we are building an energy foundation for stable, long-term growth.”

UltraTech commissioned 430 MW of green energy capacity in FY26 and continues to expand its renewable energy and waste heat recovery portfolio.

The company is also progressively integrating Battery Energy Storage Systems across its operations to improve renewable energy utilisation and supply reliability.

In 2025, UltraTech operationalised what it described as India’s first on-site hybrid round-the-clock renewable energy project at Sewagram Cement Works in Gujarat. The project combines solar, wind and battery storage.

As part of its decarbonisation strategy, UltraTech said it has not invested in new captive thermal power capacity for either greenfield projects or brownfield expansions at its integrated units for more than a decade.

The company said its expanding green energy portfolio is helping reduce dependence on conventional grid electricity and fossil fuel-based power, while lowering exposure to fluctuations in coal and electricity prices.

UltraTech aims to increase green energy’s share in its total power mix to 85 per cent by 2030. As a member of RE100, it has also committed to meeting 100 per cent of its electricity requirement through renewable sources by 2050.

UltraTech Cement, the cement flagship of the Aditya Birla Group, has a total grey cement capacity of 210.1 MTPA and white cement and putty capacity of 3.5 MTPA. The company is also a signatory to the GCCA Climate Ambition 2050 and has committed to the GCCA Net Zero Concrete roadmap.

Continue Reading

Concrete

Shiva Cement Merges with JSW Cement

Published

on

By

Shares

JSW Cement has announced a scheme of arrangement to merge its listed subsidiary Shiva Cement with itself, creating a single unified cement platform. The boards of both companies have approved the proposal, which will require clearances from stock exchanges, the Securities and Exchange Board of India, the National Company Law Tribunal, Odisha Industrial Infrastructure Development Corporation and other applicable authorities.

The transaction is expected to be completed within 12 to 14 months, subject to the necessary approvals from regulators, shareholders and creditors. Under the scheme, JSW Cement will issue 5 equity shares with a face value of Rs. 10 each for every 41 equity shares with a face value of Rs. 2 each held by Shiva Cement shareholders other than JSW Cement.

The company said the merger would consolidate financial, managerial, technical, distribution and marketing resources while reducing administrative duplication and compliance requirements. It would also provide greater funding flexibility, potentially lower financing costs and eliminate inter-company guarantees.

The consolidation is expected to strengthen backward integration by enabling JSW Cement to use Shiva Cement’s clinker manufacturing facility. This would reduce dependence on external clinker procurement and improve supply-chain efficiency. Public shareholders of Shiva Cement would receive direct ownership in JSW Cement, which has a broader institutional investor base and a more liquid listed presence.

JSW Cement acquired a controlling stake in Shiva Cement through transactions that began in January 2017. Shiva Cement operates a clinker facility in Odisha, near the borders of Odisha, Chhattisgarh and Jharkhand, and commissioned a 1 mtpa cement grinding unit at Sambalpur in FY26 through a commercial arrangement with Bhushan Power and Steel.

JSW Cement has 24.10 mtpa of cement grinding capacity and 9.74 mtpa of clinkerisation capacity. Its Indian operations comprise nine plants, including two integrated units, one clinker unit and six grinding units. The proposed merger is intended to simplify the corporate structure and align the financial statements of the two companies.

Continue Reading

Concrete

Nuvoco Vistas, CleanMax Partner for Wind-Solar Hybrid Project in Rajasthan

Published

on

By

Shares

The project – comprising 20 MW of wind and 26.4 MWdc of solar capacity – will support Nuvoco’s cement operations with cleaner power while strengthening its renewable energy and decarbonisation strategy.

Mumbai, September 29, 2026

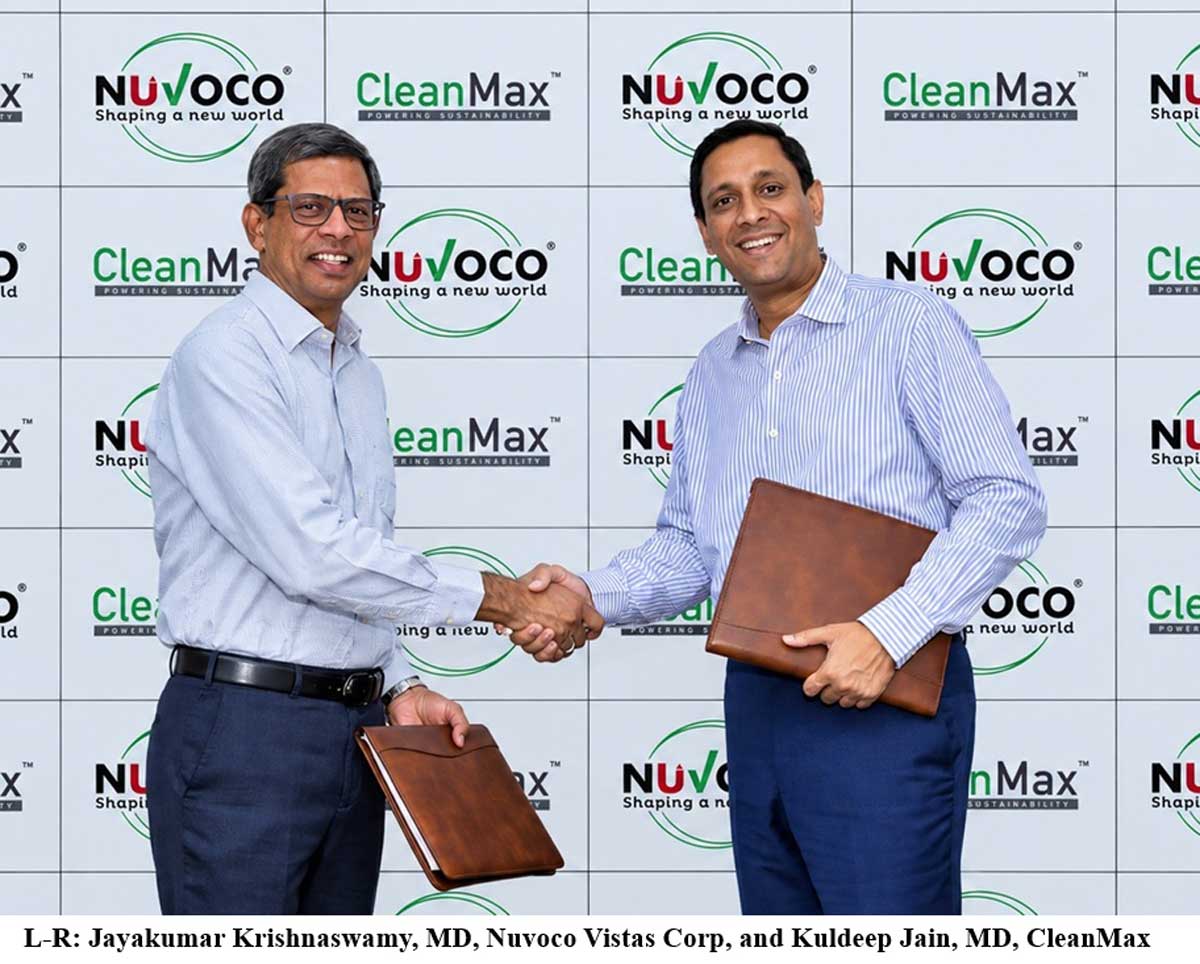
Nuvoco Vistas Corp Ltd, part of Nirma Group and one of India’s leading cement companies, has partnered with Clean Max Enviro Energy Solutions Limited (CleanMax), a renewable energy solutions provider for the commercial and industrial (C&I) sector, to develop a 46.4 MW wind-solar hybrid renewable energy project in Rajasthan.

The project will support Nuvoco’s cement operations with cleaner power while strengthening its renewable energy and decarbonisation strategy. It is expected to increase the share of renewable energy in Nuvoco’s power mix, reducing fossil fuel consumption and associated emissions.

Developed by CleanMax, an Independent Power Producer (IPP), at Bhikamkhore, Rajasthan, the project will comprise 20 MW of wind capacity and 26.4 MWdc of solar capacity, along with a 2-MWh Battery Energy Storage System (BESS). Power generated from the facility will be supplied to Nuvoco through the State Transmission Utility (STU) Open Access network.

The hybrid project is expected to generate approximately 100 million units (MU) of renewable electricity annually and help avoid around 1,25,485 tonnes of CO₂ emissions every year across Scope 1 and Scope 2 emissions.

The initiative supports Nuvoco’s ongoing efforts to reduce the carbon intensity of its manufacturing operations through renewable energy adoption, Waste Heat Recovery Systems (WHRS), energy-efficiency measures and increased use of alternative fuels. It also aligns with the company’s DIRE (Digitalisation, Innovation and Renewables) agenda, which focuses on climate action, renewable energy transition, water stewardship, circularity and biodiversity conservation across its manufacturing ecosystem.

Commenting on the initiative, Jayakumar Krishnaswamy, Managing Director, Nuvoco Vistas Corp Ltd, said, “This marks an important step in advancing Nuvoco’s journey towards more sustainable and resilient operations. Our collaboration with CleanMax will increase the share of renewable energy across our Rajasthan operations, strengthening our energy mix while improving long-term cost efficiency and reducing our dependence on conventional power sources. Initiatives such as these reinforce our commitment to operational excellence and responsible growth, while supporting our vision of Building a Safer, Smarter and Sustainable World.”

Kuldeep Jain, Founder and Managing Director, CleanMax, said, “Cement plants run continuously, so the power behind them has to be dependable for decades, not years. We’re seeing manufacturing industries view clean energy as an integral part of their core operations and long-term strategy. Our partnership with Nuvoco reflects that shift, and we’re pleased to support its decarbonisation journey. This wind-solar hybrid project is designed to deliver long-term cost certainty while supporting the Company’s transition to cleaner power.”

Nuvoco has been advancing its sustainability initiatives through renewable energy, operational efficiency and technology-driven solutions. The company operates across Cement, Ready-Mix Concrete (RMX) and Modern Building Materials (MBM) segments, with a presence across East, North and West India.

The company began operations in 2014 with a greenfield cement plant in Nimbol, Rajasthan, and later acquired Lafarge India Limited, which entered India in 1999, along with Emami Cement Ltd in 2020 and Vadraj Cement Limited in April 2025. With planned expansion initiatives, including a new grinding mill at the Arasmeta Cement Plant and multiple debottlenecking projects, Nuvoco aims to achieve a cement capacity of 35 MMTPA.

The company reported total income of Rs 113.62 billion in FY 2025-26, reflecting its continued growth trajectory. Its cement portfolio includes Concreto, Duraguard, Double Bull, PSC, Nirmax and Infracem brands, while its RMX business offers products under Concreto, Artiste, InstaMix, X-Con and Ecodure brands. Nuvoco also provides construction solutions under its Zero M range of modern building materials.


Continue Reading

Video Thumbnail
▶

    SIGN-UP FOR OUR GENERAL NEWSLETTER

    Trending News