

Concrete
Gauging the Role of Low Carbon Solutions


Raman Bhatia, Founder & Managing Director, Servotech Power Systems, sheds light on the importance of low carbon solutions (LCS) in greening India’s cement industry.
India is the second-largest cement manufacturer in the world, with a 500 MTPA total production capacity that accounts for 30 per cent of the nation’s manufacturing-related emissions. Chemical processes and burning fossil fuels contribute to substantial carbon and GHG emissions during cement manufacturing. Thus, exploring options for reducing emissions and improving energy consumption is so crucial.
The moment is right for India to switch to green cement manufacturing, clearing the path for decarbonising one of its most challenging industries, as nations across the world aim to achieve their net zero aspirations. The manufacturing of cement in India has made it a leader in the world for both social and environmental responsibility. India is well on pace to reach its Nationally Determined Contributions (NDCs) objectives and remain in compliance with the Paris Agreement, thanks in large part to efforts made by critical industries
like cement.
Fast Tracking Green Cement
In August 2018, Dalmia Cement vowed to become a carbon-negative cement firm by 2040. Dalmia was the first business worldwide to endorse the Climate Group’s RE100 and EP100 campaigns, which call for the usage of 100 per cent renewable power by 2030.
Adoption of technical advancements targeted at greening the sector is necessary to unlock further potential for emission reduction. There is currently no comprehensive structure for certifying what constitutes cement a green product, despite the fact that the discussion of ‘green cement’ in the Indian context is not new and the preliminary groundwork has already been set out by a few cement companies. The majority of cement producers discovered ways to cut their carbon footprints by investing in carbon capture and storage technology, improving energy efficiency, and decreasing their clinker factor.
Electricity purchase agreements (PPAs), which are long-term agreements between industrial consumers and power suppliers, are one option to become green (PPA). The initial transactions were done roughly ten years ago, so this is not a brand-new one. They have, however, grown in size and frequency recently, with a global record capacity of 13.4 GW contracted in 2018. The Indian cement industry has always depended on the greatest technology and process setups to remain the most effective and sustainable throughout its development and expansion. To stay ahead and attain an equilibrium between technological and economic viability at scale, some Indian cement businesses have been conducting research and development on upcoming green technologies/products.
Additionally, mandating a minimum procurement of green cement under government-mandated infrastructure projects and private building projects is one approach to partially get around the demand-side barrier. The Renewable Purchase Obligation (RPO), which mandates that DISCOMs purchase a certain amount of their energy from renewable sources, would be comparable to this. India may think about releasing several classes of green cement that differ in terms of their superiority, ability to reduce CO2, and cost of manufacture. To ensure compatibility between versions and ease the transition, standards for product quality would need to be established in conjunction with this. Therefore, the nation should think about a targeted strategy for decarbonising its cement industry by going beyond only focusing on energy efficiency and fuel switching. The cement industry in India is one of the most energy-efficient in the world, and switching to green cement will help to further reduce carbon emissions.
In addition to calciners powered by clean energy, fossil-fired calciners are required since cement manufacturing facilities are open 24 hours a day. A diverse range of low-carbon solutions (LCS) including modern and cutting-edge technology, process adjustments, and behavioural changes will be needed to decarbonise the cement sector. Other approaches to reducing industrial emissions overall include technological ones like carbon capture, utilisation and storage (CCUS), or demand-side ones like increasing material circularity, resource efficiency improvements, such as lowering the material content of finished products, and material substitution.
Solar Policy Framework
Only a small number of policies make up India’s present policy mix for decarbonising the cement industries. Lack of a clear sectoral decarbonization strategy or plan for the industry is the biggest gap. The sectoral roadmaps that do exist were drafted by civil society, but neither the government nor the business community have formally approved them. Additionally, India has very little corporate financing and regulatory support for the R&D of early-stage low-carbon technology. R&D is often kept mostly for updating plant equipment and refining internal processes, and is typically predominantly conducted out by big industrial entities, through their own corpus.
Investors are significantly favoured by Indian legislation regarding solar power plants since they provide several advantages over traditional machinery and plants. For solar plants, an accelerated depreciation of about 80 per cent is taken into account, as opposed to 15 per cent for regular plant and machinery, which results in significant tax savings for the cement makers.
The Perform, Achieve and Trade (PAT) plan, a cap-and-exchange mechanism for decreasing particular energy consumption of energy-intensive industries by establishing objectives and allowing organisations to trade energy saving certificates, is the government’s cornerstone industrial decarbonisation programme (ESCerts). The cement and concrete industries, in particular, greatly exceeded their expectations for energy reductions during the first PAT cycle (2012–2015). Although this is admirable, it also caused an excess of ESCerts. To encourage investments in low-carbon technology, however, the market price of ESCerts was too low. Setting more challenging goals and a floor price for ESCerts to encourage a minimum degree of technology uptake is thus a crucial lesson for next cycles. Furthermore, PAT may evolve to function as an emission, rather than an energy-oriented programme with a purpose to show national and sectoral climate action and establish a national carbon market.
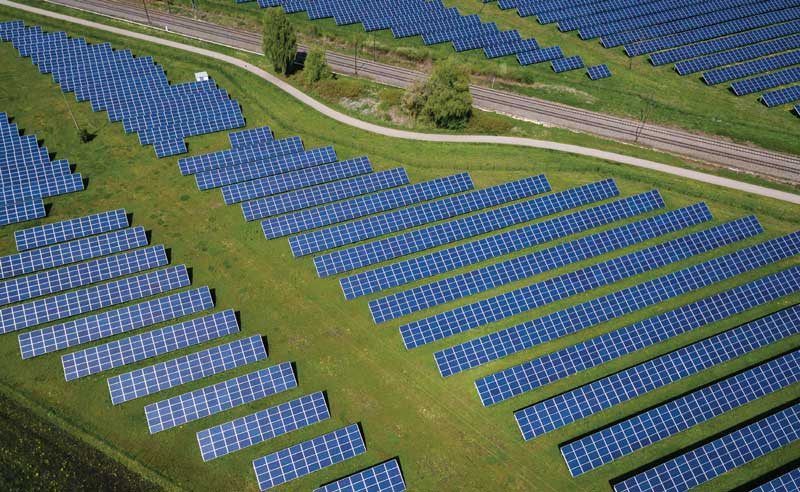
Installation of solar power plants can result in significant reduction of taxes for cement makers.
How Solar can Decarbonise Cement Manufacturing
When compared to traditional power sources, solar energy offers several advantages. The cost of solar energy has been decreasing, and in many regions of India, it is now less expensive than the industrial sector’s electricity bill. Unlike power from utility companies, where the price is only anticipated to rise annually, solar facilities have a lifespan of generally 25 years, locking in the energy rates. Cement factories can lower their GHG emissions while simultaneously fulfilling their commitments under the RPO and PAT processes by putting up solar power plants and solar water heating systems. We may establish a solar power plant in a cement mill based on the available space while taking into account the solar technology appropriate for that particular geographic topography.
Some potential uses for solar energy in cement plants include – using rooftop solar PV panels to power CCR, administrative buildings, and remote illumination applications, such as mines; meeting requirements for lighting in non-plant structures, internal roadways, water pumps, guesthouses, townships, parks, canteens, hospitals, and schools, among many other places, catering to energy requirements for utilities and auxiliary equipment; preheating of raw materials or boiler feed water; and meeting hot water requirements.
Here are a few benefits SOLAR ENERGY can bring to the Indian cement industry:
l Cost savings: The cost of energy for industrial customers is among the highest of any industry, and solar will be less expensive for them in the majority of states. With the exception of wear and some replacement, solar expenses are predicted to remain relatively stable during the course of the solar farm, whereas the cost of energy from conventional sources of electricity is predicted to increase year after year.
- Renewable Purchase Obligations (RPO) Compliance: Several industrial energy users must meet their RPO, and one of the simplest ways to do so is to establish a solar plant.
- Availability of Roof Space: Contrary to most commercial businesses, most manufacturing facilities have substantial areas of undeveloped land and open roof areas. In these open, uninhabited areas, solar plants may be set up with relative ease.
- Energy Savings: Locally produced solar energy helps balance grid electricity demand and reduce reliance on diesel generators. This then results in even greater cost reductions.
- Carbon Footprint Reduction: Most companies make an effort to lessen their carbon impact. Solar power facilities reduce carbon emissions while also assisting in environmental protection.
The adoption of solar solutions will be influenced by a wide range of contextual factors as they move up the R&D ladder and prepare for deployment, including the level of ambition of players in the industry and associations, institutional capacities, capital market maturity, national climate goals, and supportive sectoral policies and frameworks. Therefore, to reform the cement industry, adequate public policy and financial assistance must be provided.
This support entails fiscal and market-based actions, such as public R&D spending, R&D support for businesses through subsidies and investment tax credits, the imposition of a carbon price through taxes or cap-and-trade markets, and the creation of demand for green products through public procurement programmes. The use of standards, codes, and labelling programmes, such as industry-specific energy or emissions standards, requirements for the use of alternative fuels and materials, end-use sector-specific codes, green building codes, and labelling programmes for industrial products, are additional effective measures.
There are various ways that solar thermal technology may be used for industrial operations. It can be used to pre-heat the boiler feed water in a captive power plant or a waste heat recovery system, as well as to supply warm water for processes and hot air for drying raw materials. India has developed a number of solar thermal power facilities that make use of both concentrator and flat plate collector technology. It will still be a trustworthy source of grid-connected power.
Shaping Up the Industry’s Future Outlook
India has consistently taken significant measures to expand collaboration in order to raise R&D funding, generate markets, and improve the cost of low-carbon industrial goods. Most significantly, India supported the Breakthrough Agenda at COP26 in 2021, pledging to engage with other nations to hasten the development and adoption of clean technology and sustainable solutions in important industries like steel and cement.
Now, the cement industry in India are actively planning for an impending transition in response to this. Large industrial participants have committed to voluntary medium- to long-term decarbonisation goals and are appealing to the local and global credit markets for green funding. JSW Steel and Ultratech are notable instances that, like the aforementioned Dalmia Cement, have recently obtained large sums of money from foreign markets through the issuance of sustainability-linked bonds. These are important advances since huge firms’ direct contributions will be essential to the long-term deployment of LCS at scale. However, investments in the near future are likely to concentrate solely on mature and accessible LCS unless they are backed by creative finance mechanisms that reduce the cost of adopting solar as a power-generation source.
ABOUT THE AUTHOR:
Raman Bhatia, Founder and Managing Director Servotech Power Systems, comes with 20 years of entrepreneurial experience. He makes smart and sustainable clean power solutions accessible and affordable for the masses.











Meghalaya Cabinet Approves MCCL Closure, Writes Off Rs. 244.3 mn

Fornnax Wins AIRIA’s Special Export Award for Rubber Machinery in 2025-26

Cement Prices Likely to Rise Rs. 10-15 per Bag from Mid-October

Nuvoco Marks 10 Years, Targets 35 MMTPA Capacity by FY28

J&K Government Notifies City Gas Distribution Policy
Meghalaya Cabinet Approves MCCL Closure, Writes Off Rs. 244.3 mn
Fornnax Wins AIRIA’s Special Export Award for Rubber Machinery in 2025-26
Cement Prices Likely to Rise Rs. 10-15 per Bag from Mid-October
Nuvoco Marks 10 Years, Targets 35 MMTPA Capacity by FY28
J&K Government Notifies City Gas Distribution Policy
-

 Concrete3 weeks ago
JSW Cement Receives Rs. 2.3 bn GST Demand Notice
-

 Concrete3 weeks ago
Andhra Pradesh Clears Rs. 30 bn My Home Cement Plant
-
 Concrete1 month ago
Jammu Division Begins First Cement Rail Traffic to Anantnag
-

 Concrete3 weeks ago
Montra Electric, Wonder Cement Deploy 250-Vehicle EV Fleet