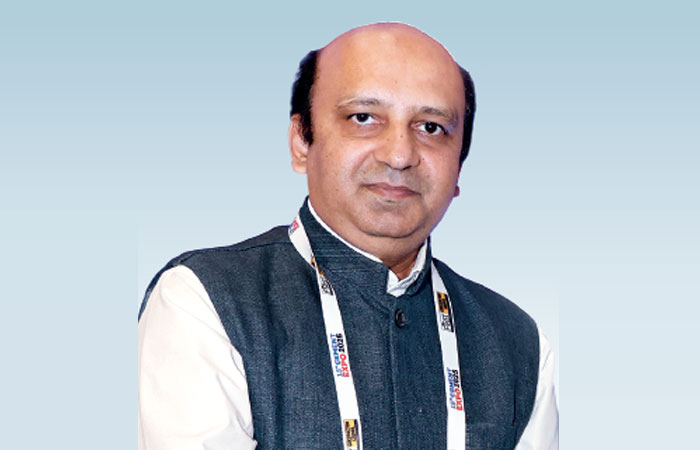
As the Indian cement industry moves toward higher efficiency and lower carbon intensity, Milan R Trivedi, Vice President – Projects, Prod & QC, MR, Shree Digvijay Cement, discusses the impact of modernisation as a strategic imperative.
In this conversation, Milan R Trivedi, Vice President – Projects, Prod & QC, MR, Shree Digvijay Cement, explains how modernisation, spanning digital control systems, energy efficiency measures and advanced operational practices, is helping the company improve productivity and strengthen its sustainability performance.
What are the key drivers pushing cement plants in India to prioritise modernisation at this stage of industry evolution?
India’s cement sector sits at a strategic inflection point, transitioning from volume-led growth to value-led competitiveness. The Indian cement industry is at a pivotal inflection point driven by scale expansion, sustainability imperatives and cost competitiveness. With India emerging as the world’s second-largest cement producer, increasing infrastructure push under programmes like PM Gati Shakti and urbanisation demand higher capacity utilisation with superior efficiency.
Major drivers to prioritise modernisation for cement industries focus around environment, efficiency and cost.
Carbon reduction commitments aligned with India’s Net Zero 2070 vision and growing shareholders focus on ESG performance and Stringent environmental norms from the Ministry of Environment and CPCB, pushes on modernisation and compliance front.
If we look at the numbers across India on cost and efficiency front the picture is depicted as
• India is the world’s second-largest cement producer with ~355–370 MTPA capacity, yet energy cost intensity remains approximately10 per cent to 12 per cent higher than global benchmarks.
• Energy and fuel account for approximately 30 per cent to 35 per cent of operating cost,
making modernisation less discretionary and more existential.
• Benchmarking shows best-in-class plants globally achieve specific thermal energy consumption
< 680 kcal/kg cli; many Indian plants still operate above 800 kcal/kg.
This isn’t incremental improvement. It’s
industry transformation to sustainably outperform global peers.
How is plant modernisation helping you balance cost efficiency, productivity, and sustainability targets simultaneously?
For us at Shree Digvijay Cement, we drill down cost efficiency, productivity and sustainability targets simultaneously and conclude to one parameter ‘EBIDTA,’ which brings the sense of ownership at all levels. And this is where the modernisation in terms of digitalisation and dashboard helps us in decision making and maintain a sustainable and efficient performance.
Focus on hourly monitoring of productivity and efficiency KPIs through WhatsApp and digital dashboards. Benchmarking on increasing usage of AFRs, increasing usage of renewable energy and reducing clinker factors through increasing portfolio of PPC and composite cement.
Modernisation enables simultaneous optimisation across the value chain. Benchmarking confirms that modernised Indian plants are closing the performance gap with global tier-I facilities, with simultaneous benefit to EBITDA margins and carbon intensity
Which technologies have delivered the most measurable impact in your upgraded facilities?
At Shree Digvijay Cement, we prioritise technology based on measurable, scalable and commercial outcomes. The decisions are driven for modern technology suitable to achieve impact on environment improvement, efficiency improvement and
cost optimisation.
We were the first in west region of country to establish waste heat recovery system (WHRS) and currently draw almost 35 per cent of total electrical consumption from WHRS. IoT-based predictive maintenance has been just at initial stage at our facility but we have focus to achieve about 20 per cent reduction in unplanned downtown.
Advanced operational controls like online raw mix optimiser, fuel control loops, process control loops helped in optimisation of operation by 4 per cent to 5 per cent improvement in kiln throughput and about 8-10 kcal/kg clinker reduction.
We are yet to explore Digital twins for improving our production and maintenance cycles.
These are not gadgets but core profit drivers with balance-sheet impact.
How do you evaluate ROI and payback periods when investing in large-scale plant modernisation projects?
The main focus in case of modernisation projects drives through the investment decision, which is mainly based on IRR and impact on overall efficiency improvement, cost optimisation and improvement in reliability. However, there are certain modernisation, which has high impact on environmental impact, statutory requirements, etc. has higher priority irrespective of ROI or payback period.
The energy efficiency and reliability investment projects generally provide fast return on investment whereas strategic, digitalisation and environmental investment projects provide long term and compounded benefits.
Typical modernisation investment projects are decided with IRR of about > 20 per cent, payback period of typically 2-3 years for fast-track projects.
What operational challenges do you face while upgrading brownfield plants without disrupting ongoing production?
Brownfield upgradation or modernisation projects always brings its own challenges. They are more complex and has constraint windows for completion. Major complexity and challenges are space constraints, limited execution time frame and interfacing of legacy equipment with new digital systems.
When it comes to such complexity and challenges, our driving factors like meticulous shutdown planning, modular installation and phased commissioning have resulted in delivering results.
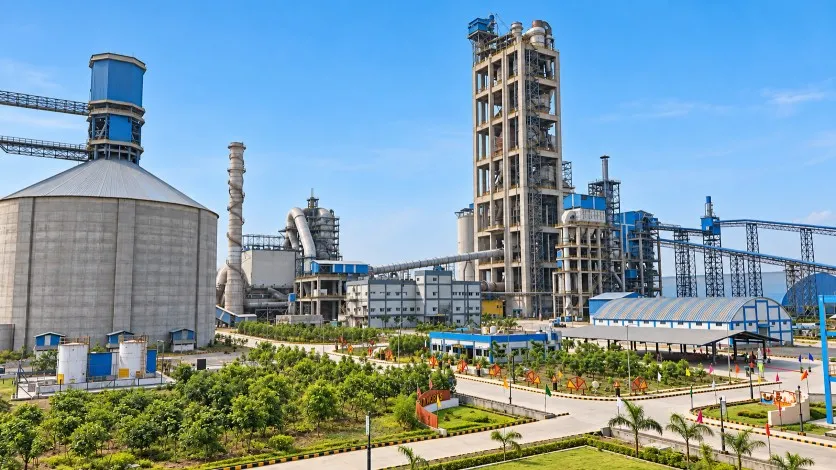
In past two years we have demonstrated the same by upgrading our plant control system from FLS Automation to ABB system for our existing 1.5 mtpa plant and upgrading our grinding capacity from 1.5 mtpa to 3.0 mtpa within same plant location.
The greatest operational risk is execution during live production windows, we mitigate it through phased commissioning, night-shift deployments, and modular executions and delivered committed production. The other execution challenges is movement of heavy erection equipment through exiting plant and limited approach in brownfield project. The cross-functional coordination between production, maintenance, and project teams ensures minimal output disruption and maximum execution results.
Our project governance adopts belt-and-road style execution discipline, detailed Gantt planning, stage-gate reviews and kill-switch risk controls to ensure production continuity and timely execution of project.
How is modernisation reshaping workforce skills, safety standards, and day-to-day plant management practices?
Workforce skills have demonstrated upgrades with the help of modernisation and digitalisation. Today’s plant manager invests 80 per cent of time in forward-looking optimisation decisions versus reactive problem-solving. Operators now work with digital dashboards, AI predictive alerts and real-time KPI analytics, and not analogue gauges. A clear shift from manual control to data-driven decision-making is evident.
Safety performance has improved measurably and enhanced through real time monitoring and interlock systems. Safety dashboards including near-miss reporting and digital lockout/tagout protocols have reduced LTI metrics year-on-year. CII studies show plants with digital training programmes reduce safety incidents by >30 per cent and improve operator utilisation, directly correlated to culture change.
The day-to-day plant management practices has improved the productivity by automated report generation. At Digvijay Cement, we now use this productivity to monitor and track not only KPIs on day-to-day basis but also EBIDTA monitoring up to the department level to hammer the ownership.
In what ways are modernised plants contributing to lower carbon emissions and alignment with ESG commitments?
We benchmark our carbon intensity against decarbonisation pathways, affirming that modernised plants deliver quantifiable carbon abatement rather than aspirational targets. Modernised plant comes with efficient, controlled and flexible operational method in cement grinding for reducing clinker factor by increasing supplementary cementitious material like fly ash, slag in addition to gypsum. Fuel mix optimiser, high momentum burners and AFR co-processing have helped in reduction of fossil fuel consumption. Both clinker factor and AFR co-processing are key drives in reducing Scope 1 emission intensity.
Today Digvijay Cement has its total grid energy replacement to the level of 60 per cent by installation of WHRS system in plant and utilisation of captive and contractual hybrid source of renewable energy such as wind energy and solar energy.
These initiatives align with global frameworks such as the GCCA roadmap and India’s Nationally Determined Contributions (NDCs). Transparent carbon accounting and digital monitoring strengthen ESG disclosures.
What role do partnerships with technology providers play in ensuring long-term efficiency and future readiness of your plants?
Future readiness depends on adaptability. Plants must be upgradeable, data-compatible and scalable. Strong partnerships ensure that modernisation is not a one-time event but a continuous journey. Strategic partnerships are critical. Technology providers
bring global benchmarking, R&D capabilities and upgrade pathways.
In our strategy, technology partnerships are not transactional. They are strategic alliances. Execution of project based on package mode rather than transactional procurement. Annual Rate Contracts for long term and timely availability of spares and consumables which also gives leverage to cost control.
We benchmark partner performance against global innovation, ensuring we always stay at the innovation frontier.
Cement plant modernisation is about upgrading equipment ad redefining competitiveness.
At Shree Digvijay Cement, the philosophy
is clear:
• Every modernisation must enhance EBITDA.
• Every efficiency gain must lower carbon intensity.
• Every investment must strengthen long-term resilience.
Modernisation is a leadership mindset. The next decade will not reward the largest producer; it will reward the most efficient, sustainable and digitally enabled ones.













 Concrete4 weeks ago

 Concrete4 weeks ago

 Concrete4 weeks ago

 Concrete4 weeks ago