Connect with us

Concrete

Ambuja Cements posts record Q2, lifts FY28 capacity target

PAT rises to Rs 23.02 bn; volumes up 20%; margin widens 450 bps

Published

on

Shares
Ahmedabad, recently — Ambuja Cements, part of the Adani Portfolio, reported a strong Q2 FY26 performance with consolidated PAT of Rs 23.02 billion (up 364 per cent year on year), highest-ever Q2 sales volume of 16.6 million tonnes (up 20 per cent) and revenue of Rs 91.74 billion (up 21 per cent). EBITDA rose to Rs 17.61 billion with a margin of 19.2 per cent, while EBITDA per tonne reached Rs 1,060 (up 32 per cent). EPS stood at Rs 7.2 (up 267 per cent). The PAT figure includes an income-tax provision reversal of Rs 16.97 billion.
The company raised its FY28 capacity goal by 15 MTPA to 155 MTPA, largely through low-capex debottlenecking at about USD 48 per tonne. Thirteen new blenders are being installed to optimise product mix and lift the share of premium cement, and logistics debottlenecking is expected to add around three per cent utilisation to the existing 107 MTPA base over 24 months.
On projects, a 4 MTPA kiln at Bhatapara has begun trial runs, the 2 MTPA Krishnapatnam grinding unit has been operationalised, and an additional 7 MTPA across three locations is slated for Q3. Renewable power capacity reached 673 MW after commissioning 200 MW, with targets of 900 MW by year-end and 1,122 MW by FY27.
Cost discipline continued: kiln fuel, power and logistics costs declined year on year; green power share of consumption rose to 32.9 per cent; and logistics cost stood at Rs 1,224 per tonne. Management reiterated end-FY26 total cost guidance of about Rs 4,000 per tonne and a pathway to Rs 3,650 per tonne by FY28, supported by higher coal share, newer assets, shorter lead distances (including a growing sea-logistics share), and long-term fly ash/slag tie-ups.
Strategically, Ambuja launched CiNOC (Cement Intelligent Network Operations Centre) to embed AI across sales, production and logistics; deepened engagements with CONCOR, CREDAI and 400+ academic partners; and ordered seven vessels totalling 65,800 DWT to lift coastal movement to five per cent. The company remains debt-free with net worth of Rs 694.93 billion and the highest Crisil ratings (AAA/Stable; A1+).

Concrete

Centre Defers Clearance for Limestone Mine Near Bustard Habitat

Panel seeks revised mining plan and safeguards for pipelines and wildlife
Published

on

By

Shares

The Centre has deferred environmental clearance for a proposed limestone mine near a Great Indian Bustard habitat in Ramgarh, Rajasthan’s Jaisalmer district. The critically endangered species has an estimated wild population of about 130 in India.

Continue Reading

Concrete

Telangana to Supply Subsidised Cement for Indiramma Houses

Poor families allotted Indiramma houses to receive cement at Rs. 230 per bag
Published

on

By

Shares

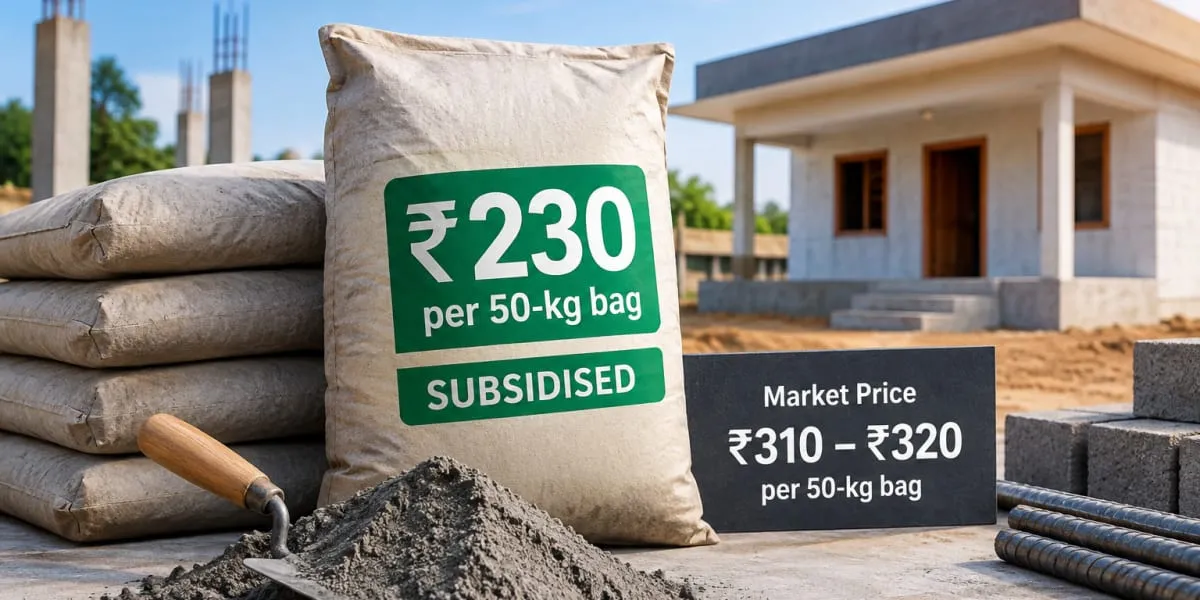
The Telangana government will supply cement at a subsidised price of Rs. 230 per 50-kg bag to poor and low-income families allotted Indiramma houses. The prevailing market price is between Rs. 310 and Rs. 320 per bag, the Assembly was informed on Thursday.

Continue Reading

Concrete

Cement Demand Strong As Prices Remain Stable

Volumes rise amid steady trade pricing and higher fuel costs

Published

on

By

Shares

Channel checks show cement demand remained healthy with volume growth estimated at six to seven per cent in July and August 2026. Trade prices were broadly stable while non-trade prices were volatile in the East, and attempted hikes were rolled back amid higher competition. Average fuel costs rose in August by five to nine per cent, lifting spot petcoke and coal prices.

All-India trade price remained flat month on month in August as increased rake supplies and competition offset early increases. Monsoon related demand softness limited sustained hikes and dealers indicated further attempts would depend on demand trends. Combined July and August volumes were estimated at six to seven per cent, supported by infrastructure spending while retail housing remained weather sensitive.

In the South, a Rs20 a bag hike in August did not hold and prices stayed flat month on month, while dealers planned Rs25 to Rs30 a bag from fifth September 2026 but with uncertain sustainability. In the East, trade prices were unchanged and non-trade prices corrected by Rs15 to Rs20 a bag amid weak construction in West Bengal, Jharkhand and Odisha.

The West remained most resilient on pricing and demand despite attempted hikes of Rs10 to Rs15 a bag, and Gujarat saw relatively better volumes in August. North and Central markets kept prices range bound as players focused on ramping up utilisation of new capacity, with schemes of up to Rs2 to Rs3 a bag used to meet month-end targets. Overall construction activity improved as the monsoon eased, aiding a pickup in several states.

Fuel cost pressures persisted, with South African coal at USD114 a t and petcoke around USD146 to USD147 a t in August, while spot imported petcoke and coal were higher. Imported coal consumption cost stood at Rs2.07 per Kcal and petcoke at USD2.11 per Kcal. Analysts estimate the all-India trade spread to decline by Rs90 to Rs100 a t quarter on quarter, weighing on near-term profitability and they prefer UltraTech Cement (UTCEM), JK Cement (JKCE) and Grasim Industries (GRASIM).

Continue Reading

Video Thumbnail
â–

    SIGN-UP FOR OUR GENERAL NEWSLETTER

    Trending News

    SUBSCRIBE TO THE NEWSLETTER


    Don't miss out on valuable insights and opportunities to connect with like minded professionals.


      This will close in 0 seconds