Connect with us

Concrete

Future of cement distribution is exciting and challenging

Published

on

Shares

Syaam Prakash V, Vice President – Marketing, NCL Industries, speaks about their preferred distribution channels and the impact that technology is likely to have on the processes in the near future.

How many channels of distribution do you prefer to have for your product and how do you choose them?
Our channels for distribution of cement can be broadly classified into six types, selection of which is based on the channel’s reach, efficiency and cost optimisation and is finally driven by
consumer’s preference.

Which is your most preferred channel of distribution and why?
Our most preferred channel of distribution is through dealer to consumer. This channel has been our mainstay for several years and constitutes 80 per cent of our dealer network of over 2200. It gives us immense reach into rural Andhra Pradesh and Telangana. Now the company is focused to develop channel wholesaler – retailer to consumer. This is predominantly in urban markets where the company is focused to increase its presence. 75 per cent of our business is from channel sales, hence, we continue to strengthen it by adding close to 250 dealers a year across south India.

How do you select your distributors? Tell us about the parameters and selection process.
The following are the parameters to evaluate distributors selection:
» Retail network size, store locations and retail store space
» Synergy to existing network, niche clientele base
» Financial strength and potential to grow. Scope to add other products of NCL (cement article board, NCL doors etc) and group company products (AAC blocks, wall putty, paints,
UPVC etc)
» Current cement dealerships and their positioning vis-à-vis Nagarjuna Cement.

What are the major challenges in the line of distribution of cement?
The major challenges that we have faced in our distribution channels are:
» Timely, cost effective and seamless reach to consumers
» Continued channel partners loyalty
» Penetration, reach and depth in retail space
» Efficient last mile connectivity and service to consumers

What are the software and other IT solutions used to understand the cement distribution?
Currently we are not using any software specifically for cement distribution. We are evaluating
several options.

How is the acceptance of online sales of cement?
India has the third largest online shopper base of 140 million subscribers contributing to US $ 50 billion in turnover 2020. The segment is growing 35 per cent annually and the Indian digital economy is estimated at US $537 billion. However, the major share of which is from groceries, educational technology and personal care, beauty and wellness (PCB&W) segment etc. The online sales of cement is growing gradually in India as most of the customers still prefer to shop at brick and mortar stores.

Who are the major buyers of cement online?
Thus far, major buyers of cement online in India are Individual House Builders (IHB) and institutional buyers.
As we can see, bulk of cement is bought by central and state governments for low-cost housing, infrastructure etc. Urban housing (builders) and industrial buyers are yet to take up online buying in a big way and the space is still evolving as the same involves credit and contract buying.
Hence, purchase of cement online will increase in the years to come as penetration of smartphones and 5G network improves in rural markets.

How do you foresee the future of cement distribution?
Cement distribution has been evolving over the last few decades. We are graduating from being commodity (cement) sales to product marketing in the cement space. Further, due to various new applications (RMC, cement sheets, cement particle boards, AAC blocks, prefabricated structures, 3D printing, white top highway roads etc.) cement is moving into bulk sales (naked cement).
There are a lot of green initiatives in cement production and applications. New products are being developed and promoted for the benefit of individual as well as industrial customers.
India is second largest producer of cement in the world with 550 MMT per annum installed capacity and consumption is estimated to grow at 9 per cent CAGR in next few years (current per capita cement consumption is 250 kg against world average of 550 kg) hence the future of cement distribution is exciting and challenging.

Concrete

Cement Firms to Invest Rs. 130 bn in Green Energy by FY28

Cement companies plan to expand clean energy capacity to 6 GW by FY28
Published

on

By

Shares


India’s major cement companies are set to raise their clean energy capacity to 6 GW by March 2028 from around 4 GW at the end of March 2026, according to ratings agency ICRA. The planned expansion is expected to involve investments of Rs. 130 bn over the next two years.

The additional capacity could generate annual savings of Rs. 62 bn to Rs. 67 bn, resulting in an estimated payback period of 1.8 to 2.2 years. Cement is an emission-intensive industry, and leading producers have established net-zero roadmaps covering the next 15 to 20 years.

The calcination process accounts for 57 to 60 per cent of the sector’s total emissions, while fuel combustion contributes 27 to 30 per cent and electricity consumption accounts for 10 to 13 per cent. ICRA said the figures highlighted the need for a broad decarbonisation strategy involving green power, blended cement, alternative fuels and improvements in clinker efficiency.

Green energy is considered one of the most commercially attractive decarbonisation options because it can reduce emissions while lowering operating costs. Every 5 per cent increase in green power replacement can reduce power and fuel costs by Rs. 15 to Rs. 16 per tonne. A 25 per cent replacement level could therefore save Rs. 75 to Rs. 80 per tonne and expand operating margins by 140 to 160 basis points.

Cement producers are also assessing carbon capture, utilisation and storage, although high implementation costs, energy requirements and limited transport and storage infrastructure are expected to slow commercial adoption. The government has proposed Rs. 200 bn over five years to support deployment across key sectors. Meanwhile, companies are targeting thermal substitution rates of 10 to 15 per cent over the next three to five years, compared with the current industry level of around 6 per cent.

Continue Reading

Concrete

Centre Defers Clearance for Limestone Mine Near Bustard Habitat

Panel seeks revised mining plan and safeguards for pipelines and wildlife
Published

on

By

Shares


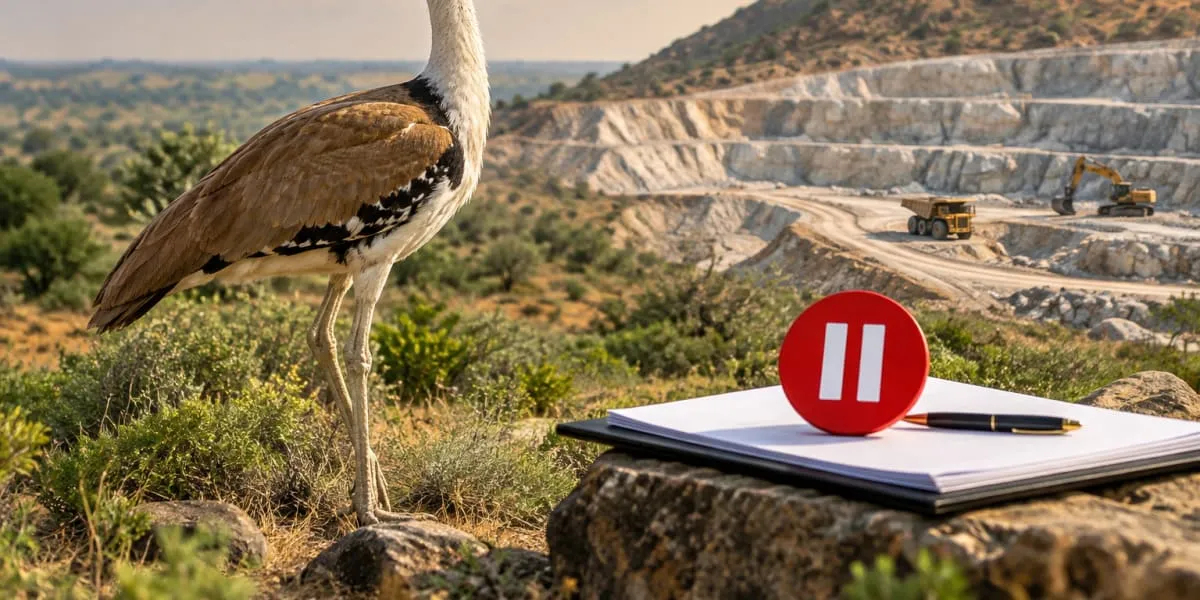
The Centre has deferred environmental clearance for a proposed limestone mine near a Great Indian Bustard habitat in Ramgarh, Rajasthan’s Jaisalmer district. The critically endangered species has an estimated wild population of about 130 in India.

Continue Reading

Concrete

Telangana to Supply Subsidised Cement for Indiramma Houses

Poor families allotted Indiramma houses to receive cement at Rs. 230 per bag
Published

on

By

Shares


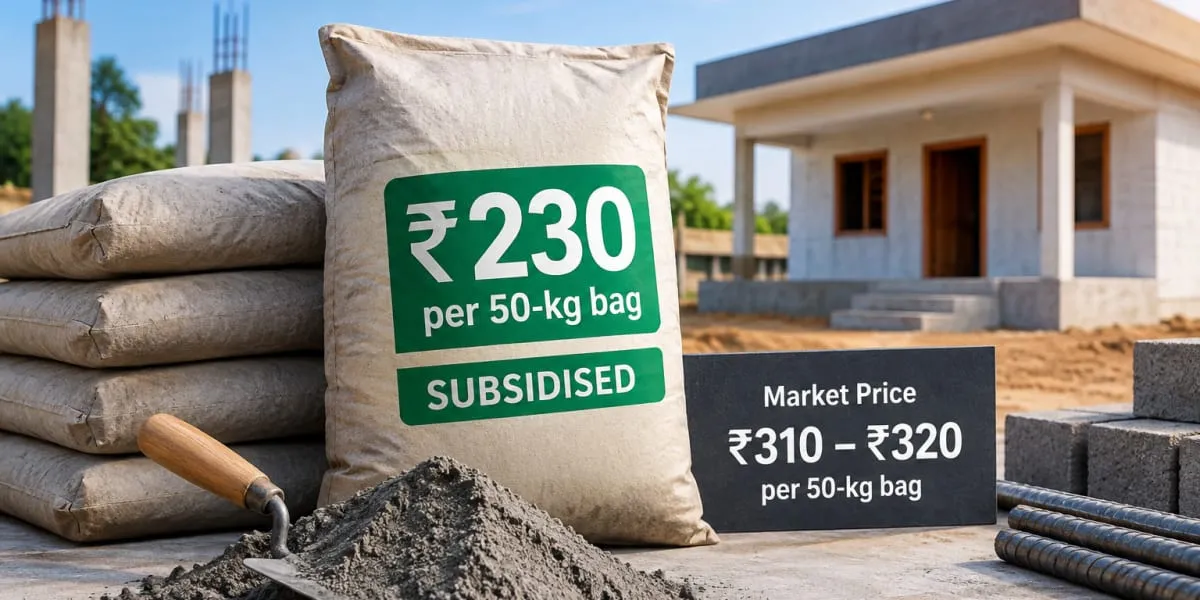
The Telangana government will supply cement at a subsidised price of Rs. 230 per 50-kg bag to poor and low-income families allotted Indiramma houses. The prevailing market price is between Rs. 310 and Rs. 320 per bag, the Assembly was informed on Thursday.

Continue Reading

Video Thumbnail
â–

    SIGN-UP FOR OUR GENERAL NEWSLETTER

    Trending News

    SUBSCRIBE TO THE NEWSLETTER


    Don't miss out on valuable insights and opportunities to connect with like minded professionals.


      This will close in 0 seconds