Economy & Market
Demand uptrend persists, amid price pressures
Published
8 years agoon
By
admin
Cement demand that has started picking up in the third quarter (October-December 2017) of fiscal 2018 (FY18) continued its growth streak in the fourth quarter of the fiscal, according to analysts. However, cement realisations failed to post commensurate rise, and prices, which should have seen an uptrend in the last quarter of the year, have remained subdued.Sabyasachi Majumdar, Senior Vice President & Group Head, ICRA Ratings, says, "A demand pick-up in the recent months, October 2017 to January 2018 by 13.4 per cent, is backed by low cost housing in the eastern markets, Andhra Pradesh and Telangana along with the infrastructure demand from the eastern, southern and western markets."
Discussing the latest demand trends, CLSA’s Vivek Maheshwari and his team says, "The industry has seen a pick-up in volume growth, also reflected in 11 per cent volume growth expected for our coverage in 4QFY18 (January-March 2018 quarter). While a low base helped (these volumes), the two-year Compounded Annual Growth Rate (CAGR) should still be at a respectable ~8%." Besides, cement realisations have not seen any quarter-on-quarter (QoQ) uptick despite favourable seasonality.
The demand environment continued to remain favourable in March 2018, said Binod Modi – Senior Research Analyst, Reliance Securities, in a recent report, adding, however, the pricing trend remained subdued marked by sharp month-on-month (MoM) contraction during the month. Volume push owing to year-end month, and fair chances of price hike from April 2018 also aided volume growth.
"Demand growth was aided by both trade and non-trade segments and most dealers expect the demand momentum to remain benign till the onset of monsoon, while the prices are expected to bounce back from first or second week of April across the regions barring Central," said Modi.
"A pick-up in the affordable and rural housing segments and infrastructure – primarily road and irrigation projects – is likely to continue the demand growth momentum of around 5 per cent in FY2019," says Majumdar.
Budget FY2019 has provided higher rural credit target, increased MSP, and allocation for rural, agricultural and allied sectors, and stressed on continued focus on the PMAY and infrastructure investments, all positive for cement demand growth. Price falls
There was a disappointment on the price front for the cement companies in the Q4FY18. March quarter is traditionally the busiest quarter for construction, and hence cement prices usually firm up sequentially, but not this time.
All-India average cement price corrected by about 3 per cent MoM to ~Rs 286-291/bag mainly due to sharp correction in Western and Southern realisation, which corrected by ~6 per cent and 5 per cent MoM, respectively in March, while average prices in Northern, Central and Eastern regions corrected by ~1 per cent MoM each, according to Reliance Securities. Besides, all-India average price declined by 1 per cent YoY (Rs 3-5/bag) and 0.3 per cent QoQ in 4QFY18.
Average price in Southern region corrected sharply by 5 per cent QoQ, while it corrected by 1-1.5 per cent QoQ in Western and Northern region during 4QFY18. However, Eastern and Central regions witnessed average price improvement of ~3 per cent and ~4 per cent QoQ, respectively during 4QFY18.
CLSA said that their channel checks had indicated that "efforts are underway to raise prices by 5-20 per cent in South India and Maharashtra," the regions which saw the highest pressures on EBITDA, follow the sharp cuts in March. However, the channel is still apprehensive on sustainability of such hikes.
"Overall, while cost inflation remains a concern, we believe that price hikes are imminent across regions and unit margins should expand in FY19," says Maheshwari.
Though government seems to be vigilant about any price hike by the cement companies for last couple of months, Modi of Reliance Securities expects "prices to witness an upward movement in coming months due to rising cost pressures
and sustained demand growth leading to higher utilisation."Cost pressures
"Overall earnings before interest, tax, depreciation and amortisation (EBITDA or operating profit) for our coverage should rise by a modest 7 per cent year-on-year (YoY) although net earnings will likely decline," Maheshwari says in the report. This is mainly due to high costs particularly those of pet coke, imported coal and diesel, however, rising volumes are expected to come to manufacturers’ rescue during the quarter to an extent. Due to lack of price hikes during the quarter EBITDA margins are expected to decline by 7-8 per cent YoY and QoQ to a 13-quarter low, for CLSA’s universe of cement stocks, Maheshwari said in the report.
Majumdar also predicts that expectation of higher pet coke, coal and diesel prices are likely to put pressure on the profitability margins and debt metrics of the cement companies in the coming quarters.
"Lumpy capacity additions in the recent past have led to an increase in debt levels and some deterioration in credit metrics, although they still remain at comfortable levels for most of the larger players. Further, higher power and fuel (increase in coal and pet coke prices) and freight costs (increase in diesel prices) in FY2018 and in the coming quarters of FY2019 is likely to continue to put pressure on the profitability margins and debt metrics of the cement companies. Hence, the ability of the industry players to secure increases in cement prices remains critical from the profitability perspective," Majumdar reiterated.
Given all these scenarios, ICRA expects that the capacity overhang and the moderate demand growth to continue to keep the industry’s capacity utilisation level close to 65 per cent over the medium-term (3-5 years).
You may like
-
Cement Demand Strong As Prices Remain Stable
-
AI is solving longstanding challenges
-
Customer requirements are the primary driver.
-
Cement Makers’ Margins To Fall Rs 50-75 Per Tonne Amid West Asia Conflict
-
Cement Sector Faces Sluggish Growth in First Half of FY27
-
Indian Railways Plans Green Fly Ash Transport Network
Concrete
UltraTech Cement achieves 100% green energy milestone at Chhattisgarh plant
Published
16 minutes agoon
September 29, 2026By
admin
UltraTech Cement’s Kukurdih Works becomes its first integrated unit to meet 100 per cent electricity needs through green energy every month.
Raipur (Chhattisgarh)
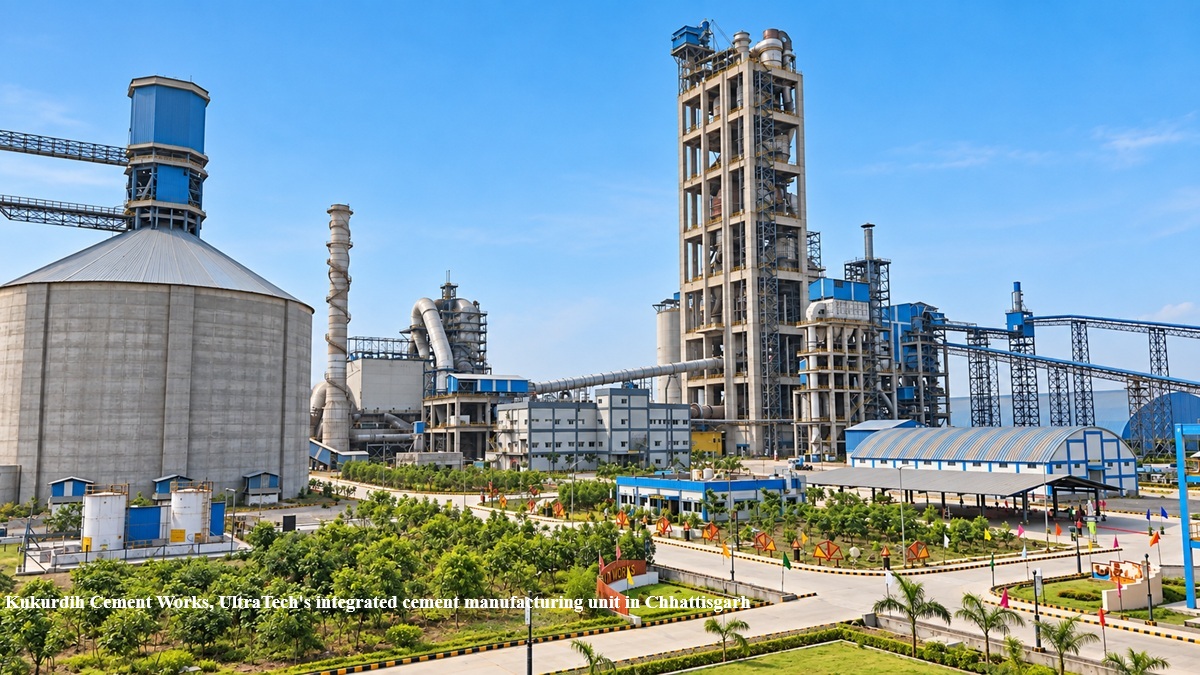
UltraTech Cement Limited, the world’s largest cement company outside China, has achieved a significant decarbonisation milestone, with its Kukurdih Cement Works integrated unit in Chhattisgarh meeting 100 per cent of its electricity requirement through green energy every month since April 2026.
Commissioned in 2024, Kukurdih Cement Works has an installed grey cement capacity of 3.3 million tonnes per annum. The unit achieved this milestone through a combination of renewable power sourcing and Waste Heat Recovery Systems (WHRS), which now collectively meet its entire electricity demand while ensuring operational reliability.
Since April 2026, nearly one-third of UltraTech’s 76 manufacturing units in India have maintained green energy utilisation above 50 per cent of their electricity requirements. Five units, including Kukurdih, have exceeded 95 per cent green energy utilisation. The company is also progressively deploying Battery Energy Storage Systems (BESS) across its network to enable deeper renewable energy integration.
As part of its decarbonisation strategy, UltraTech has not invested in additional captive thermal power capacity for greenfield projects or brownfield expansions at its integrated units for over a decade.
As of Q1FY27, the company’s captive green energy capacity stood at 1,897 MW, comprising 1,463 MW of renewable energy capacity from solar, wind and hybrid sources, along with 434 MW of WHRS capacity. Under its RE100 commitment, UltraTech aims to increase the share of green power in its total energy mix to 85 per cent by 2030 and achieve 100 per cent by 2050.
UltraTech Cement Ltd, the cement flagship company of the Aditya Birla Group, is a $10-billion building solutions company and the largest cement producer globally by sales volume outside China. The company has a total grey cement capacity of 210.1 MTPA and white cement/putty capacity of 3.5 MTPA. It is a signatory to the GCCA Climate Ambition 2050 and has committed to the Net Zero Concrete roadmap announced by GCCA.
Praveen Vashistha, Founder, Gxpress Solutions, speaks about building a holistic logistics network that encompasses latest technology and current challenges faced by logistics service providers.
Logistics may seem to only entail transporting a package from one location to another. However, there is more to this term than just that. Logistics refers to the entire process of controlling all movement, transfers and decisions in the correct way at the right time and cost and with the desired level of visibility.
People nowadays want to receive more than just the delivery. They want quick, efficient, reliable and transparent logistics service. On the other hand, companies are facing higher operating costs, broken supply chains, congested cities, changing habits of consumers and growing complexity of logistics services. In this situation, a full logistics package is gaining importance not only as a competitive advantage but also as a necessity for a successful business.
The main challenge lies in uniting the first mile, the middle mile and the last mile into one seamless process.
The journey begins before the package moves
First-mile logistics may be the least recognised part of the logistics chain, but they have a crucial influence on all that follows.
This stage starts from the moment the shipment leaves the manufacturer, supplier, farm, warehouse or distribution centre. Depending on the industry, first-mile logistics may involve grouping shipments from multiple suppliers, compiling paperwork and checking the inventory before sending the shipments to a central hub.
Flaws in first-mile logistics produce effects later down the supply chain. Delays in cargo pickup can affect warehouse operations; improper packaging can damage goods in transit; and incorrect inventory information may cause stockholding or unnecessary replenishments.
This is why building a reliable network involves simplifying the operations done at the beginning of the supply chain.
Companies require accurate demand forecasts, supplier visibility, standard procedures, and software to capture information from the moment a shipment enters the supply chain. Route planning and fleet management are also important at this stage, especially as it may involve contacting multiple suppliers.
The main goal is simply to make the first mile predictable.
The middle mile: Where scale meets complexity
When products leave the original site, they travel through the ‘middle mile,’ which connects fulfilment centres, warehouses, sorting centres, and regional distribution points. In this phase, logistics networks begin operating on a large scale. A shipment can pass through several facilities before reaching the final destination. Each additional transfer entails the risk of delay or damage and information losses. Accordingly, the ideal solution is not to minimise the number of transfers but rather to optimise them. The use of hub-and-spoke networks, regional distribution centres, and strategically placed distribution centres can help companies shorten transportation routes and optimise distribution costs. Besides, data can be used to determine the optimal placement of inventories.
For instance, a retailer may find that it takes more time and is more expensive to deliver goods to customers if everything is stored in a central warehouse. Meanwhile, regional distribution helps meet the customer’s needs quicker and more efficiently.
The last mile is where the customer judges you
When it comes to the logistics experience, the customer experience comes down to the delivery. While the last mile might comprise a small part of the entire journey in actual distance, it could also entail expensive and difficult processes. Delivery runs through densely populated cities, through traffic jams, through unsuccessful delivery attempts, and through changing consumer preferences and narrowed time frames.
Customers want to have control over their delivery. Delivery means that customers expect to know the exact moment when their order is delivered. They need to receive current updates about their orders and the ability to decide whether they want scheduled deliveries, or whether they want their order to be dropped off at a designated location far from their house.
As a result, last-mile logistics must incorporate both efficiency and experience. The technology may be used to ensure timely and accurate delivery, through such products as route optimisation and real-time delivery tracking.
However, technology is not enough to guarantee success in terms of last-mile delivery. Knowledge of the local area is still an important aspect that contributes to successful delivery.
One network, not three separate operations
First, the common mistake that organisations can make is treating the first mile, the middle, and the last mile separately.
An effective first mile of logistics does not matter much if the shipment waits in a hub for many hours. A perfectly working warehouse does not make a happy customer if the last-mile delivery fails. Therefore, even the fastest last-mile delivery can become an expensive operation if the supply is not well geographically positioned.
The three moments should work together as one whole system.
This implies having a common view on inventory, transport capacities, shipment statuses and demand. The Transportation Management System, Warehouse Management System and order management system should give information to each other instead of acting like separate islands.
That is where real-time information comes into play!
If something happens, such as a vehicle gets delayed, the company has to know that from the start. If not, someone from Customer Service should be informed about the situation.
Visibility is the new infrastructure
Previously, companies had to rely on physical assets, such as warehouses, trucks, and sorting facilities, to create their logistics networks. Today, they have an additional layer of technology providing visibility.
Command-and-control systems now include GPS tracking, Internet of Things devices, bar-coding, RFID, cloud computing, artificial intelligence, and analytics, which allow companies to know what the goods are doing, how well they are doing, and what is going to happen next.
Predictive analytics reveal possible delays. AI-powered forecasting increases availability. Digital dashboards enable the manager to monitor all operations in one place. The efficiency of such technologies is not measured in the amount of information they gather, but rather in their capability of converting data into knowledge.
Logistics managers should be able to answer the following questions: Where is it? When is it supposed to arrive? What causes the delay? What impact does it have? Can it be delivered some other way? How much will it cost?
The sooner the answers are given, the more resilient the logistics system is.
Resilience must be designed into the network
The events of recent years have highlighted the vulnerability of interconnected supply chains. Geopolitical tensions, bad weather, a lack of labour, poorly developed infrastructure and an unexpected spike in demand are some events that can cause problems for logistics systems without prior notice. Thus, companies should create an end-to-end network not just for normal times but also capable of functioning quickly in problematic situations. In order to create such a network, it is necessary to find alternative suppliers, use several means of transportation, create several routes of delivery, and establish inventory. It is also important to use scenario planning to define what to do if the main hub becomes unavailable or any means of transportation is blocked.
Sustainability: Part of the delivery equation
The future of logistics will also be shaped by environmental considerations.
As delivery volumes rise, businesses are under increasing pressure to reduce emissions without compromising service. Better route planning, load optimisation, electric vehicles, alternative fuels, renewable-energy-powered warehouses and consolidated deliveries can all contribute. The most sustainable shipment is often the one that does not require unnecessary movement in the first place.
Better demand forecasting and inventory placement can reduce empty miles and avoid repeated transportation. Consolidating deliveries can improve vehicle utilisation. Reverse logistics can ensure that products, packaging and materials return efficiently instead of becoming waste.
Sustainability, therefore, should not be treated as a separate initiative. It should be incorporated into network design itself.
The future belongs to connected logistics
An end-to-end logistics network ultimately seeks to close existing gaps between various processes.
Every mile of the process should be interconnected with the other miles. Warehouses should be aware of the restraints imposed by transportation. Delivery crews should be able to know at every moment the inventory at their disposal. Clients must have access to this useful information.
Companies that will be successful in this area will not necessarily be the ones with the biggest fleets or the most warehouses. They will simply be the ones that can employ their resources in the most effective manner.
The future of logistics will be represented by an ecosystem consisting of the combination of the physical aspect, digital intelligence, and personnel decisions. Every mile in the process of delivery is important. However, the key advantage here is getting those miles to work together.
For companies, it means having minimal resistance, enhancing their efficiency and improving customer care. For clients, it means simply having the right product delivered at the right time.
About the author: Praveen Vashistha, Founder, Gxpress Solutions,
Concrete
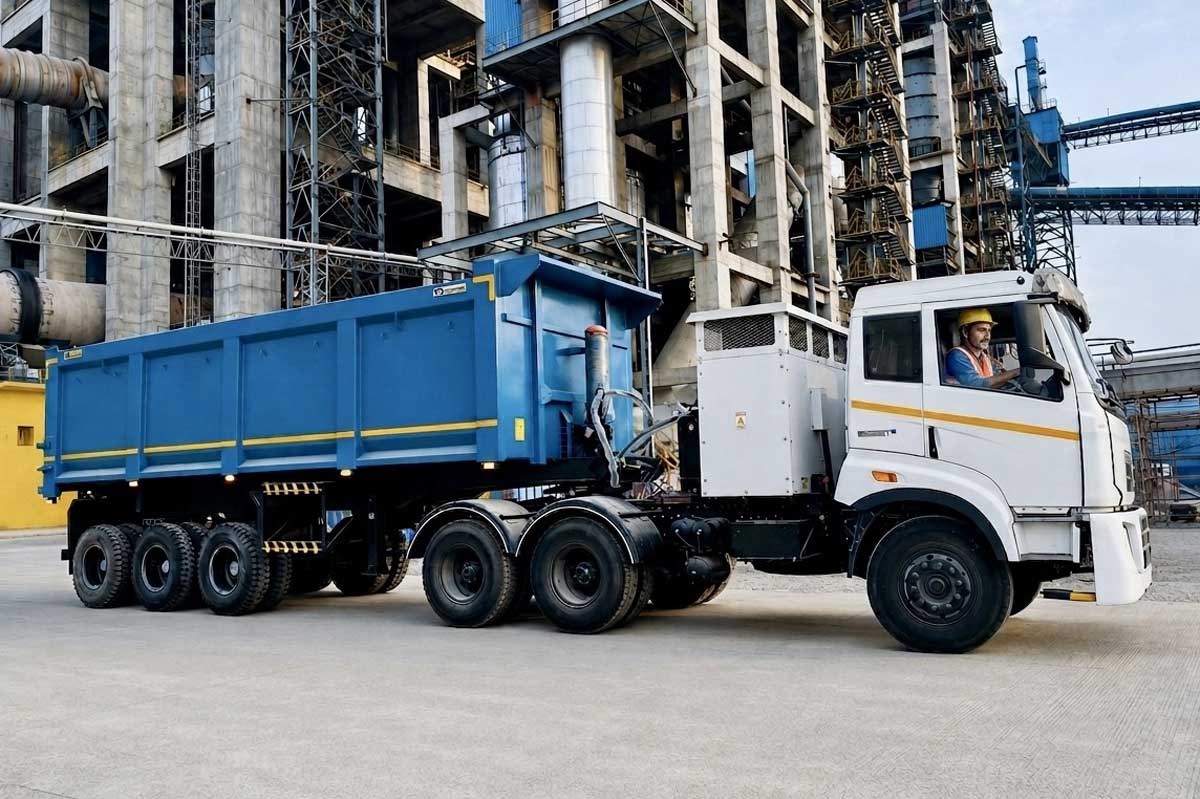
UltraTech Cement expands green logistics with 600+ electric truck fleet
Published
4 weeks agoon
September 3, 2026By
admin
The e-truck fleet will be used to transport five million MT of clinker and other key materials with potential of over 1,17,000 tonnes of net annual CO₂ reduction, displacing the equivalent of 39 million litres of diesel per year.
Mumbai
UltraTech Cement Limited, an Aditya Birla Group company and the world’s largest cement company by sales volume and capacity outside China, has announced that it will scale up its electric vehicle fleet in its logistics operations to 600+ EV trucks by December 2026.
UltraTech has signed service contracts with leading EV prime mover manufacturers including Tata Motors, Ashok Leyland, IPLTech, Energy in Motion and Sany, along with their subsidiaries and other third-party logistics providers, to deploy EV trucks.
The total fleet of 600+ EV trucks will transport about five million MT of clinker and other key materials per annum across Gujarat, Uttar Pradesh, Madhya Pradesh, Rajasthan, Chhattisgarh, Maharashtra and Odisha. Once fully operational, this fleet of over 600 EV trucks will enable a net annual CO₂ reduction of more than 1,17,000 tonnes, displacing the equivalent of 39 million litres of diesel per year.
K C Jhanwar, Managing Director, UltraTech Cement Limited, said, “UltraTech is expanding sustainability beyond its plants by adopting greener logistics solutions. This large-scale transition to green logistics underscores our focus on decarbonising every link of our value chain and supports our commitment to achieving Net Zero.”
UltraTech has been a pioneer in advancing sustainable transport in the cement sector, being the first cement company to deploy heavy-duty electric trucks for long-haul transport of clinker and other materials at scale. The company was among the first in India to introduce green logistics, deploying CNG trucks in 2021 and electric trucks in 2024. UltraTech currently operates 850+ trucks as part of its green logistics operations, including CNG and electric trucks.
UltraTech, with a grey cement capacity of over 200 MTPA in India, operates one of the country’s most complex logistics networks. Its electrification strategy covers the entire supply chain—from mine-to-plant movement to inter-plant transport of clinker and other key materials.
The $ 10 billion UltraTech, the cement flagship company of the Aditya Birla Group, has a total Grey Cement capacity of 205.5 MTPA and White Cement/Putty capacity of 3.2 MTPA. It is a signatory to the GCCA Climate Ambition 2050 and has committed to the Net Zero Concrete roadmap announced by GCCA.
UltraTech Cement achieves 100% green energy milestone at Chhattisgarh plant
Assam Cabinet Approves Rs. 110 bn JK Lakshmi Cement Investment
JSW Cement Receives Rs. 2.3 bn GST Demand Notice
Montra Electric, Wonder Cement Deploy 250-Vehicle EV Fleet
From First Mile to Last Mile
UltraTech Cement achieves 100% green energy milestone at Chhattisgarh plant
Assam Cabinet Approves Rs. 110 bn JK Lakshmi Cement Investment
JSW Cement Receives Rs. 2.3 bn GST Demand Notice
Montra Electric, Wonder Cement Deploy 250-Vehicle EV Fleet
From First Mile to Last Mile
Trending News
-
Concrete4 weeks agoUltraTech to Deploy 600+ Electric Trucks by Dec 2026
-

Concrete4 weeks agoUltraTech Cement expands green logistics with 600+ electric truck fleet
-

Concrete3 weeks agoKirby India Breaks Ground on Fourth PEB Plant in Tamil Nadu
-

Concrete3 weeks agoAditya Birla Group Launches Ultravolt Wires And Cables Business