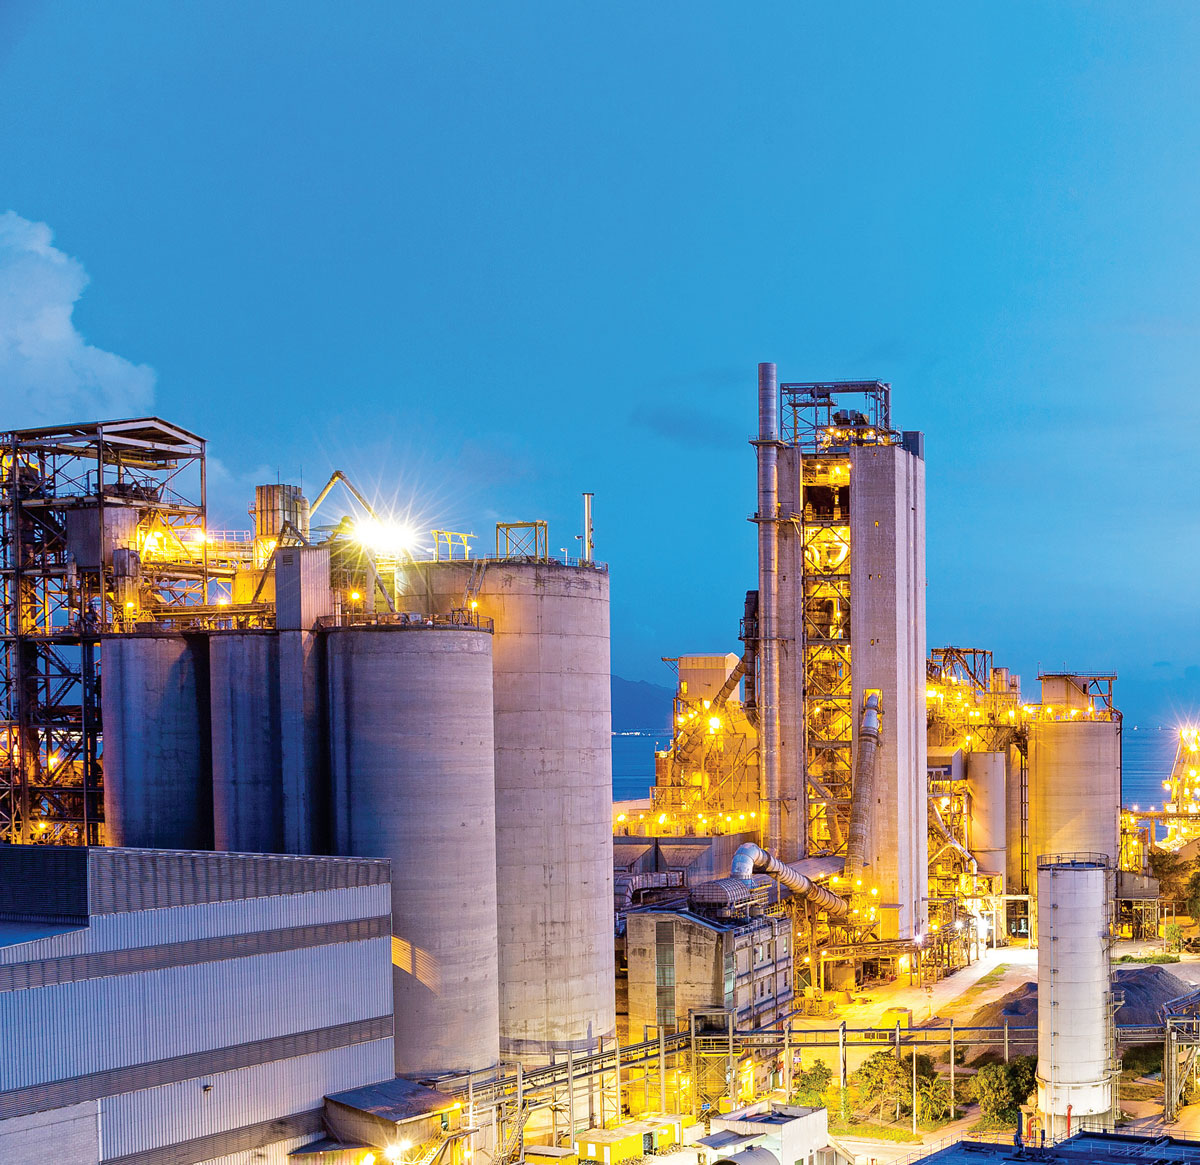
Modernisation of cement plants is reshaping the operational economics, states Professor Procyon Mukherjee as he considers it a strategic pathway to lower costs, improve resilience and enhance long-term competitiveness.
In boardrooms across the cement industry, modernisation is often framed as a compliance-driven exercise, reducing emissions, improving energy efficiency or aligning with sustainability goals. Yet the most successful plants in Europe and India have quietly demonstrated that modernisation is not a cost centre but a strategic lever. When executed with technical depth, especially in kiln systems, alternative fuels and heat recovery, it can fundamentally reset cost structures, improve resilience against fuel volatility, and unlock new sources of competitive advantage.
The difference lies not in whether plants modernise, but in how deeply they transform their core pyro-processing systems.
Why kiln-centric modernisation matters
Cement manufacturing is, at its core, a thermal process. The rotary kiln and calciner together account for energy consumption and emissions. The theoretical thermal requirement for clinker production is around 1700–1800 MJ per tonne, yet real-world plants often operate far above this benchmark due to inefficiencies in combustion, heat recovery and material flow.
Modernisation, therefore, must begin with the kiln system, and not peripheral automation or isolated upgrades. The shift from wet to dry process
kilns, combined with multi-stage preheaters and precalciners, has already delivered step-change improvements, making dry kilns nearly 50 per cent more energy efficient.
However, the next frontier is not merely efficiency; it is fuel transformation.
Engineering the shift to alternative fuels
Thermal Substitution Rate (TSR), the percentage of fossil fuel replaced by alternative fuels. has become the defining metric of modern cement plants. European plants routinely achieve TSR levels of 40 per cent to 50 per cent, with some exceeding 90 per cent, while India still averages below 10 per cent.
The gap is not due to lack of intent but due to the technical complexity of scaling alternative fuels.
At low TSR levels (below 10 per cent), implementation is relatively straightforward, requiring basic fuel preparation and feeding systems. However, once plants target 25 per cent or higher TSR, the modernisation challenge becomes structural. Fuel conditioning systems must handle heterogeneous waste streams, including refuse-derived fuel (RDF), biomass and industrial residues. Milling capacity must be expanded, and feeding systems must be redesigned to ensure consistent calorific input.
The real inflection point occurs beyond 50 per cent TSR. Achieving this level requires deep modifications to the pyro-processing system, including:
• Calciner redesign to handle low-calorific-value fuels
• Multi-channel burners to stabilise flame characteristics
• Chlorine bypass systems to prevent build-up from waste-derived fuels
• Advanced combustion control systems for real-time optimisation
Without these, plants face operational instability, coating formation, flame temperature reduction and incomplete combustion.
European plants have addressed these constraints through integrated engineering, rather than piecemeal upgrades. A mid-sized European plant, for instance, transitioned from 100 per cent coal to a mix of RDF and biomass, achieving a 50 per cent substitution rate with an $8 million investment in fuel
systems. This reduced fuel costs by 25 per cent and lowered CO2 emissions by 15 per cent, even before further optimisation.
The lesson is clear: high TSR is not a fuel decision, it is a kiln redesign problem.
Progress without full transformation
Indian cement companies have made visible progress, but largely within the constraints of
partial modernisation.
Plants operated by companies such as Dalmia Bharat, JSW Cement, and JK Cement have installed pre-processing and co-processing facilities to utilise alternative fuels. These initiatives have delivered TSR levels in the range of 7 per cent to 15 per cent, along with measurable reductions in coal consumption and emissions.
For example, JSW Cement’s Nandyal plant increased its TSR from 4.2 per cent to 7.1 per cent through co-processing of biomass, plastics, and hazardous waste, reducing emissions by approximately 40,000 tonnes and saving significant coal consumption.
Similarly, Ambuja Cement’s Marwar facility has invested in pre-processing infrastructure capable of converting over 200,000 tonnes of waste annually into fuel, raising TSR levels to around 15 per cent.
Yet these gains remain incremental. The structural barriers to higher TSR, fuel availability, regulatory support and kiln readiness, continue to limit progress. Even where plants have technical capability, inconsistent fuel quality and higher alkali or chloride content can disrupt kiln stability, requiring sophisticated control systems and material handling solutions.
India’s industry roadmap targets TSR levels of 25 per cent by 2030, but global experience suggests that this will require a step change in plant design.
Materials, control and thermal efficiency
Beyond fuel substitution, kiln modernisation also involves advances in materials and control systems that directly affect performance.
One of the most overlooked levers is refractory technology. Next-generation refractory materials, such as high-alumina and magnesia-spinel bricks, improve thermal insulation and resistance to chemical attack from alternative fuels. Pilot projects in India have demonstrated energy efficiency gains of 10 per cent to 15 per cent and reductions in downtime due to longer refractory life.
These improvements translate into tangible economic value. Reduced heat loss lowers specific energy consumption, while fewer shutdowns improve capacity utilisation, often by 5 per cent to 7 per cent.
Equally important is the digital layer. Advanced process control systems, including AI-based combustion optimisation, are increasingly being deployed in European plants to stabilise kiln operation under high TSR conditions. These systems integrate real-time sensor data, predictive models, and automated control loops to maintain optimal flame temperature, oxygen levels and clinker quality.
The combination of material science and digital control allows plants to operate closer to theoretical efficiency limits, which is a critical advantage in an industry with thin margins.
Turning losses into power
Another pillar of modernisation is waste heat recovery (WHR). Cement kilns release large volumes of high-temperature exhaust gases, often at 300–400°C. Historically, this energy was lost to the atmosphere.
Modern WHR systems capture this heat to generate electricity, meeting up to 30 per cent of a plant’s power requirements.
In regions with high power costs, such as India, WHR can significantly improve operating margins while reducing exposure to grid volatility. European plants have integrated WHR systems as standard practice, while Indian plants are increasingly adopting them as part of modernisation programmes.
When combined with high TSR, WHR creates a dual benefit: reducing both fuel costs and electricity expenses, while lowering emissions.
The economics of deep modernisation
The capital intensity of modernisation is often cited as a barrier. However, evidence suggests that returns are strongest at higher levels of transformation.
Initial investments, such as basic alternative fuel systems, deliver modest savings. But as plants move toward 25 per cent to 60 per cent TSR, the required investments in kiln modifications, fuel preparation, and control systems increase significantly.
Yet it is precisely at these higher levels that the economic benefits accelerate. Alternative fuels are often significantly cheaper than coal, and in some cases, plants are paid to process waste. Combined with carbon pricing in Europe, this creates a
powerful financial incentive to push TSR as high as technically feasible.
In addition, modernisation reduces exposure to volatile fossil fuel markets, which is helpful in times of geopolitical uncertainty.
A strategic perspective
The most advanced cement companies are moving beyond project-based modernisation toward integrated transformation programs. These programmes align multiple levers, such as kiln design, fuel strategy, digital control and waste integration, into a coherent operating model.
Three strategic principles emerge from leading examples:
- Design for high TSR from the outset. Retrofitting is possible, but optimal performance requires kilns and calciners designed for alternative fuels.
- Invest in fuel ecosystems, not just plant equipment. Reliable supply of waste-derived fuels is as critical as kiln capability.
- Integrate digital and physical systems. High TSR operation requires real-time control and predictive optimisation to maintain stability.
European plants have demonstrated what is possible when these principles are applied systematically. Indian plants are beginning to move in the same direction.
Progress towards digital cement plant
A critical, and often underestimated, dimension of modernisation is the emergence of the digital cement plant, where the traditional boundaries between mechanical systems and decision-making are redefined. In such plants, the kiln, mills and logistics network are no longer operated solely through human judgment but are continuously optimised through advanced process control, machine learning, and real-time data integration.
Leading European producers such as Heidelberg Materials and Holcim have deployed AI-enabled control systems that stabilise kiln operations under high alternative fuel usage, reducing variability in clinker quality while lowering thermal energy consumption by 3 per cent to 5 per cent. These systems use predictive models to adjust parameters such as fuel mix, airflow, and kiln speed in real time, effectively operating the plant closer to its thermodynamic optimum.
In India, companies such as UltraTech Cement have rolled out ‘digital command centres’ that integrate data from multiple plants, enabling centralised monitoring of performance, predictive maintenance, and cross-plant benchmarking. One such initiative has demonstrated reductions in specific heat consumption, improved kiln stability and measurable gains in output without additional capital expenditure. Similarly, Dalmia Bharat has invested in Industry 4.0 programmes that combine IoT sensors with advanced analytics to optimise energy consumption and reduce unplanned downtime. The strategic significance of these initiatives lies not merely in incremental efficiency gains, but in the shift from reactive to predictive operations: plants move from responding to deviations to anticipating them. In an environment where high thermal substitution rates and variable fuel quality introduce operational complexity, digital systems provide the control layer necessary to sustain performance.
About the author:
Professor Procyon Mukherjee, ex-CPO Lafarge-Holcim India, ex-President Hindalco, ex-VP Supply Chain Novelis Europe, has been an industry leader in logistics, procurement, operations and supply chain management. His career spans 38 years starting from Philips, Alcan Inc (Indian Aluminum Company), Hindalco, Novelis and Holcim. He authored the book, ‘The Search for Value in Supply Chains’. He serves now as Visiting Professor in SP Jain Global, SIOM and as the Adjunct Professor at SBUP. He advises leading global firms including consulting firms on SCM and industrial leadership and is a subject matter expert in aluminum and cement. An alumnus of IIM Calcutta and Jadavpur University, he has completed the LH Senior Leadership Programme at IVEY Academy at Western University, Canada.












 Concrete4 weeks ago

 Concrete4 weeks ago

 Concrete4 weeks ago

 Concrete4 weeks ago