Economy & Market
Market Watch (October-2013)
Published
5 years agoon
By
admin
Cement stocks underperform Cement stocks have corrected sharply over the past couple of months, due to growing macro concerns over weakening GDP growth, low infra and realty spends, and unbridled INR depreciation, further dimming the outlook for cement demand. INR depreciation is likely to increase costs (fuel and freight) for cement companies, though their limited US$ debt exposure insulates the balance sheet. While the rupee has corrected upwards against the USD, its sustainability is still in doubt.
Q1FY14 lower EBITDA/tonne
Cost remained flattish to moderately higher in Q1FY14 with marginal push in energy cost and raw material cost coupled with negative operating leverage. Due to the high base of last year, EBITDA for companies dipped in the 18% – 31% range. The current quarter too, is high base and with no improvement in demand and prices so far, earnings are expected to be disappointing in Q2FY14 as well.
Increased clinker consumption
Clinker consumption in the cement manufacturing process typically goes up during periods of high moisture content such as the monsoons. Early monsoons this year have driven clinker consumption higher YoY in Q1FY14, leading to an increase in power and fuel cost per tonne for manufacturers.
Coal India pricing
Effective June 2013, Coal India increased prices of C, D and E-grade coal by ~10%, while lowering prices for Grades A and B by a similar percentage (~12%). A major chunk of domestic coal purchased by the cement industry constitutes C, D and E-grade coal, which is used both for cement manufacture and for captive power generation. Further, higher petcoke prices would have also impacted fuel costs. However, the recent decline in e-auction prices could bring partial relief to major players.
Higher freight cost from rail surcharge
The Indian Railways increased rail freight by 5% effective 1 April, leading to higher landed cost of coal for manufacturers.
Pricing power holds key
Pricing power is essential for the companies to improve profitability. During the first quarter, while ACC saw flat volume growth, UltraTech and Ambuja saw their volumes decline by three per cent each, compared to the year ago quarter. The per- tonne realisations declined five-seven per cent for most companies, with the exception of UltraTech that saw flat realisations.
Diesel price hike
State-owned oil companies demanded a one-time steep increase in diesel prices to make for the widening losses, with the value of rupee dropping by 12 per cent against the US dollar making imports costlier. In the first week of September, diesel prices were increased by 50 paise a litre, excluding local taxes. The increase in diesel prices was the eighth since January. This recent diesel price hike will increase freight costs for ACC, Ambuja, India Cements, UltraTech and Grasim by Rs.70-100/tonne. Since, diesel is mainly used for transportation of cement and raw materials like coal and fly ash, industry experts say it will be adding up to the cost of sales and not the production cost. Taking into account the costs involved in transportation in terms of per- tonne- per- kilometre, on industry´s level it would result in a hike of Rs 1 on a 50 kg bag of cement. Transportation of cement through road accounts for 55 per cent while the rest is shipped largely by rail and to some extent, by sea. Companies will have to pass it on to consumers..
As and when the government bites the bullet and raises diesel prices at one shot, cement companies will have to take more of a burden. Limited visibility on recovery of the investment cycle could continue to dampen the prospects of demand revival. Cement is among the sectors that can see downgrades as the RBI is unlikely to reverse its tightening stance in a hurry and government spending cuts are likely. A good monsoon is expected to bring some respite as cement demand may start improving in October. Volumes are expected to rise in the second half, led by election-led government spending. Now with the INR free-fall resulting in a higher oil subsidy burden, government capital spending may not increase appreciably in H2FY14. Reduced odds of cheaper funding in the system also put in question any sizeable increase in private investments during H2FY14..
While there are no signs of a recovery in demand due to absence of corporate capex and low infra spend, companies will need to further improve efficiencies in order to minimise the impact of weak cement prices. Additionally, with cash flows being impacted in the near term due to challenging macro environment, there will be a slowdown in new project announcement, especially from regional players..
UltraTech Cement, a Birla group company, is our preferred exposure in the large-cap cement space. One, its all-India exposure helps negate fluctuations in offtake and prices in regional markets. Two, the company is growing sales by expanding its market reach. Three, the company controls its costs well, a key advantage in the current scenario of high input costs and drop in realisation for cement players..
ACC – highlights:
ACC is coming up with a Rs.600- crore cement plant in Kharagpur town of West Bengal. It has started the construction for the new unit. The new cement factory will start production after three years and it would produce 15 lakh tonnes of cement daily. It is also planning to invest Rs.3,000 crore to expand its capacity by nearly four million tonnes a year in three eastern region States in the next three years.
ACC plans are afoot for expanding capacities at two existing plants Jamul in Chhattisgarh and Sindri in Jharkhand – the company expects to start construction of a 1.5 million tonne grinding unit at Kharagpur by next January next. The company plans to increase its capacity 10 mt a year from the existing 6 mt a year in three years in the east. This will entail an investment of about Rs.3,000 crore. The projects will be financed through internal accrual.
UltraTech Cement – highlights:
UltraTech Cement announced acquisition of Jaiprakash Associates´ cement assets in Gujarat (4.8 mTPA) for ~Rs 38billion (US$125/t). This is not a big climb-down from a year ago, when media reported likely valuation of Rs 42billion. However, there are definite positives:
1)Removal of a substantial volume-driven competitor,
2)Addition of 4.8 mTPA at ~Rs 8,000/t which can generate ~Rs 550/t of EBITDA straightaway in UTCEM´s hands,.
3)Limestone reserves worth 90 yrs at present capacity and option to scale up substantially in Kutch. Given its own substantial capex commitments (~Rs 78bn in FY14-15), the leverage (0.41x net D/E in FY14E) may border on uncomfortable.
Breakeven requires an EBITDA/t of ~Rs1,200, and the deal will result in EPS dilution for sure.
Concerns
Additional capacities coming on stream and/or fall in growth of demand could lead to decline in cement prices and in turn, lower realisations. There could also be a pressure on margins, which may have to be offset by control in costs. Rise in input costs like coal, slag, fly ash and gypsum could put pressure on margins as could increase in freight costs. Final resolution of the Competition Commission´s order if negative, could impact ACC´s and UTCL´s cash flows and profits. The latest restructuring proposal by Holcim could impact valuation of ACC in the interim.
Conclusions
CY13 could remain a challenging year due to a slowdown in demand, rise in cost pressure and inability to pass on the hike fully to consumers led by weak demand. Demand has continued to remain sluggish at the pan-India level during June-July. UTCL still has been the best performing large cap cement stock with outperformance of 16% in the last one year. As Ultratech is one of the most geographically diversified players in the Indian cement space, it could be the least impacted from ongoing slow-down seen across the industry.
Further, UTCL is valued the lowest in terms of EV/ton among its peers. On the back of weak topline growth trends, inability of the company to pass on any increase in operating expenses would lead to continued pressure on near-term EBITDA margins. The proposed deal of Holcim´s ownership in both ACC and Ambuja may result in UTCL enjoying premium valuations in the sector. However, a sharp revival in profitability is needed for UTCL stock price to perform.
Disclaimer: This document has been prepared by HDFC securities Limited. Publishers of ICR or HDFC securities Limited do not represent that it is accurate or complete and it should not be relied upon as such.
You may like
-
Double Tap to Go Green
-
15th Cement EXPO to be held in March 2025 in Hyderabad
-
14th Cement EXPO
-
Vinita Singhania receives Lifetime Achievement Award at the 7th Indian Cement Review Awards
-
Increasing Use of Supplementary Cementitious Materials
-
Indian Cement Review Touts Decarbonisation Mantra & Awards Growth
Economy & Market
Leonard Unveils Dual-Head Robotic Arm for Hazardous Industrial Demolition
Published
7 days agoon
October 30, 2026By
admin
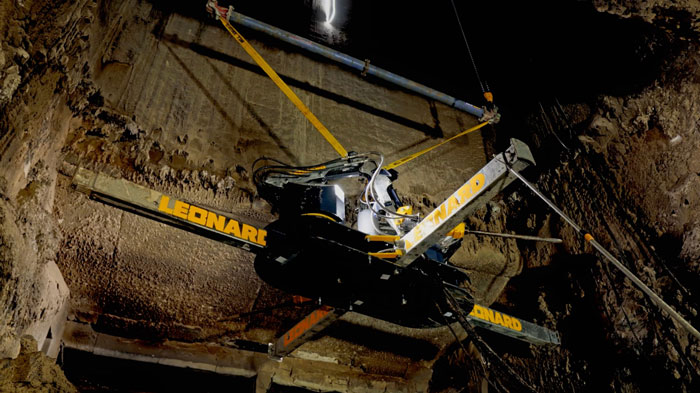
Leonard unveils Descender Duo, a dual-head robotic demolition arm designed to improve industrial safety and reduce shutdown time by up to 50 per cent.
Industrial robotics and refractory services specialist Leonard has launched Descender Duo, a dual-head robotic demolition arm designed to improve safety, accelerate maintenance and reduce shutdown times in hazardous industrial environments. The system made its debut at Lisahally Power Station in Northern Ireland, removing 25 tonnes of slag material within hours.
Developed for the cement, metals, waste-to-energy and petrochemical industries, Descender Duo enables remote-controlled refractory demolition, anchor cutting and welding, and refractory spraying inside boilers, calciners and silos. Its vertical-access design eliminates the need for personnel to enter confined, high-risk spaces during these operations.
Weighing less than two tonnes, the pre-assembled system requires an access opening of just 1.2 m². Supported by an external overhead hoist, it uses electrically operated hydraulic stabilising legs to secure itself inside vessels. The robotic arm offers 360-degree rotation and is suited to vessels approximately 9 m in diameter, with its operating reach extendable through strategically positioned access points.
Equipped with two independently controlled robotic heads, Descender Duo can perform identical or different tasks simultaneously, including refractory demolition, anchor cutting and spraying. Its remote-control system incorporates live camera feeds, allowing operators to monitor operations without entering hazardous environments.
According to Leonard, the technology can deliver time savings of up to 50 per cent compared with manual methods. Its ability to operate at temperatures exceeding 100°C allows maintenance to begin as early as 24 hours after burner shutdown. An all-electric power supply further supports cleaner and more cost-efficient operations.
First Deployment Demonstrates Shutdown Efficiency
The system was first deployed at Burmeister & Wain Scandinavian Contractor’s (BWSC) Lisahally Power Station in Londonderry, Northern Ireland. The facility generates electricity from grade C waste wood, supplying approximately 40,000 homes and businesses.
Leonard and BWSC collaborated to develop a customised solution for the plant’s 26-metre furnace, where extensive external pipework created significant access challenges.
Mark Leonard, Managing Director, Leonard, said, “It required new thinking and rather than step away from the problem we were committed to solving it for the customer, with the customer. We’re relentless in our approach to tackling complex challenges, head-on. We took our years of cement plant experience, coupled with our working knowledge of the BWSC plant, and designed, engineered and tested a completely new vertical solution within just seven weeks from that initial conversation with the customer. That solution was the Descender Duo as we know it today.”
Traditionally, the furnace required a cooling period of up to 36 hours before preparatory work could begin, followed by manual slag removal using rope-access personnel. With Descender Duo, work commenced just 24 hours after shutdown, reducing downtime by up to one day.
The deployment removed 25 tonnes of slag within hours, eliminated the need for at least six workers to enter the hazardous furnace interior and saved 26 hours in the shutdown programme.
“The effectiveness exceeded expectation,” said Martin Doran, Plant Manager at Lisahally Power Station.
“When the Descender Duo concept was first discussed, we had to spend some time with the team from Leonard looking at how it was going to be moved into the furnace. Every site is different and that presented its own challenges, but nothing that the team couldn’t overcome. Once it was installed we were hugely impressed by its efficiency.”
Expanding Industrial Robotics Applications
Descender Duo joins Leonard’s existing portfolio of robotic maintenance solutions, including the Axis horizontal-access arm, Nano confined-space access arm, Charger cement mill media recharging system and Calibre cement mill media grading system.
Headquartered in Northern Ireland, Leonard provides robotic refractory demolition, installation, inspection and industrial maintenance services across the cement, metals, energy, biomass, glass and civil engineering sectors.
Formerly known as G Leonard, the company has more than 35 years of industry experience and operates across Europe, North America, the Middle East, Africa and Asia-Pacific.
The latest innovation reinforces Leonard’s focus on replacing hazardous manual processes with robotic systems that improve workforce safety, enhance operational efficiency and minimise industrial downtime.
Concrete
Martin Engineering Appoints Ashwini Khunte as India General Manager
Published
1 week agoon
October 30, 2026By
admin
Martin Engineering names Ashwini Khunte India General Manager to strengthen operations and drive growth across key bulk material handling sectors.
Pune
Martin Engineering, a global provider of bulk material handling solutions, has appointed Ashwini Khunte as General Manager of its India business, strengthening its leadership as the company expands its presence across the country’s cement, mining, steel, power and infrastructure sectors.
Khunte brings more than a decade of experience with Martin Engineering, having joined its Indian operations in 2013 as a Design Engineer, shortly after the company established its presence in the country in 2012.
A mechanical engineer by qualification, she spent her initial five years developing bulk material handling solutions in collaboration with the company’s operations team. During this period, she gained extensive experience addressing operational challenges in the steel, cement and coal industries. She subsequently moved into project engineering, managing major engineering, procurement and construction (EPC) and original equipment manufacturer (OEM) projects from initial enquiry to commissioning. Her responsibilities later expanded to overseeing Martin Engineering’s conveyor product portfolio in India, involving customer engagement, technical presentations and site visits across heavy industries.
In 2024, Khunte was promoted to Head of Sales & Marketing for the company’s Europe, Middle East, Africa and India (EMEAI) region. The position broadened her international market exposure and strengthened her strategic and commercial leadership capabilities.
Commenting on her appointment, Ashwini Khunte, General Manager, Martin Engineering India, said: “India represents a tremendous opportunity for Martin Engineering. The country’s continued investment in cement, mining, steel, power and infrastructure is creating increasing demand for safer, cleaner and more productive bulk material handling, and that’s exactly what we do. My priority will be to build on the strong foundations already established in India, while continuing to develop our people, strengthen customer relationships and bring practical solutions to the challenges faced by our industry.”
Robert Whetstone, Area Vice President – EMEAI, Martin Engineering, highlighted Khunte’s technical expertise, market understanding and leadership experience.
“Ashwini brings an exceptional combination of technical understanding, customer knowledge and commercial leadership. She has grown as Martin Engineering has grown, and has consistently demonstrated outstanding capability to transform her expertise into practical solutions. Her knowledge of the Indian market, together with her international experience, makes her ideally suited to lead our India business through its next stage of growth for years to come.”
Since establishing its Indian business in 2012, Martin Engineering has expanded its local workforce, manufacturing capabilities and dealership network. The company supplies conveyor products, transfer point solutions, material flow aids, training and technical support to bulk material handling industries. Khunte’s appointment positions the company to further strengthen customer relationships and expand its solutions portfolio in India’s growing industrial and infrastructure markets.
Concrete
Fornnax Wins AIRIA’s Special Export Award for Rubber Machinery in 2025-26
Published
3 weeks agoon
October 19, 2026By
admin
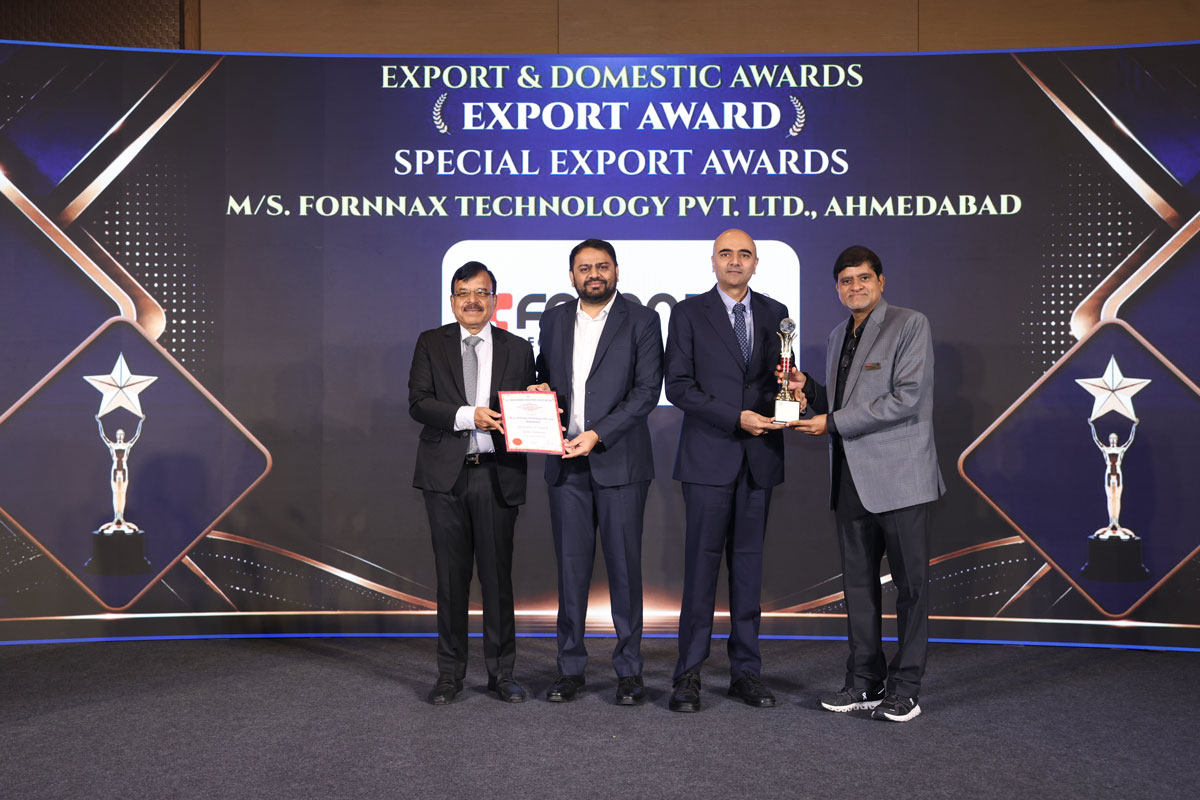
Fornnax Technology Pvt. Ltd. has been honoured with the Special Export Award – Rubber Machinery for 2025–26 by the All-India Rubber Industries Association (AIRIA), in recognition of its highest exports of tyre recycling plants to the European region.
With more than a decade of experience in India’s tyre recycling industry, Fornnax has contributed to the development of advanced recycling technologies and infrastructure. The company currently holds a 90% market share in India’s domestic tyre recycling sector, while exports account for 30% of its business, spanning markets such as Europe, Australia and the GCC.
The award marks another milestone for Fornnax, whose tyre recycling lines and advanced shredding technologies are supporting the growth of the circular economy in India and international markets.
Commenting on the recognition, Mr. Jignesh Kundaria, Founder and Director of Fornnax, said:
“This honour from AIRIA is a reflection of an incredible journey we have undertaken over the years. When we started Fornnax, there was no established recycling industry in India to follow. We chose to build for the future instead. Today, when you see India’s tyre recycling sector, it has already transformed into a dynamic, high-growth industry and we are extremely proud to have played our part in building it.”
Unlike standalone equipment suppliers, Fornnax focuses on developing complete, high-capacity recycling infrastructure. Its integrated systems combine multiple stages of shredding and size reduction to enable efficient, continuous operations. This system-level engineering approach helps recycling operators improve throughput, equipment reliability and operational consistency.
The recognition reinforces Fornnax’s commitment to developing engineering technologies that contribute to a more efficient and circular recycling ecosystem.
Looking ahead, the company aims to expand its international presence while continuing to develop advanced shredding and recycling solutions to address the growing volumes and evolving requirements of the global recycling industry.
For more information, visit: www.fornnax.com
Dhanekula Institute Signs MoU with Adani Cement
JK Lakshmi Cement Begins Rs. 110 bn Assam Plant Project
Kshatriya Engineering College Signs MoU with Adani Cement
Ambuja Cements to Invest Rs. 145 bn to Raise Capacity by FY30
India’s Cement Sector Cuts Energy Use, but Worker Safety Worsens
Dhanekula Institute Signs MoU with Adani Cement
JK Lakshmi Cement Begins Rs. 110 bn Assam Plant Project
Kshatriya Engineering College Signs MoU with Adani Cement
Ambuja Cements to Invest Rs. 145 bn to Raise Capacity by FY30
India’s Cement Sector Cuts Energy Use, but Worker Safety Worsens
Trending News
-
Concrete4 weeks agoShiva Cement Merges with JSW Cement
-
Concrete4 weeks agoJSW Cement Boards Approve Proposed Shiva Cement Merger
-
Concrete4 weeks agoUltraTech becomes first Indian cement firm to cross 2 GW green energy
-
Concrete4 weeks agoJSW Cement commissions additional 1 MTPA grinding unit at Nagaur