Connect with us

Economy & Market

Consolidation in cement industry: Gobbling Up!

Published

on

Shares

The cement industry has been going through consolidation phase with large Indian cement players preying on smaller ones and foreign cement majors acquiring controlling stake in Indian majors. Prakash Patil looks at the M&A scenario and what it holds for the future of cement industry in India.It’s mergers and acquisitions season in the Indian cement industry and the latest big ticket deal is the acquisition of 51 per cent controlling stake by Irish cement major CRH in the two 2.4 MTPA plants of the Jaypee Group in Gujarat. A buoyant trend in prices could reportedly fetch the Jaypee Group at least $160 per tonne as replacement value, as it puts on the block its hived-off plants in western (2 units of 2.4 MT each) and southern India (1 unit of 5 MTPA). The deal for the two 2.4 MTPA plants is reportedly valued at Rs 4,200 crore. However, as Jaypee Group has its third plant with a capacity of 5 MTPA in Andhra Pradesh and the three plants would be valued at about Rs 9,000 crore. For CRH, this will be the second acquisition in India. The company had forayed into India in 2008 with the acquisition of 50 per cent stake in Hyderabad-based cement producer My Home Industries, which had an installed capacity of 4.2 MTPA.The latest CRH-Jaypee Group deal is an indication of the churning the Indian cement industry is going through over the last decade or so. The big fishes are on the prowl to gobble up smaller fries in the business and considering that there are 139 large cement plants and 365 mini cement plants in the country currently with 40 major and mid-size players having pan-India presence, the opportunities for acquisitions for the large cement players are enticing. And, it’s not just the small fries that are on the radar of the big players, even some of the biggest cement companies have been taken over in the past and many more are being wooed. After all, the cement business of Jaypee Group being acquired by CRH makes Jaypee Group the third largest cement player in India after UltraTech and Ambuja Cements.The big ticket dealsApart from the latest big ticket deal between the CRH-Jaypee Group, there have been quite a few large takeovers since 1999. When Gujarat Ambuja Cements (GACL) picked up 7.2 per cent stake in India’s then largest cement manufacturer ACC at a price of Rs 370 per share when the market price hovered around Rs 240 per share from the Tatas in December 1999, it created sensation. Later in 2000, GACL acquired the balance 7.2 per cent from the Tatas to become the largest shareholder in ACC. But the twist to this tale came when Swiss cement major Holcim picked up 14.8 per cent stake in Gujarat Ambuja Cements (later to merge with Ambuja Cements Eastern to become Ambuja Cements) for Rs 2,100 crore through the creeping acquisition route and later picked up another 20 per cent stake for Rs 2,400 crore. Subsequently, Holcim hiked its stake in Ambuja Cements to over 50 per cent, thereby acquiring complete management control over Ambuja Cements. The Holcim transaction and valuation provides an excellent indication of the extent to which investors and strategic players are ready to buy the India growth story. In 2005, Holcim acquired stake in ACC at an enterprise value (EV) of $111 per tonne and the next year Holcim acquired stake in Ambuja Cement at an EV of $193 per tonne. In 2007, Holcim again increased its stake in Ambuja Cements at an EV of $301 per tonne!With this acquisition, Holcim also acquired management control over ACC as Ambuja Cements had hiked its stake in ACC to more than 50 per cent. So, Holcim upped the ante for other global cement companies by acquiring majority stake and management control over two of India’s largest cement companies.Lafarge, the French cement major, got late into action in the M&A space and decided to take the acquisition route to fast track it cement business in India. The company declared in 2010 that it was open to consolidation in India and, according to Bruno Lafont, Chairman & CEO, Lafarge, the timeframe for acquisitions was the next five years. "We see consolidation happening (in the cement industry) in India in the mid term period. We are confident of our ability to deliver our investments in India and are open to seizing new opportunities, be it consolidation or greenfield projects," said Lafont while inaugurating the clinker line at Lafarge India’s cement plant in January 2010 at Sonadih in Chhattisgarh. The company entered the Indian market in 1999 with the acquisition of Tata Steel’s cement plant. This was followed by the purchase of the Raymond Cement facility in 2001 and the acquisition of L&T’s concrete business in 2008.The takeover of L&T’s cement business by Grasim Industries in June 2003 also created buzz in the market since this takeover catapulted Grasim Industries (later its cement division being merged into UltraTech Cement) from the third position to the numero uno position in India. After the takeover, UltraTech’s installed capacity went up from 13 MTPA to 31 MTPA. Grasim Industries had to shell out Rs 2,200 crore over a period of three years for a majority stake in Ultratech Cement. Today, UltraTech maintains its leadership position with an installed capacity of 52 MTPA, with Holcim at the no. 2 position with combined capacity of 45 MTPA through ACC and Ambuja Cement.These are just a few samples of big ticket deals that have happened in the cement sector in India since late nineties. There have been many more big and small takeovers and mergers by domestic players since mid-1990s and by foreign players since late-1990s (see box). According to the data published by the Department of Industrial Policy and Promotion, the cement sector attracted foreign direct investments (FDI) worth US$ 2.62 bn between April 2000 to May 2012, which is an ample indication of the fact that the cement sector has been attracting foreign investors in droves.The key M&A triggersClearly, the cement biggies have gone on a shopping spree since during the last decade or so. And not without reason. There are compelling reasons why domestic and foreign cement majors appear to be so bullish on India. "Major reasons for consolidation were excess capacity and entry of foreign players who wanted a pie of untapped Indian market…Apart from above two reasons, another factor that is leading to consolidation is the rising cost of greenfield capacity which also tends to have longer gestation period. Existing players are eyeing companies who are unable to meet rising cost of raw materials due to increasing imported coal prices. On the other hand, the top players who want to spread their reach are tapping such companies as it saves on time factor of greenfield capacities," says Alok Sanghi, Director, Sanghi Industries.
Commenting on the reasons for consolidation, Jailesh Dalal, Director, JAYCEE Buildcon (India), says "The Indian cement industry is fragmented and large domestic and international players would try to consolidate their position going forward for geographical diversification, concentrated focus on operational efficiency, challenges in acquiring land/limestone resources, exit of smaller players and divesture of cement businesses by diversified groups."Now, let’s look at each of these reasons why Indian cement industry is passing through the consolidation phase.Overcapacity

During 2007-12, cement producers added capacity to the tune of 150 MTPA, thereby almost doubling the total installed capacity to 303 MTPA in FY2012-13. According to a report by research firm RNCOS, "It is anticipated that the cement industry players will continue to increase their annual cement output in coming years and the country’s cement production will grow at a compound annual growth rate (CAGR) of around 12 per cent during 2011-12 to 2013-14." According to projections, by 2017 the total capacity nationally would add up to 470 MTPA.The increase in capacities by many of the Indian companies was in anticipation of demand from the infrastructure sector which failed to materialise. In a situation where demand fails to keep pace with supply, the capacity utilization rate is bound to decelerate. The capacity utilisation rate for the cement industry in India has dropped from 93 per cent in FY2006-07 to 75 per cent in FY2011-12. The fall-out of such overcapacity situation is that the cement prices are likely to come under downward pressure which would make survival difficult for smaller cement companies with capacities less than 1 MTPA and therefore vulnerable for takeover. However, the fact that cement majors have built up capacities in advance is an indication that these companies expect demand for cement to remain firm due to construction activity, which is expected to gather momentum due to government’s policy to boost investments in infrastructure.Infrastructure PotentialIndia’s high housing and infrastructure deficits points to the huge potential for development of housing and infrastructure. The cement sector will benefit hugely as and when the momentum in housing and infra development picks up. This potential for development has been attracting major players in hordes from across the world. The demand for cement, being a derived demand, primarily depends on the industrial construction, real estate business, construction activities and investments in the infrastructure sector.Currently, the housing sector consumes 55-60 per cent of cement produced in India and this is expected to change in the next few years when the emphasis will shift on infrastructure development such as roads, bridges, airports, and railways, which will consume a significant percentage of cement produced in the country. The consumption of cement in agriculture is negligible today; but with a greater thrust on agriculture and the suggested ‘second green revolution’, this sector too will extensively use cement to build warehouses and other logistics.But instead of opting to set up cement plants themselves, it makes sense for the foreign players to take the acquisition route not just to make foray into India but also ramp up capacity quickly. The high potential for growth in demand for cement is amply evident from the fact that the per capita cement consumption in India was 230 kg in 2010, which is almost half of the global average of around 450 kg and way below the Chinese average per capita consumption of 1220 kg. Hence, domestic and foreign cement companies remain bullish on the prospects of cement industry in India.High capital cost & long gestation periodA cement plant is typically a capital intensive business and to establish a greenfield project takes about three years. The cost of setting up a greenfield capacity has reportedly shot up from $120 per tonne to $160 per tonne in just two years. Besides, the cement business has a long gestation period and, depending on the market situation, the break-even point may extend to three-four years at an operating level of 70-75 per cent. The high capital cost and long gestation period makes establishing a new cement plant an unattractive business proposition. Hence, established and large players may prefer to poach on the existing and established players to beat the competition and increase their market share. "The cement sector is slowly heading for a major consolidation as greenfield projects are becoming difficult to set up due to increased hassles in areas like mineral concession, land acquisition and related environmental and operational issues. This may lead the cement industry in India to be consolidated in the hands of a few major giant cement companies and only a few cement companies with single or smaller capacity plants shall continue to operate purely due to regional and local factors," says P K Ghosh, Chairman, Ercom Engineers.Entry barriers & cumbersome proceduresDifficulty in accessing limestone reserves, which is a key input in cement production, acts as a significant entry barrier for new entrants. To overcome this difficulty, takeover of companies with access to limestone reserves is the easiest route to crossing the entry barrier. No wonder, none of the foreign cement majors tried to set up a greenfield cement plant as prospecting for limestone reserves is a time-consuming process. Even if the limestone reserves are established, getting the mining rights, railway siding, etc. can reportedly take upto 7-8 years, with only 25 per cent chance of striking enough limestone reserves to last for the entire economic life-span of the plant. Hence, acquisition is bound to pick up further momentum as more cement majors enter the Indian market.The benefits of consolidationThe consolidation in the cement industry would prove to be beneficial both for the acquiring companies as well as for the cement industry. Some of the benefits that would ensue from consolidation are as follows:
Economies of scale
A large cement company enjoys the benefits of economies of scale. Mergers and acquisitions bring about consolidation of capacities which adds up the benefits of scale. The economies of scale enable the company to reduce the production costs so that it can reduce the cement price to maintain an edge over the competitors.Extended reach and increased revenuesWhen a company takes over the production and distribution facilities of another company, it immediately extends its geographical reach and increases its market share on account of expansion of the market for its product. The market expansion helps in ramping up the revenues of the company within a short span of time. The enhanced geographical reach may also result in substantial reduction in transportation costs which are quite high as cement is a bulk commodity.Technological upgradationThe new energy-efficient but capital-intensive "dry" production technology offers to the companies efficiencies that provide vital edge over the companies not deploying such technologies. Small manufacturers may not possess the requisite financial resources or production volumes to be able to afford the most efficient technology, which puts them at a competitive cost disadvantage. The entry of foreign players has led to technological upgradation and innovation in Indian cement industry. "Despite the fact that the technology used by Indian cement companies is among the best in the world, more innovation is required to ensure that cement plans are not only environment-friendly, but also low-cost in nature. M&As in last decade has helped Indian firms propel to global standards. Foreign firms who took over Indian firms have made most of the investments in India in the last decade for upgrading technology and raising capacity. With higher spend on technology, existing players are likely to focus more on ready mix concrete, bulk sales and blended cement to ensure improvement in quality as well as environment consciousness with sustainable construction," says Sanghi.The Road AheadGoing forward, the acquisitions space is going to get hotter, with lot of small and mid-sized cement companies up for grabs. Once the economies of scale kick in on account of consolidation, the cement prices are likely to remain competitive yet remunerative. This would benefit both the cement companies as well as cement consumers. Summarising the benefits of consolidation, Dalal says, "M&As would largely have a positive impact in the cement industry in India on account of value creation, economies of scale and cost efficiencies, operational and supply chain efficiencies, higher competitiveness, technology transfer, better research and development and high quality products, financial leveraging and optimization of profitability and increased focus on health, safety and environment. In the future as well, M&As would augur well for the industry as it would bring world-class technology, products and operational efficiencies into India." Sanghi too feels that M&As would be beneficial and says, "M&As in cement industry is likely to bring pricing power, improve profitability and reduce cost of branding for top players. Through M&As, top players would have higher vertical integration and locational advantage with respect to sourcing raw materials and market reach."Of course, there is always the possibility of major companies forming a cartel to keep the cement prices artificially high, but with the Competition Commission of India keeping a vigil over the production figures, capacity utilization and cement prices, the cement companies would be wary of indulging in such malpractices. Sanghi too dismisses fear of cartelization saying, "If there was (cartelisation) as is claimed, cement companies would not have reported losses in any quarter. Also, prices would have been same across the year, if there was cartelization. But every year, cement prices fall during monsoon because there is a slowdown in demand; while prices rise on and around Diwali due to surge in demand from real estate."To sum up, consolidation is good for the cement industry and there are sunny days ahead for the industry in times to come.

Economy & Market

Leonard Unveils Dual-Head Robotic Arm for Hazardous Industrial Demolition

Published

on

By

Shares

 Leonard unveils Descender Duo, a dual-head robotic demolition arm designed to improve industrial safety and reduce shutdown time by up to 50 per cent.

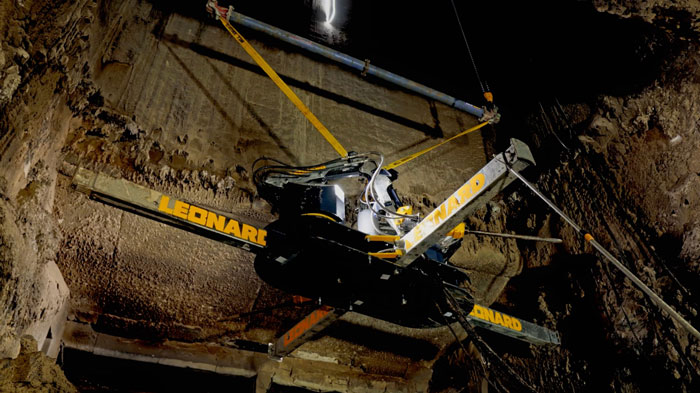
Industrial robotics and refractory services specialist Leonard has launched Descender Duo, a dual-head robotic demolition arm designed to improve safety, accelerate maintenance and reduce shutdown times in hazardous industrial environments. The system made its debut at Lisahally Power Station in Northern Ireland, removing 25 tonnes of slag material within hours.

Developed for the cement, metals, waste-to-energy and petrochemical industries, Descender Duo enables remote-controlled refractory demolition, anchor cutting and welding, and refractory spraying inside boilers, calciners and silos. Its vertical-access design eliminates the need for personnel to enter confined, high-risk spaces during these operations.

Weighing less than two tonnes, the pre-assembled system requires an access opening of just 1.2 m². Supported by an external overhead hoist, it uses electrically operated hydraulic stabilising legs to secure itself inside vessels. The robotic arm offers 360-degree rotation and is suited to vessels approximately 9 m in diameter, with its operating reach extendable through strategically positioned access points.

Equipped with two independently controlled robotic heads, Descender Duo can perform identical or different tasks simultaneously, including refractory demolition, anchor cutting and spraying. Its remote-control system incorporates live camera feeds, allowing operators to monitor operations without entering hazardous environments.

According to Leonard, the technology can deliver time savings of up to 50 per cent compared with manual methods. Its ability to operate at temperatures exceeding 100°C allows maintenance to begin as early as 24 hours after burner shutdown. An all-electric power supply further supports cleaner and more cost-efficient operations.

First Deployment Demonstrates Shutdown Efficiency

The system was first deployed at Burmeister & Wain Scandinavian Contractor’s (BWSC) Lisahally Power Station in Londonderry, Northern Ireland. The facility generates electricity from grade C waste wood, supplying approximately 40,000 homes and businesses.

Leonard and BWSC collaborated to develop a customised solution for the plant’s 26-metre furnace, where extensive external pipework created significant access challenges.

Mark Leonard, Managing Director, Leonard, said, “It required new thinking and rather than step away from the problem we were committed to solving it for the customer, with the customer. We’re relentless in our approach to tackling complex challenges, head-on. We took our years of cement plant experience, coupled with our working knowledge of the BWSC plant, and designed, engineered and tested a completely new vertical solution within just seven weeks from that initial conversation with the customer. That solution was the Descender Duo as we know it today.”

Traditionally, the furnace required a cooling period of up to 36 hours before preparatory work could begin, followed by manual slag removal using rope-access personnel. With Descender Duo, work commenced just 24 hours after shutdown, reducing downtime by up to one day.

The deployment removed 25 tonnes of slag within hours, eliminated the need for at least six workers to enter the hazardous furnace interior and saved 26 hours in the shutdown programme.

“The effectiveness exceeded expectation,” said Martin Doran, Plant Manager at Lisahally Power Station.

“When the Descender Duo concept was first discussed, we had to spend some time with the team from Leonard looking at how it was going to be moved into the furnace. Every site is different and that presented its own challenges, but nothing that the team couldn’t overcome. Once it was installed we were hugely impressed by its efficiency.”

Expanding Industrial Robotics Applications

Descender Duo joins Leonard’s existing portfolio of robotic maintenance solutions, including the Axis horizontal-access arm, Nano confined-space access arm, Charger cement mill media recharging system and Calibre cement mill media grading system.

Headquartered in Northern Ireland, Leonard provides robotic refractory demolition, installation, inspection and industrial maintenance services across the cement, metals, energy, biomass, glass and civil engineering sectors.

Formerly known as G Leonard, the company has more than 35 years of industry experience and operates across Europe, North America, the Middle East, Africa and Asia-Pacific.

The latest innovation reinforces Leonard’s focus on replacing hazardous manual processes with robotic systems that improve workforce safety, enhance operational efficiency and minimise industrial downtime.


Continue Reading

Concrete

Martin Engineering Appoints Ashwini Khunte as India General Manager

Published

on

By

Shares

Martin Engineering names Ashwini Khunte India General Manager to strengthen operations and drive growth across key bulk material handling sectors.

Pune

Martin Engineering, a global provider of bulk material handling solutions, has appointed Ashwini Khunte as General Manager of its India business, strengthening its leadership as the company expands its presence across the country’s cement, mining, steel, power and infrastructure sectors.

Khunte brings more than a decade of experience with Martin Engineering, having joined its Indian operations in 2013 as a Design Engineer, shortly after the company established its presence in the country in 2012.

A mechanical engineer by qualification, she spent her initial five years developing bulk material handling solutions in collaboration with the company’s operations team. During this period, she gained extensive experience addressing operational challenges in the steel, cement and coal industries. She subsequently moved into project engineering, managing major engineering, procurement and construction (EPC) and original equipment manufacturer (OEM) projects from initial enquiry to commissioning. Her responsibilities later expanded to overseeing Martin Engineering’s conveyor product portfolio in India, involving customer engagement, technical presentations and site visits across heavy industries.

In 2024, Khunte was promoted to Head of Sales & Marketing for the company’s Europe, Middle East, Africa and India (EMEAI) region. The position broadened her international market exposure and strengthened her strategic and commercial leadership capabilities.

Commenting on her appointment, Ashwini Khunte, General Manager, Martin Engineering India, said: “India represents a tremendous opportunity for Martin Engineering. The country’s continued investment in cement, mining, steel, power and infrastructure is creating increasing demand for safer, cleaner and more productive bulk material handling, and that’s exactly what we do. My priority will be to build on the strong foundations already established in India, while continuing to develop our people, strengthen customer relationships and bring practical solutions to the challenges faced by our industry.”

Robert Whetstone, Area Vice President – EMEAI, Martin Engineering, highlighted Khunte’s technical expertise, market understanding and leadership experience.

“Ashwini brings an exceptional combination of technical understanding, customer knowledge and commercial leadership. She has grown as Martin Engineering has grown, and has consistently demonstrated outstanding capability to transform her expertise into practical solutions. Her knowledge of the Indian market, together with her international experience, makes her ideally suited to lead our India business through its next stage of growth for years to come.”

Since establishing its Indian business in 2012, Martin Engineering has expanded its local workforce, manufacturing capabilities and dealership network. The company supplies conveyor products, transfer point solutions, material flow aids, training and technical support to bulk material handling industries. Khunte’s appointment positions the company to further strengthen customer relationships and expand its solutions portfolio in India’s growing industrial and infrastructure markets.

Continue Reading

Concrete

Fornnax Wins AIRIA’s Special Export Award for Rubber Machinery in 2025-26

Published

on

By

Shares

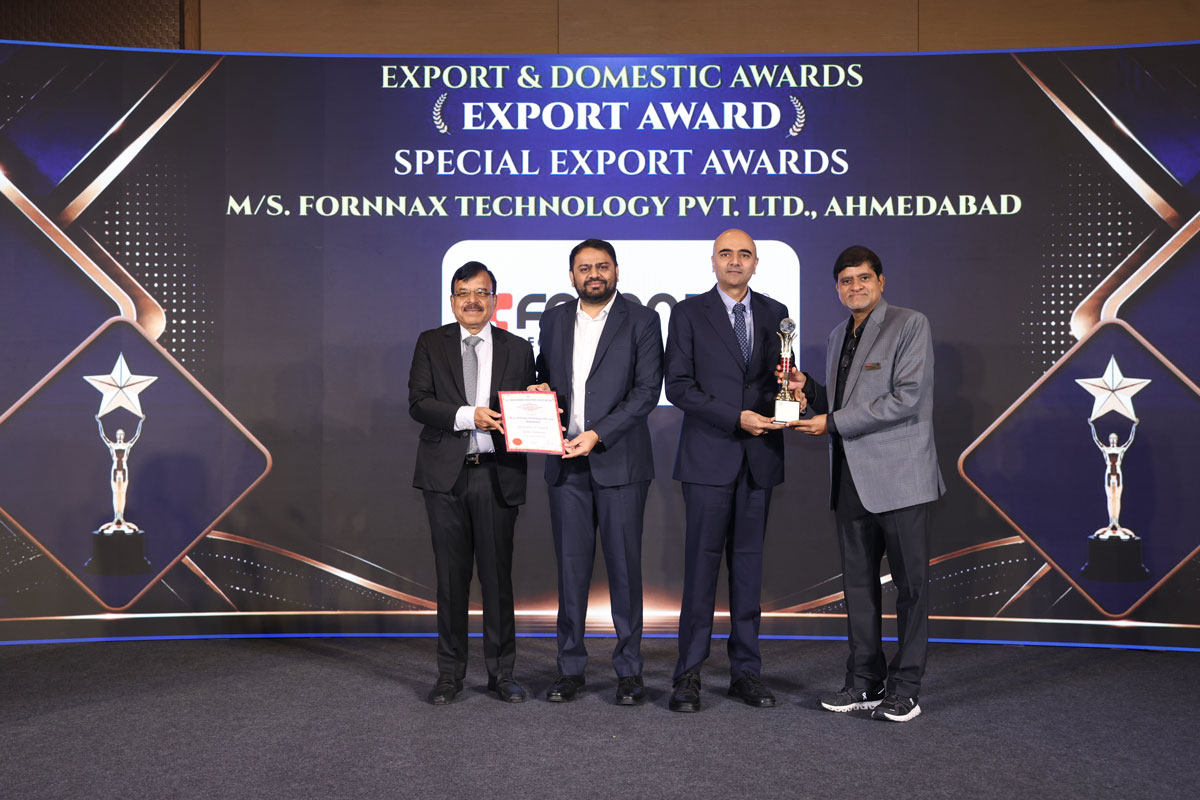
Fornnax Technology Pvt. Ltd. has been honoured with the Special Export Award – Rubber Machinery for 2025–26 by the All-India Rubber Industries Association (AIRIA), in recognition of its highest exports of tyre recycling plants to the European region.

With more than a decade of experience in India’s tyre recycling industry, Fornnax has contributed to the development of advanced recycling technologies and infrastructure. The company currently holds a 90% market share in India’s domestic tyre recycling sector, while exports account for 30% of its business, spanning markets such as Europe, Australia and the GCC.

The award marks another milestone for Fornnax, whose tyre recycling lines and advanced shredding technologies are supporting the growth of the circular economy in India and international markets.

Commenting on the recognition, Mr. Jignesh Kundaria, Founder and Director of Fornnax, said:

“This honour from AIRIA is a reflection of an incredible journey we have undertaken over the years. When we started Fornnax, there was no established recycling industry in India to follow. We chose to build for the future instead. Today, when you see India’s tyre recycling sector, it has already transformed into a dynamic, high-growth industry and we are extremely proud to have played our part in building it.”

Unlike standalone equipment suppliers, Fornnax focuses on developing complete, high-capacity recycling infrastructure. Its integrated systems combine multiple stages of shredding and size reduction to enable efficient, continuous operations. This system-level engineering approach helps recycling operators improve throughput, equipment reliability and operational consistency.

The recognition reinforces Fornnax’s commitment to developing engineering technologies that contribute to a more efficient and circular recycling ecosystem.

Looking ahead, the company aims to expand its international presence while continuing to develop advanced shredding and recycling solutions to address the growing volumes and evolving requirements of the global recycling industry.

For more information, visit: www.fornnax.com

Continue Reading

Video Thumbnail
▶

    SIGN-UP FOR OUR GENERAL NEWSLETTER

    Trending News

    SUBSCRIBE TO THE NEWSLETTER


    Don't miss out on valuable insights and opportunities to connect with like minded professionals.


      This will close in 0 seconds