Indian Cement Review (ICR) and Fuller Technologies brought industry, policy and technology leaders together to discuss how cement innovation can drive green construction at scale, writes Rakesh Rao.
India is building at a pace few countries can match. Highways, airports, housing, logistics parks, industrial corridors and urban infrastructure are reshaping the country’s economic geography. But beneath this growth story lies a difficult question: can India continue to build at scale without locking itself into a high-carbon future?
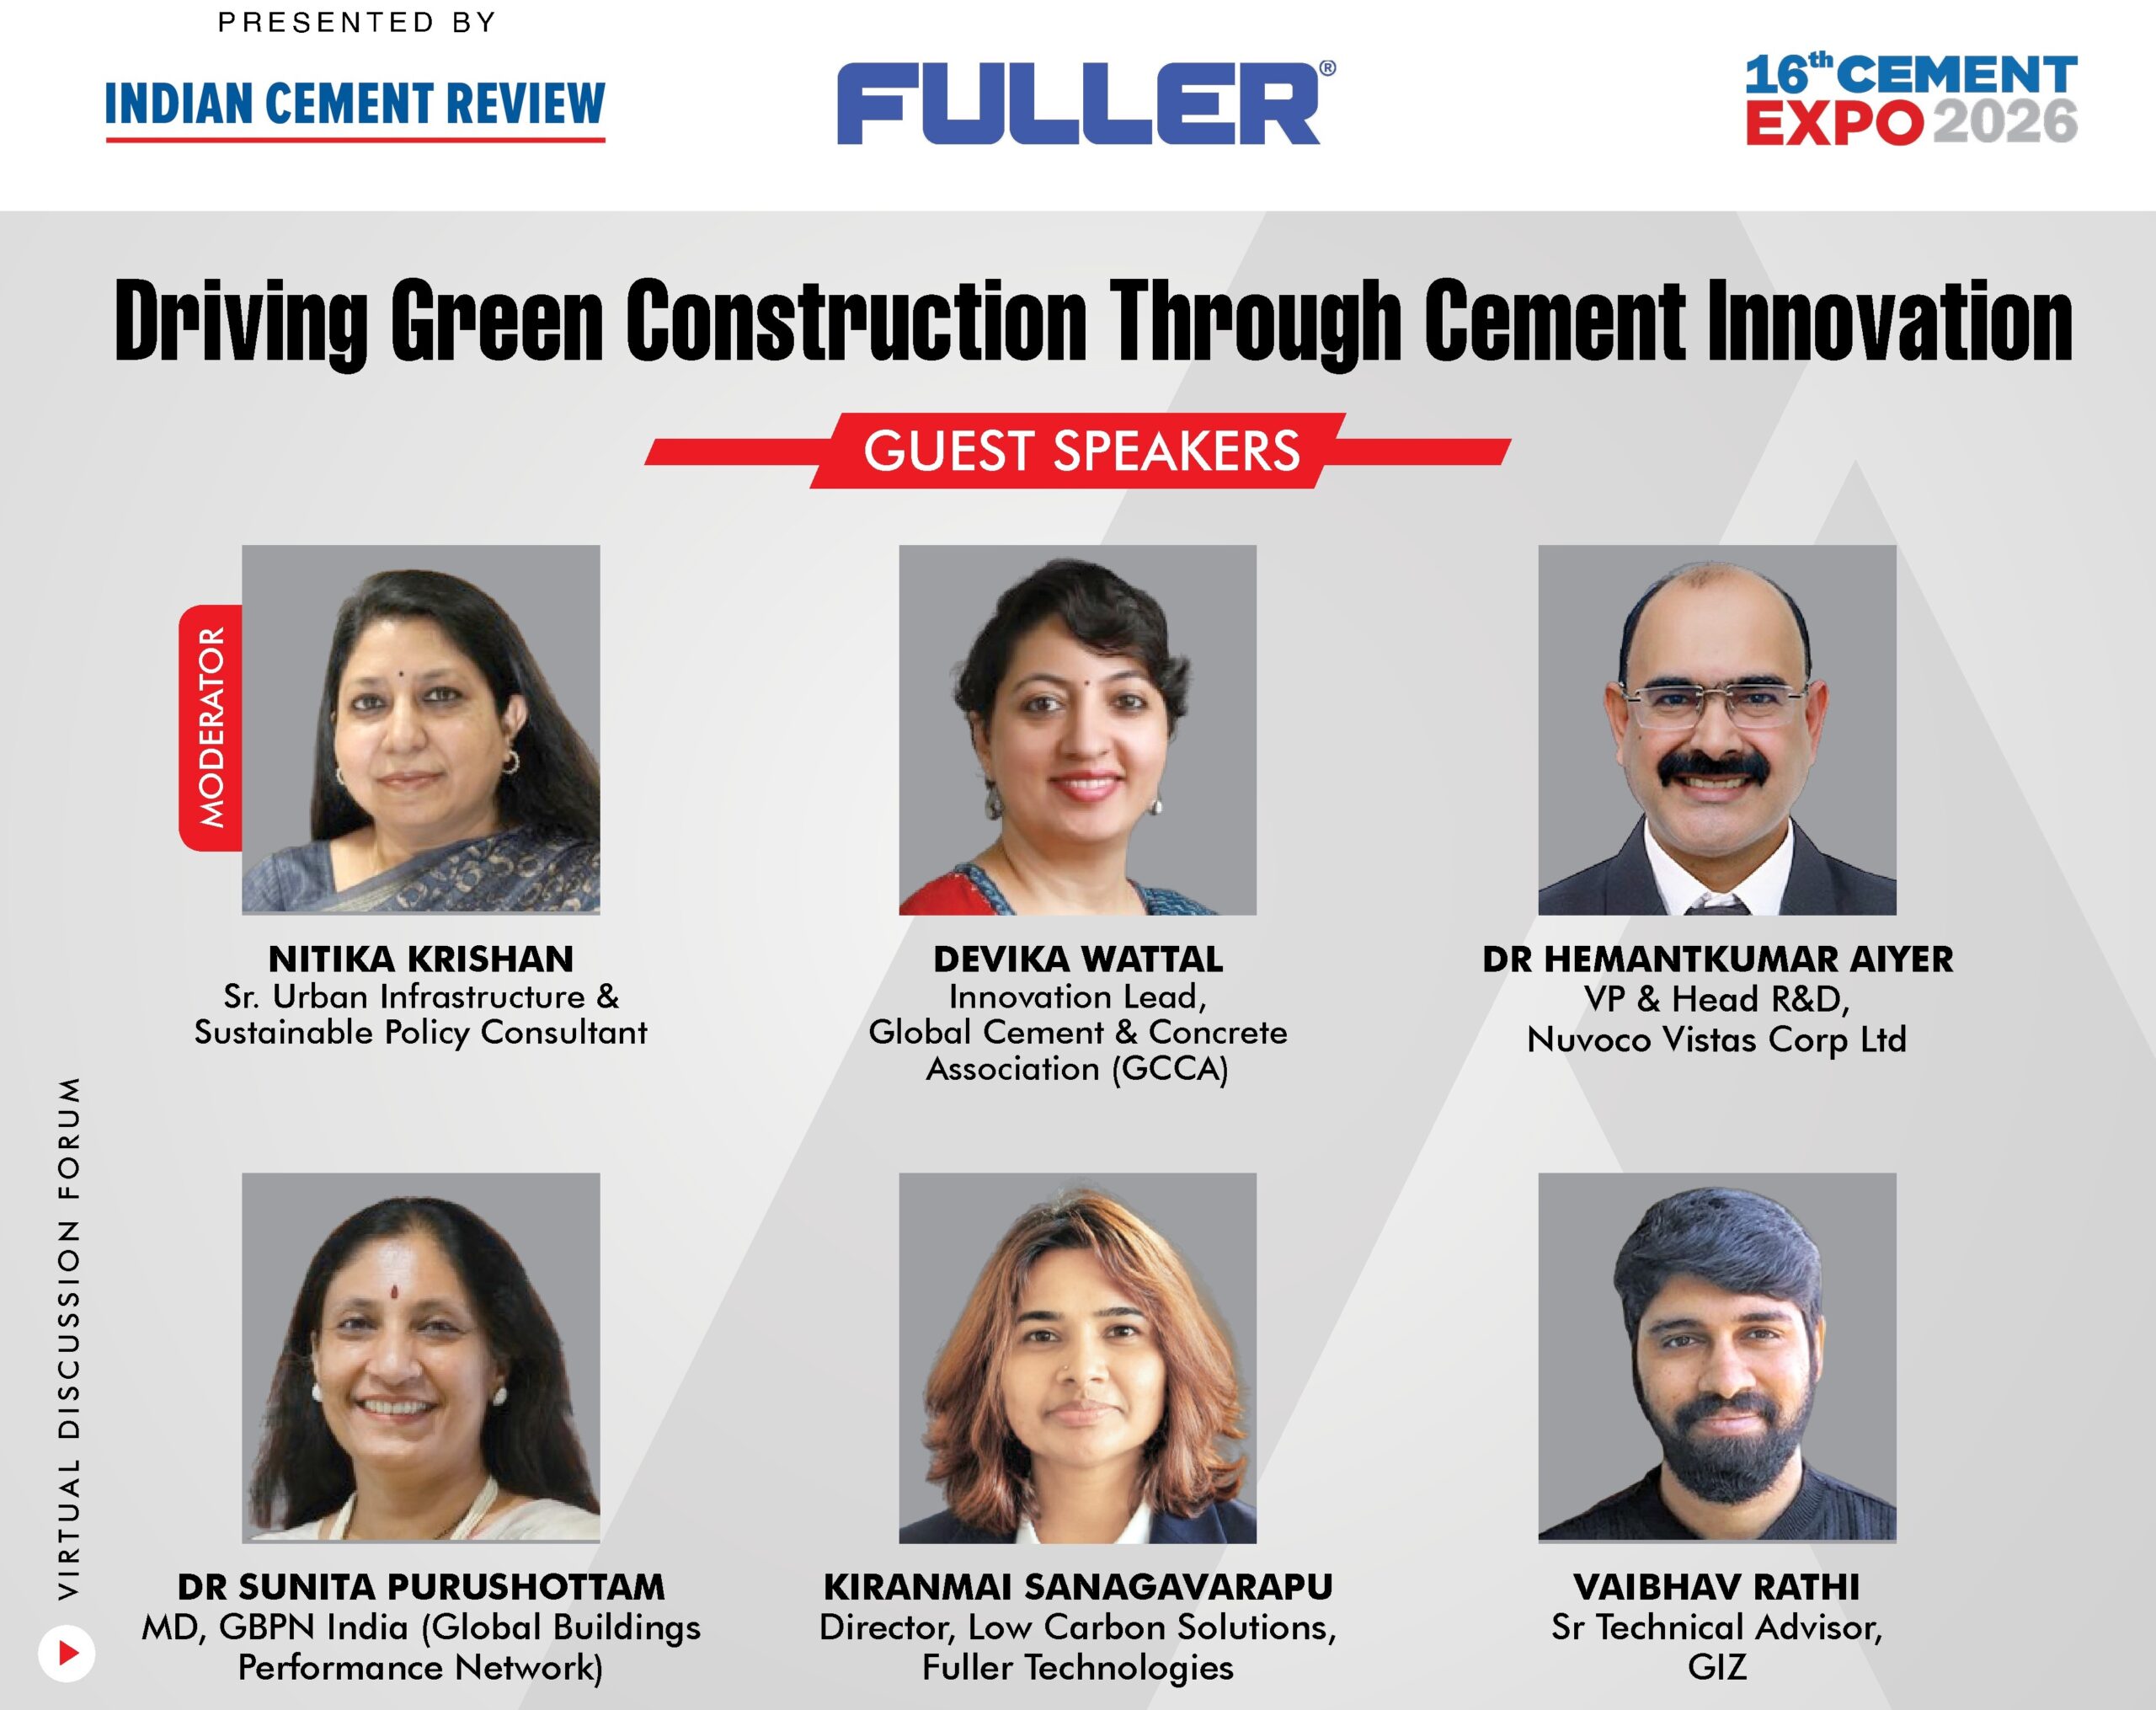
That question formed the core of an online panel discussion titled “Driving Green Construction Through Cement Innovation”, organised by Indian Cement Review (ICR) in association with Fuller Technologies as the Presenting Partner on June 25, 2026. The webinar brought together experts from cement technology, R&D, global industry platforms, building performance policy and international development cooperation to examine how low-carbon cement and material innovation can accelerate India’s green construction transition.
The discussion came at a crucial time. India has committed to achieving net-zero emissions by 2070 and reducing the carbon intensity of its economy by 45 per cent by 2030. At the same time, the country’s construction sector is expanding rapidly, driven by urbanisation, infrastructure development, housing demand and industrial growth. Cement, as one of the most widely used construction materials, sits at the heart of this transition. It is indispensable to development, but also central to the challenge of reducing embodied carbon in buildings and infrastructure.
Moderated by Nitika Krishan, Senior Urban Infrastructure and Sustainable Policy Consultant, the panel featured:
Dr Hemantkumar Aiyer, VP and Head R&D, Nuvoco Vistas Corp Ltd;
Devika Wattal, Innovation Lead, Global Cement and Concrete Association (GCCA);
Dr Sunita Purushottam, MD, GBPN India (Global Buildings Performance Network); and
Vaibhav Rathi, Senior Technical Advisor, GIZ (the German Agency for International Cooperation)
Setting the tone for the discussion, Nitika Krishan underlined the scale of the challenge before the sector. “The question before us is no longer whether we build, but how we build sustainably,” she said. She pointed out that construction accounts for nearly 40 per cent of global energy-related carbon emissions when both operational and embodied carbon are considered. Cement production, she added, remains one of the hardest industrial processes to decarbonise.
For India, this is not merely an environmental issue. It is a development issue, a competitiveness issue and increasingly, a market issue. As one of the world’s largest cement producers and among the fastest-growing construction markets, India’s material choices will influence the carbon trajectory of its built environment for decades. As Krishan observed, sustainability solutions in economies such as India must not remain limited to laboratory success. They must be scalable, commercially viable and practical at national level.
The innovation gap: From technology to market
Experts believe that there is a need to bridge the innovation gaps for making decarbonisation in cement and concrete scalable. Devika Wattal of GCCA, explained, “The starting point must be the core cement manufacturing process itself. The first and foremost is the heart of our process, the heart of cement manufacturing. How do we reduce clinker? That is always a topic where industry is working very intrinsically.”
Clinker reduction remains one of the most important pathways for lowering emissions in cement. Since clinker production is energy-intensive and chemically emits carbon dioxide, reducing the clinker factor through supplementary cementitious materials (SCMs), blended cements and new chemistries can have a significant impact. Wattal also noted that carbon capture, utilisation and storage (CCUS) will have a role, though it may not be the first lever for all markets.
However, she stressed that innovation cannot stop at technology development. A solution that works in the lab must also be adaptable to industry, scalable in production and acceptable in construction practice. “It is important for that innovation to be adaptable, to be scalable, and so that it can be executed in real time,” she said.
Wattal also called for stronger enabling systems around innovation. These include performance-based standards, product-level embodied carbon databases and clearer frameworks for evaluating green materials. Without these, low-carbon cement products may struggle to compete with conventional materials in procurement and design.
R&D must balance carbon, cost and performance
Bringing in the R&D perspective into the discussion, Dr Hemantkumar Aiyer of Nuvoco Vistas emphasised that low-carbon cement development cannot be treated as a single-variable exercise. Cement must perform in real construction conditions. It must deliver strength, durability, consistency and cost competitiveness, while also reducing carbon.
“The root of understanding and balancing all these aspects lies in materials, and knowing the materials,” he said.
According to Dr Aiyer, R&D teams must understand the variability of raw materials such as fly ash, slag and clinker. Different sources produce different material behaviours. This makes mix optimisation, material characterisation and processing-property relationships critical. When performance is affected, cement manufacturers must understand how strength enhancers, admixtures and other performance chemicals interact with the material system.
He also linked material science with process efficiency. Clinkerisation takes place at extremely high temperatures, around 1,400 to 1,450 degrees Celsius. Any improvement in raw mix design, process control or energy optimisation can, therefore, help reduce emissions and cost. Dr Aiyer pointed to artificial intelligence-based optimisation, Cement 4.0 tools and advanced software as important enablers for real-time process and material control.
“The more you understand the materials, the more you can control it,” he said.
LC3: The promise is proven, the sequencing is not
Limestone calcined clay cement, commonly referred to as LC3, has attracted global attention because it can reduce clinker content significantly by using calcined clay and limestone while maintaining performance in many applications. Kiranmai Sanagavarapu of Fuller Technologies said the technology itself has already moved beyond proof of concept. Fuller Technologies has worked with calcined clay technology for nearly two decades and has seen plants running in France and Ghana. These plants, she said, are meeting local and national specifications, while the economics are beginning to make sense.
“The calciner is performing, the economics is stacking up, it is making business sense to produce,” she said.
But if the technology is viable, why has adoption not scaled faster? For Sanagavarapu, the answer lies in project sequencing. Too often, clay characterisation happens after equipment is specified. This, she warned, is a backward approach because calciner design depends on clay mineralogy, kaolinite content, iron levels, reactivity, moisture and other variables.
“If you don’t know what your deposit looks like before you commit for the equipment, you are, in a way, going blind into designing,” she said.
She also identified permitting and plant integration as major bottlenecks. Environmental clearances, mining permissions and local regulatory approvals must begin early. Similarly, calcined clay must be integrated into existing grinding, blending and logistics systems from the design stage, not treated as an afterthought during commissioning.
India already has IS 18189:2023 standard for LC3, but Sanagavarapu pointed out that the standard is not yet visible enough in procurement documents. “The gap between what is technically being permitted and what the procurement is asking is the single biggest bottleneck,” she said.
In her view, successful scale-up depends on getting the sequence right: clay characterisation first, permitting in parallel, standards aligned with construction, and integration built into plant design.
India’s LC3 journey: Progress, but demand remains thin
Providing details of India’s LC3 commercialisation experience, Vaibhav Rathi of GIZ noted that JK Cement carried out the first commercial production of LC3 at its Rajasthan plant, followed by JK Lakshmi Cement three months later. These initiatives were supported by the International Climate Initiative of the Government of Germany, with IIT Delhi contributing deep institutional knowledge on LC3 research and BIS certification.
Rathi said India’s early experience has produced clear lessons. One of the biggest was the need to build capacity among regulators. While BIS certification existed, State Pollution Control Boards were unfamiliar with the technology and unsure about the approval pathway.
“The capacity building is not just needed amongst the producer and the users of the cement, but also the regulators who are working with this technology for the first time,” he said.
He also highlighted the need for better information on China clay deposits. Since China clay is currently classified as a minor mineral, centralised data on availability, quality and location is limited. If cement manufacturers are to adopt LC3 at scale, stronger mineral intelligence will be important.
The third issue is demand. LC3 has already been used in projects such as Palava City in Mumbai and Noida International Airport, but these remain limited examples. “It is in a chicken and egg situation,” Rathi said. “Cement companies are saying we need more demand, and users are saying there is not enough cement available.”
Public procurement, he suggested, could help break this cycle. If agencies such as CPWD and other public bodies begin testing, accepting and specifying LC3, it could create the market confidence needed for cement companies to invest in production and storage.
Building codes must catch up with innovation
Dr Sunita Purushottam of GBPN India argued that material choices will determine built environment emissions over the long term, but India’s current policy signals remain fragmented. Although LC3 has received BIS recognition, she pointed out that building codes, municipal bylaws, schedules of rates and sustainability codes do not yet provide uniform guidance on low-carbon cement.
“The current cement regulations are largely prescriptive and favouring traditional materials,” she said. This limits the ability of alternative materials to compete on performance, durability and emissions.
Dr Purushottam also raised the issue of taxation. Cement, including LC3, currently falls under the same GST bracket as conventional cement. A differentiated tax structure, she argued, could help accelerate market adoption. “In order for the market to demand LC3, that differentiation in the GST could go a long way,” she said.
She noted that green building certifications such as IGBC and GRIHA are already creating demand for low-carbon materials by assigning points for embodied carbon and sustainable material use. However, she said large-scale adoption will require regulatory mandates, particularly through building codes and state-level notifications.
She also cautioned that low-carbon cement alone does not solve the entire building performance problem. A material may reduce embodied carbon, but the operational carbon of a building depends on thermal performance, design, insulation and energy use. “The energy part has two elements,” she said. “One is the embodied carbon of the material itself, and the other is the operational carbon.”
Collaboration is the bridge between invention and impact
Wattal said GCCA sees innovation as a strategic priority and works through platforms that connect industry with academia and start-ups. “There is no way we will decarbonise our sector without innovation,” she said.
However, she stressed that research must be connected to actual industry challenges. Innovations developed in isolation may fail when they encounter real-world barriers such as raw material variability, plant integration, cost, standards and finance. Start-ups, too, need industry mentorship and scale-up pathways.
Wattal also flagged the importance of finance. Even strong technologies may struggle to attract investment if there is no common understanding of bankability. “We have always put projects into, is this a bankable project? But the definition of a bankable project has never been defined,” she said.
For India, she saw strong potential in its academic and start-up ecosystem, but said the challenge lies in alignment and prioritisation. The country has the research base, industrial capacity and market size. What it now needs is a coordinated route from innovation to deployment.
There is a practical concern for cement manufacturers: how can existing plants be adapted for lower emissions without compromising reliability or commercial viability?
Kiranmai Sanagavarapu addressed, “The reliability risk in calcined clay retrofit is definitely real, but it is almost always self-inflicted. The risk arises when a new process is added to an existing circuit without properly redesigning grinding and blending configurations.”
Existing cement plants, she explained, can take two broad routes. The first is external sourcing of calcined clay combined with mill optimisation. This requires lower capital investment and can potentially move in 12 to 18 months if other conditions are in place. It may reduce emissions by around 20 to 30 per cent. The second route is integrated calcination on site, which requires higher capital expenditure and longer lead times, but provides greater control over quality, supply and emissions reduction potential.
For Sanagavarapu, the principle is simple: low-carbon retrofits must be designed with intent. “Design it with an intent properly from the start. Start in the market conditions where the economics are already working,” she said.
Circularity: The overlooked advantage
According to Vaibhav Rathi, fly ash and slag are already well established in cement and construction (C&D), but construction and demolition waste remains underutilised. “C&D waste is a growing business opportunity which not many have taken up,” he said. India’s continuous construction and demolition activity creates huge volumes of waste, much of which contributes to air pollution, land degradation and material inefficiency. With the right processing and standards, this waste can be converted into useful construction products.
Rathi also pointed out that LC3 has a circular economy dimension that is often overlooked. It can use low-grade kaolin-rich clay left behind after high-grade clay is extracted for other applications. “LC3 is not only a low-carbon solution, but also a circular economy solution,” he said.
At the same time, he cautioned that LC3 in India is not yet cheap because it has not reached scale. Site-specific techno-commercial feasibility studies, supported jointly by development agencies and industry, could help companies assess whether LC3 production makes technical and financial sense at a given location.
Dr Purushottam added that India must address both low-carbon cement and construction waste together. “Both low-carbon cement and C&D waste go hand in hand. India does not have an option but to work on both,” she said.
Dr Aiyer called for policy shifts from both government and industry, including preferential purchasing of sustainable materials, minimum supplementary cementitious material requirements in public and public-private projects, and faster regulatory implementation. “If we can fast-track the regulatory standards and their implementation on the ground, that is the way to go,” he said.
From green ambition to green construction
Cement innovation is no longer only about chemistry. It is about systems. Low-carbon cement will scale only when technology, standards, procurement, finance, regulation, education and construction practice move together.
LC3 and other low-carbon technologies have shown promise. India has early commercial examples, strong research capability and growing market interest. But mainstream adoption will depend on whether demand can be created, regulators can be capacitated, standards can be embedded in procurement, and manufacturers can see a clear business case.
For a country building at India’s scale, the opportunity is enormous. Cement will continue to be central to infrastructure and urban development. The challenge now is to ensure that the cement used in India’s growth story carries a lower carbon burden.
Rakesh Rao
Participate in Cement Expo 2026 and discover how next-gen infrastructure can be built with innovations in cement.
NCL Industries has approved an investment of Rs. 5.95 bn for Phase 2 and Phase 3 of its 130 MW solar and wind power project in Tuticorin, Tamil Nadu. The approval covers the remaining 80 MW capacity and takes the estimated cost of the entire project to Rs. 9.87 bn.
The company, which manufactures cement, ready-mix concrete and other building materials, had approved the first phase on April 13, 2026. Phase 1 consists of 50 MW and was estimated to cost Rs. 3.92 bn. The project will be financed through a combination of debt and internal accruals.
Separately, the company’s board has granted in-principle approval to pursue a proposal for establishing a cement manufacturing plant in Odisha. NCL Industries plans to approach the Odisha government for project land and will undertake the applications and approvals required for the proposed facility.
The company said the Odisha project remains at a preliminary stage. No land allotment or definitive agreement has been executed, and it has not made any binding commitment to acquire or lease land as of the date of its disclosure.
Further action on the proposed cement plant will depend on applicable regulatory approvals, as well as the company’s additional evaluation and internal approvals. The board’s decision does not therefore represent a final investment commitment for the Odisha facility.
Shares of NCL Industries closed at Rs. 170.40 on the BSE on November 13, 2026, down Rs. 1.85, or 1.07 per cent, from the previous close. The company’s renewable energy expansion is intended to support its power requirements, while the Odisha proposal would add a new manufacturing project to its cement business if approved at a later stage.
Cement makers are set to see a significant improvement in profitability in the second half of FY27 as falling global oil prices reduce the cost of key fuels, including petcoke and coal. Higher cement prices are also expected to support earnings, according to a report by Systematix Group.
The cement sector remained resilient in Q2 FY27, with volumes across the companies covered by the brokerage rising 7.2 per cent year-on-year. Higher sales volumes and improved realisations contributed to top-line growth during the quarter, although fuel and packaging expenses remained near-term concerns for manufacturers.
The report said the impact of lower oil prices should gradually appear in fuel costs, though the transmission is likely to be delayed. Petcoke and coal prices generally follow movements in crude oil prices, and the recent decline in global oil prices is expected to provide relief in subsequent quarters rather than immediately.
Cement prices improved towards the end of the second quarter, while price increases implemented during September and October are expected to support realisations in H2 FY27. The combination of stronger selling prices and moderation in energy costs could help offset pressure from fuel and packaging expenses, particularly after the third quarter.
Demand conditions are expected to remain supportive, with infrastructure spending, housing demand and a recovery in construction activity after the monsoon set to drive consumption in the coming months. Demand in eastern markets remained subdued because of prolonged monsoon conditions and flooding, while northern, southern and western markets recorded stronger activity.
The report retained a positive view of the sector, citing resilient demand growth of 8 to 9 per cent, improving pricing discipline and the expected moderation in fuel costs. These factors are expected to support a sharp earnings recovery for cement companies during H2 FY27.
ABB reconditions 25 drives at ACC’s Jamul cement plant, avoiding 16 tonnes of CO₂ emissions while improving reliability through predictive maintenance. Chhattisgarh
ABB has signed a multi-year Motion OneCare service agreement with ACC Limited, part of the Adani Group, to modernise ageing industrial drives at its Jamul cement plant in Chhattisgarh, improving operational reliability while avoiding approximately 16 tonnes of carbon dioxide (CO₂) emissions without disrupting production.
Announced on 27 October 2026, the agreement combines scheduled drive reconditioning, digital condition monitoring and energy appraisals to extend equipment lifespan, improve plant uptime and optimise maintenance costs. The initiative marks a shift from conventional equipment replacement towards a more resource-efficient approach to industrial asset management.
The first phase, completed in April 2026, involved the on-site reconditioning of 25 ABB ACS800 variable speed drives without a major plant shutdown. By retaining the existing cabinets and restoring the drive modules rather than replacing entire panels, ABB helped ACC preserve capital investment, minimise material consumption and avoid approximately 16 tonnes of CO₂ emissions.
A second phase, covering an additional 25 ACS800 drive modules, is scheduled for the fourth quarter of 2026. The programme is designed to improve long-term equipment reliability while allowing maintenance activities to be aligned with the plant’s operational schedules.
The ACS800 drives, installed at Jamul in 2010, had delivered more than a decade of near-continuous service in demanding cement manufacturing conditions. However, ageing electrical components and changing fault patterns had begun to affect their ability to meet the plant’s reliability requirements.
Rather than opting for complete equipment replacement, ACC engaged ABB’s certified engineers to conduct a comprehensive asset health assessment. The evaluation found that the existing cabinets and enclosures remained structurally sound, making targeted reconditioning a technically viable and cost-effective alternative to full replacement.
Drawing on nearly two decades of experience with ACC’s equipment and operating requirements, ABB developed a maintenance framework tailored to the plant’s shutdown windows, budget cycles and production priorities.
The Motion OneCare agreement incorporates planned equipment restoration, condition-based monitoring and energy assessments, enabling ACC to adopt a more systematic approach to maintaining critical electrical infrastructure.
As part of the programme, ACC has implemented ABB Ability™ Digital Powertrain Insights to monitor drive performance and identify emerging operational issues before they result in equipment failures.
The digital platform provides continuous visibility into parameters such as temperature, current, vibration and fault patterns. These insights allow maintenance teams to detect early signs of equipment deterioration, schedule interventions more effectively and reduce the likelihood of unexpected downtime.
Amit Gupta, Local Division Manager, Motion Services, ABB India, said: “We know what unchecked wear costs over time: a small inefficiency that eats away at ROI for years. At Jamul, the evidence pointed clearly to assets with productive life still in them.”
“Our job was to restore them properly and give the team the tools to stay ahead of the next problem. At ABB, we don’t just fix what fails. We want to protect what works.”
The initiative also demonstrates the growing relevance of circular economy principles in cement manufacturing, where extending the service life of existing industrial equipment can reduce capital expenditure, material consumption and the environmental impact associated with manufacturing replacement components.
According to ABB, drive reconditioning can reduce lifecycle emissions by 50 to 80 per cent compared with complete equipment replacement. By preserving functional components and restoring critical modules, the process helps retain the economic and material value of existing industrial assets.
The addition of energy appraisals in subsequent phases will further expand the programme beyond equipment restoration, enabling ACC to assess drive performance, identify energy-saving opportunities and improve operating efficiency.
For cement manufacturers, variable speed drives play an important role in controlling motors and optimising energy consumption across production processes. Maintaining their reliability and efficiency is essential for minimising operational disruptions and managing electricity costs.
Vinod Bahety, CEO – Cement Business, Adani Group, said: “Moving from reactive firefighting to a structured maintenance plan was exactly what this operation needed. That kind of peace of mind doesn’t come easily. It comes from a partner that understands how your business runs.”
“We didn’t need a full system overhaul; we needed expert support, actionable insights, and a plan we could execute around our schedule. That’s what we got.”
The project supports ACC’s broader strategy to improve manufacturing efficiency through digital transformation, preventive maintenance and sustainable asset management.
ACC, a subsidiary of Ambuja Cements and part of the Adani Group, operates 20 cement manufacturing facilities and 119 ready-mix concrete plants across India. The company has been advancing initiatives focused on renewable energy, circular economy practices and technology-driven operational improvements.
Alongside Ambuja Cements, ACC is part of a large-scale building materials business committed to achieving net-zero emissions by 2050, with near-term and net-zero targets validated by the Science Based Targets initiative (SBTi).
The Jamul initiative aligns with these sustainability objectives by demonstrating how equipment life extension and digital monitoring can contribute to resource efficiency without requiring large-scale replacement of existing infrastructure.
ABB, a global technology company specialising in electrification and automation, brings more than 140 years of industrial expertise and employs approximately 110,000 people worldwide. Its Motion Services business supports industrial customers through equipment maintenance, modernisation, digital monitoring and lifecycle management solutions.
The agreement also reflects a wider shift in industrial maintenance practices, with manufacturers increasingly adopting predictive technologies to improve equipment availability, manage costs and reduce unplanned shutdowns.
With 25 drives already reconditioned and another 25 scheduled for restoration, ABB’s collaboration with ACC illustrates how targeted modernisation, digital monitoring and circular maintenance practices can extend the operational life of critical equipment while supporting more efficient and sustainable cement production.











 Concrete4 weeks ago

 Concrete4 weeks ago

 Concrete3 weeks ago

 Concrete2 weeks ago