Large cement companies cracked the code and invested heavily in high visibility ATL (above the line) advertising, says Sandip Ranjan Ghose of Birla Corporation.
The advertisement of an iconic tea brand features a shop-owner trying to sell a packet of ordinary tea to a customer- saying "Chai toh chai hi hota hain".. The lady refuses to take it, explaining why she preferred only that particular brand. Cement marketing used to be similar with little differentiation between the offerings by manufacturers.
There was another reason for the late marketing evolution of the cement industry. As long as cement was under the control regime customers had little choice. They had to pretty much settle only for what was available.
At best, there were some perceived differences, determined largely by visual attributes such as colour and fineness. These, at times, resulted in the products of certain plants commanding a marginal premium over others. Because of this, the name of the plant where the cement was produced became the brand rather than the company that owned it. So, the trade would refer to it as Jamul, Satna, Maihar, Kota, etc. depending on the source of supply.
Thus, there was little incentive for cement-makers to invest in marketing. All brands of cement were generically positioned in terms of strength. Rarely did the communication extend to technical parameters such as setting time, workability and other BIS standards. Therefore, it is not surprising that the sales teams of cement companies were referred to as marketing. A practice that has not entirely disappeared since not all companies have a separate dedicated brand marketing vertical.
Life began to change in the 90s after decontrol – when, with a surge in capacities, the industry saw cycles of supply-demand imbalance and, consequently, the impact of real competition in the market. The first serious attempt at brand building was probably by Gujarat Ambuja, which came to challenge the dominant player in its home turf.
The advent of multinationals and the ensuing spree of consolidation, most notably Grasim’s merger with L&T cements, permanently changed the rules of the game. Soon, cement companies became one of the biggest advertisers on television and dominated the outdoor space, covering practically every inch of exposed wall in the countryside.
What makes India different from many other countries is the route-to-market. With a very high component of retail customers – the Individual Home Builder (IHB) segment – bulk of cement sales, including supplies to small or medium-size builders and contractors, happen in bags through the trade network. RMC, still is at a nascent stage and only large sites, can handle bulk deliveries. Thus, it is essentially a B2C business – in which dealers and stockists are the first level of customers.
Large companies cracked the code and invested heavily in high visibility ATL (above the line) advertising. Television commercials-especially cricket sponsorship-pleased the channel partners and wall paintings helped raise TOMA (top of mind awareness) with rural consumers. However, marketers soon realised they were missing a vital link in the chain – the influencers, comprising Masons, Engineers and Contractors.
This led to a renewed emphasis on influencer contact programmes through BTL (Below the Line) marketing activities. From simple gratification schemes, market leaders started developing more sophisticated technical selling competencies.
Separate Technical Services or Customer Service Teams were formed with the mandate for customer conversion through on-site demonstration. So, cement marketing drew from both pure play consumer and industrial product categories to developing a unique marketing mix, that is a combination of B2B and B2C businesses. The large players were naturally the early adapters as they jostled for space at the premium end of the market. This saw a burst of creativity but without any significant product innovation.
The first major disruption came with the introduction of laminated bags – pioneered by the erstwhile Lafarge for its Concreto brand of slag cement. The "tamper proof" packaging provided the consumer with a "reason to believe" the superior quality claim, addressing two common concerns of moisture absorption and pilferage. On the back of this innovation and smart celebrity advertising, Lafarge was able to establish itself over peers in its core markets.
However, not everyone was impressed. Traditional companies thought the extravagance of MNCs and large Indian conglomerates were wasteful. Much like the "tea-seller" they saw little point in branding a commodity. The old guard preferred to remain "price-takers" (and, in some cases, "cost warriors") and not spend resources for the race for price leadership.
This diametrically opposite strategies of two sets of players had an interesting impact on the market structure, polarising it into two distinct segments of premium and discount brands that came to be popularly known as "A" and "B" Group. The price gap between these was accentuated during 2010-2011 when the industry saw one of the steepest declines in demand growth. Since then, the twain has not met though, as we shall see later, there has been some cross currents between them.
The sustained investment in brand building had a positive fall out for the industry. Years of commoditisation of the product had led to very low consumer engagement with the category. But, with increasing visibility, thanks to the rural penetration of satellite television and high viewership of sports (primarily cricket) and news channels (rise in political awareness and high stake elections), consumer involvement with cement palpably increased.
This shift in consumer mindset coincided with the rise of aspirational middle class in "Bharat" comprising tier 2 and 3 cities, small towns and "urban" areas. This was in sync with trends in related products for construction and home-building, such as paint, tiles, sanitaryware and toilet fittings. The sentiment of "you build a home only once" resonated with "new India"more than ever before.
During the last decade, if one were to analyse, cement price increased marginally in real terms. However, the cost push on Fuel, Power and Logistics was relentless. This put margins of cement companies under pressure. This could only be partially insulated by tax incentives for new units and reducing lead to market by setting up grinding units closer to cementitious sources and consumption centre. But, manufacturers realised that the cushion will not last for ever. Salvation in the longer run, therefore, lies in improving realisation while ruthlessly pursuing cost reduction. Thus was born the new cult of "Premiumisation" in cement industry. Companies in the so-called"B" segment jumped on to the premium bandwagon by launching brands in paper (LPP) bags. Group A leaders launched"super-premium" variants with special attributes. While everyone was nibbling at different ends of the pie – a clear strategy was not in sight.
MP Birla case study
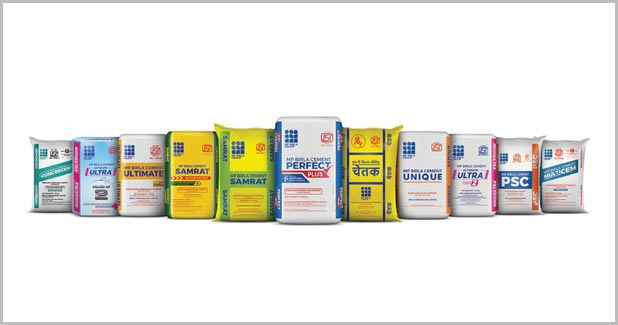
Sometimes, necessity is the mother of virtue. Birla Corporation faced a unique challenge. Due to historical legacy, it had inherited a slew of regional brands across the geographies where it was present. While Birla Chetak, often called Ghoda Chhap Cement by consumers, was its dominant brand in Rajasthan and North India, Birla Samrat (popularly referred to as Satna Cement) was its flagship in Central India. In the East, it had a niche premium slag cement, Birla Unique.
This put serious impediments in developing an unified brand strategy for the Company. There was considerable confusion in brand recognition among consumers and the trade due to the presence of several cement brands with the "Birla" suffix in the same markets. To resolve that it was imperative to have a common brand identity. Also, without a sizeable national presence it was not possible to provide adequate ATL support to each of the brands.
Merging the brands was not an option " because that would destroy the strong regional equity of each brand. Therefore, a mega brand transition like what UltraTech undertook after its acquisition of L&T’s Cement Division was neither advisable nor viable given Birla Corporation’s size and scale of operations.
The problem was compounded – when Birla Corporation acquired the Cement Business of the Reliance ADAG group in 2016. The Business Transfer Agreement provided a very short window for using the Reliance brand name. So, a quick name-change was almost a condition precedent of the deal. This posed several challenges on the marketing front. Though Reliance Cement had a very short life-span it had established its own brand salience. Reliance Group insignia gave it a special halo that could not be easily substituted in the trade and consumer mind-space.
At the same time, any value destruction of the brand would jeopardise the financials of the deal. However, the marketing team saw this as an opportunity to create a brand architecture for the group under a new MP Birla franchise. The strategy was based on segmentation of the market both in terms of price-points and geographies. Reliance Cement brand morphed into MP Birla Perfect Plus and became the group’s flagship premium cement brand across all markets.
The seamless brand transition ensured business continuity with minimum disruption in the trade channel, which helped the company scale-up and consolidate within a short time. Since then, MP Birla Perfect Plus has been extended into new geographies, increasing its share in the premium cement segment. Now, nearly 40 per cent of MP Birla Cement’s trade sales come from the premium segment " one of the highest among its peer group.
The Brand Architecture is founded upon the strong pillars of the regional Heritage Brands (Chetak and Samrat), flanked by Super-Premium and niche offerings. To have a common pan-India offering for the non-trade and Institutional customers and preserve the sanctity of trade (B2C) segment – MP Birla Cement has two special brands Multicem (blended cement) and Concrecem (OPC).
Albeit a very evolved architecture – it has probably yielded results with MP Birla Cement’s high share of trade sales (81.61 per cent) and blended cement (92.5 per cent) in the portfolio, during April to December/FY20.
The future of Cement Marketing, like almost every other category, is clearly Digital. We already find companies investing heavily in Data Analytics, CRM and Loyalty programmes for trade and Influencers and preparing for e-selling. The consumer today is more aware, tech savvy and looks for the best while building his dream house. The key would be to provide segmented solutions.
The future clearly belongs to brands offering segmented solutions to customers. Those who understand and connect with the consumers best will ultimately win the game.
ABOUT THE AUTHOR: Sandip Ranjan Ghose is the Chief Operating Officer of Birla Corporation (MP Birla Group). He has worked in senior leadership roles at Hindustan Unilever, ABP Group, HT Media and Lafarge. He is an ICF – PCC Leadership Coach. Ghose is a popular blogger, op-ed columnist and social-media influencer.









 Concrete4 weeks ago

 Concrete4 weeks ago
 Concrete1 month ago
 Concrete1 month ago