Connect with us

Concrete

A new phase of structural adjustments prompted by Bullwhip

Published

on

Shares

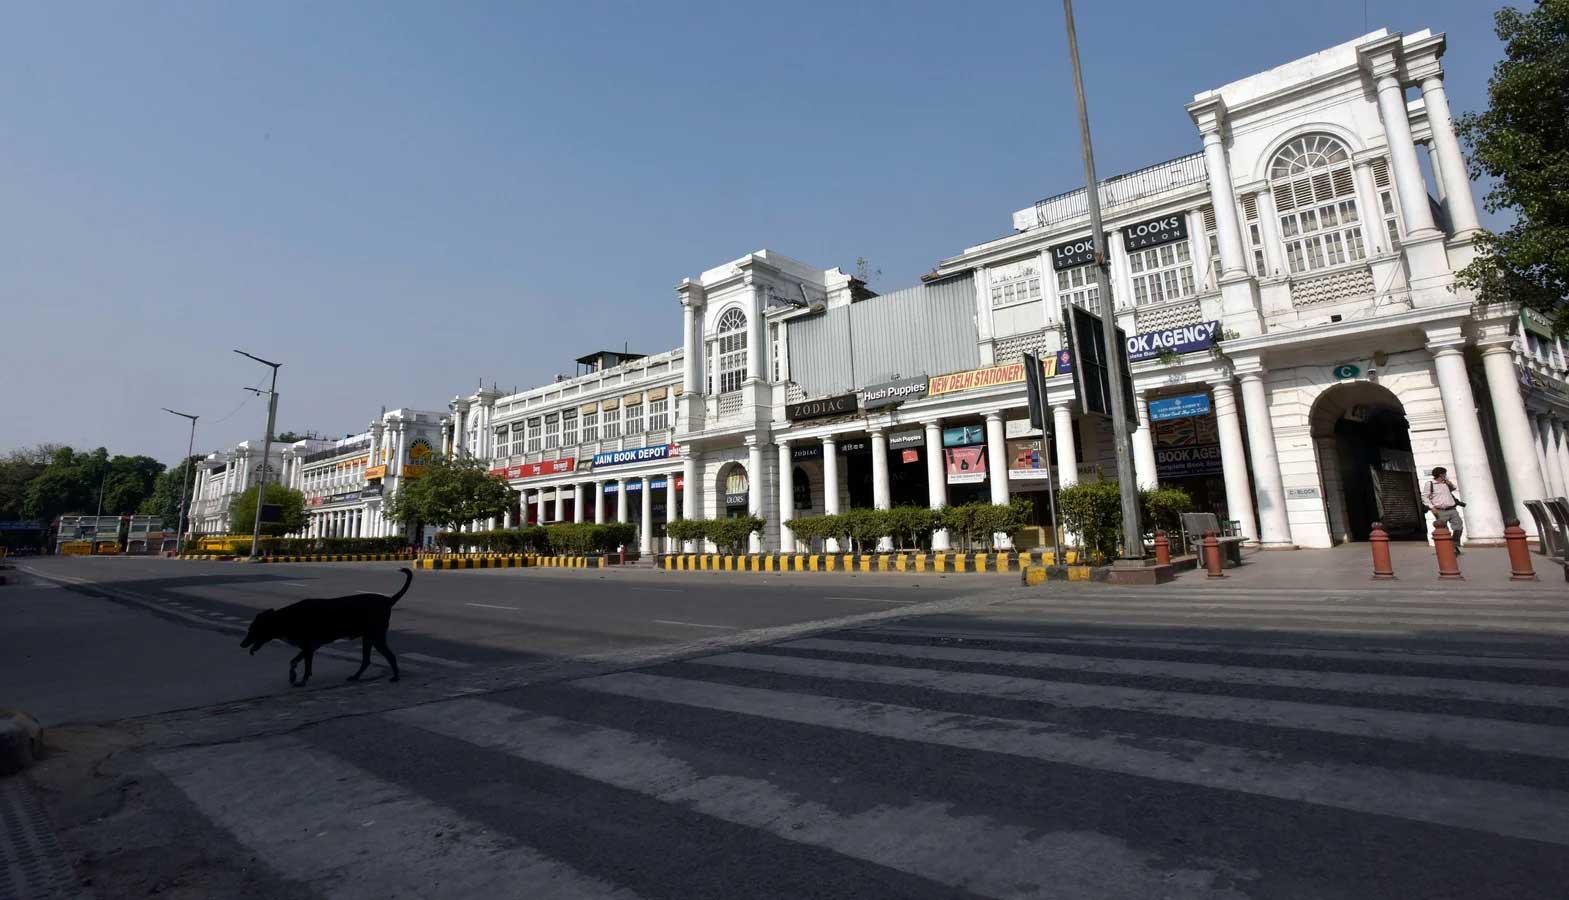
The latest data on the 2020-21 Q4 GDP shows a growth of 1.6 per cent over 2019-20 Q4, which in absolute numbers looks like Rs 38.96 lakh crore, as against Rs 38.33 lakh crore in Q4 of 2019-20. If anyone wants to see this in dollar terms, the dollar made a steep fall against the Rupee (Rs 75 v/s Rs 72.5) over this period, thus making the growth look like 5 per cent instead of 1.6 per cent. Despite these aberrations, the Indian economy weathered a major storm last year and both Q3 (0.5 per cent) and Q4 (1.6 per cent) have been two quarters of growth thus signaling a ??oming out??from the technical recession that was caused in Q1 and Q2 of 2020-21.

The drivers of growth however have shifted majorly in Q4, if one sees the sectorial data, the biggest unit of rise came from the government consumption expenditure increase of 28.3 per cent in the same period over last year. If we start with gross value added (GVA) growth (GDP growth minus product taxes), the manufacturing sector accelerated to 6.9 per cent in the fourth quarter of 2020-21 compared to a contraction of 4.2 per cent a year ago and construction grew by 14.5 per cent against 0.7 per cent, while both agricultural growth (down 3.1 per cent from 6.8 per cent) and hospitality and transport (down -2.3 per cent from 5.7 per cent) showed markedly lower numbers. We must keep in mind that only a week was lost in production activity in the corresponding quarter of last year, due to lockdowns, thus the two periods in terms of economic flow are not out of whack in comparison.

The crucial question is what we now expect the economy to perform, given that 66 per cent of the time in Q1 2021-22 is mired in semi-lockdowns, the informal sector is impacted heavily and working capital is locked in unforeseen inventories of all kind and debt moratoriums are being requested for another extended period of time over the previously allowed one. The question cannot be about comparing period numbers alone. Last year?? similar period was worse off with national lockdowns and the expectation at the start of the quarter was to achieve 22 per cent growth over that quarter. This looks a tall ask given the current state of the economic activities.

Let us move to some other dampening factor, perhaps more ominous than the stalling of economic activities through lockdowns. It is the rising commodity prices, which has seen no calming effects, either from the government or trade interventions, left to its own, the prices have spiraled into an orbit; many are calling this a precursor to the super cycle for commodities.

I am however of the view that the rise in global commodity prices, which finally impact every citizen of every country, were actually fueled by rising international logistics cost, global shipping to start with and followed by the inland full truckload freight costs, which later spilled over to every aspect of commodity prices.

The global barometer of logistics costs, the Baltic Dry Index stands at 2750 today, compared to 400 at the start of the crisis and the Shanghai containerised freight index stands at 3500 against 1000 at the start of the crisis last year. These numbers portray how many times the shipping costs have soared to move commodities from oil, coal, pet coke, to agricultural commodities to intermediate products to finally finished goods. The dollar weakness in the same period did adjust in some normative ways to counteract, but it is nowhere close to fully compensate for the deluge.

Every household item has moved several notches up in terms of prices, if they have not then sellers are simply absorbing the brunt of the increase from the input side.

This is what I call the supply side structural shift that every economy has to weather for the next several quarters. It all started with a shipping disruption, where vessels were stranded in high seas, which later moved to ports in form of congestion and then later impacted loading and unloading of vessels as people were not available. The final nail was the concentration of big five shipping lines that shared space among their carriers thus making the supply side even more tight, thus raising prices.

The structural shift needs to be seen from the point of what supply chains grapple with, the Whiplash effect, or the more commonly known Bullwhip effect. This essentially means that in a multi-echelon supply chain, for a small change in supply or demand conditions at the downstream part of the chain could translate to a much bigger change in the supply or demand conditions at the upstream part of the chain.

For an economy as diverse as India, with several supply chains crisscrossing each other, the disruptions in supply conditions in one part of the chain moves up or down the chain in varying degree of ripple effects, that are caused due to asymmetry of information, error propagation, ship-set mismatches and a host of financial woes travelling in multiple directions, working capital, inventory and cash flows being the key ones.

The supply chains in India have to adjust in these conditions and create new rules so that they are able to reconfigure their outputs and flows such that the new varying degrees of demand can be matched with varying supply conditions under constraints. This is the task that will be able to respond to price conditions better, something that will determine the next phase of GDP growth, not only for India, but for the globally connected markets as well.

Footnote:

ABOUT THE AUTHOR:

Procyon Mukherjee is an ex-Chief Procurement Officer at LafargeHolcim India.

Continue Reading
Click to comment

Leave a Reply

Your email address will not be published. Required fields are marked *

Concrete

Cement Prices Likely to Rise Rs. 10-15 per Bag from Mid-October

Input costs and steady demand may drive cement price increases

Published

on

By

Shares

Cement manufacturers in India are likely to raise prices by Rs. 10-15 per bag from mid-October, as they seek to offset persistent increases in power and fuel costs. Emkay Research said its channel checks indicated a high probability of an increase from October 12, supported by the start of the busy construction season and favourable demand-supply conditions.

The sector had implemented similar rate adjustments of Rs. 10-15 per bag during the first quarter, but the increases were insufficient to cover higher operating costs. Prices also softened during July and August because of the monsoon, widening the gap between realisations and input expenses. Delayed plant expansion programmes have pushed clinker utilisation rates towards 79 per cent by FY28, helping to balance market fundamentals.

Emkay Research said steady volume offtake was supporting cement consumption, with non-trade demand driving activity across regional markets. Industry volumes are expected to grow by 7-8 per cent year on year during the first half of FY27, while demand momentum is projected to remain firm over the following 18 months. The outlook includes the busy construction season in the second half of FY27 and infrastructure activity linked to general elections in the first half of calendar year 2029.

The brokerage expects overall cement demand to record a compound annual growth rate of about 7 per cent between FY26 and FY28. However, elevated operating expenses are likely to continue weighing on profitability. Input costs have risen by Rs. 300-400 per t over the past six to seven months, with the full impact expected to become visible in second-quarter earnings and remain persistent through the second half of FY27.

Spot prices for petcoke and imported coal are approximately 20 per cent and 16 per cent above their second-quarter averages, at USD 175 per t and USD 150 per t, respectively. Packing costs have also increased, with polypropylene granule prices rising above Rs. 135 per kg. Emkay Research estimated that second-quarter earnings could decline by Rs. 200-250 per t sequentially because of higher fuel bills and negative operating leverage, and said the sector requires sustained price increases of about Rs. 10 per bag to offset cost inflation.

Continue Reading

Concrete

Nuvoco Marks 10 Years, Targets 35 MMTPA Capacity by FY28

Nuvoco celebrates a decade of growth, targeting 35 MMTPA cement capacity by FY28.

Published

on

By

Shares
Nuvoco Vistas Corporation Limited is celebrating a decade of operations under the theme ‘Dus Saal Bemisaal’, highlighting its expansion in India’s building materials sector. The company has grown from a single cement manufacturing facility into a diversified organisation operating across cement, ready-mix concrete (RMC) and modern building materials.
The company’s journey began in 2014 when its parent, Nirma Group, commissioned a 2 million metric tonnes per annum (MMTPA) greenfield cement plant at Nimbol, Rajasthan. A major milestone followed in October 2016 with the acquisition of Lafarge India, significantly expanding its manufacturing footprint.
Nuvoco strengthened its market presence through the acquisition of Emami Cement, now NU Vista Limited, in 2020, followed by its public listing in 2021. In April 2025, the company added Vadraj Cement to its portfolio, strengthening its presence in western India.
Nuvoco has an operating cement capacity of 27 MMTPA and 14 manufacturing units, including the Kutch and Sachana facilities in Gujarat, which are in advanced stages of completion. It also operates 58 ready-mix concrete plants across India and offers a range of modern building materials.
The company aims to increase its cement capacity to 35 MMTPA by FY2027-28, representing approximately 15-fold growth over the decade.
Reflecting on the milestone, Hiren Patel, Chairman, Nuvoco Vistas Corporation Limited, said, “From our beginnings at Nimbol to the organisation we are today, every milestone has added a new chapter to Nuvoco’s journey and strengthened our belief in building for the long term.”
The company continues to focus on capacity expansion, operational efficiency, innovation and sustainability while strengthening its position in India’s construction materials market.

Continue Reading

Concrete

J&K Government Notifies City Gas Distribution Policy

Policy targets PNG and CNG expansion across all 20 districts

Published

on

By

Shares

Jammu and Kashmir government has notified the City Gas Distribution (CGD) Policy, 2026, following its approval by the Council of Ministers headed by Chief Minister Omar Abdullah. The policy sets out a phased framework for expanding Piped Natural Gas (PNG) and Compressed Natural Gas (CNG) access for households, businesses, industries and the transport sector across the Union Territory.

CGD networks will be expanded in phases across all 20 districts, with the aim of bringing reliable natural gas closer to consumers and supporting a gradual shift from conventional fuels. The government said the policy is designed to improve energy access while creating an investor-friendly and time-bound environment for gas distribution projects.

The policy provides for single-window and time-bound clearances, streamlined procedures for setting up CNG stations and standardised norms for the Right of Way. These measures are intended to reduce procedural delays, simplify project implementation and facilitate investment in natural gas infrastructure.

It also prioritises gas connectivity for major industrial estates, including those in Kathua, Samba and Pulwama. Improved access to natural gas is expected to support industrial activity, enhance energy efficiency and help businesses manage fuel costs, while strengthening their competitiveness and encouraging investment in the clean-energy sector.

The policy is also expected to create opportunities for local employment, apprenticeships and skill development in the construction, operation and maintenance of gas distribution networks and related services. Abdullah described the measure as an important step towards cleaner growth, sustainable development and a modern energy ecosystem in Jammu and Kashmir, saying it would expand reliable energy access and support industry and investment.

Continue Reading

Video Thumbnail
▶

    SIGN-UP FOR OUR GENERAL NEWSLETTER

    Trending News

    SUBSCRIBE TO THE NEWSLETTER


    Don't miss out on valuable insights and opportunities to connect with like minded professionals.


      This will close in 0 seconds