Economy & Market
Indian Cement Industry: The year gone by and the challenges ahead
Published
15 years agoon
By
admin
Though the year 2011 has been bumpy for the Indian cement sector, demand growth for the sector is likely to bounce back given the positive outlook of the general construction and infrastructure sector. The main impediments which have impacted the industry are the recent devaluation of the rupee and bank funding becoming costlier for the industry. This has led to a rise in import & input costs for the company in the form of freight and logistics cost. Read on to know the journey of the Indian Cement industry in the current scenarioIndia is the second largest producer of cement in the world after China and the Indian cement industry has seen a tremendous boom during the last few years in sync with the booming Indian economy. However, the fiscal 2011-12 saw the Indian economy suffering a setback due to an increase in inflation, spiking interest rates and a surge in the prices of commodities and fuels alongwith a devalued rupee. A lull has also been observed in the country’s housing sector, which accounts for over 60-70 percent of the country’s cement demand.Pervasion of a negative sentiment in the Indian Economy :As per the monthly "Economic Watch for November 2011" brought out by the Federation of Indian Chambers of Commerce and Industry (FICCI), the country’s economic growth is expected to slump to 6.6-6.8 percent in the financial year 2011-12. This projection by the industry’s apex body comes in the wake of the Indian government having lowered the country’s GDP growth forecast from the originally projected 9 percent to 7.25-7.75 percent. A poor performance by the mining, manufacturing and capital goods sectors resulted in a 5.1 percent on year contraction in the country’s industrial production in October in over two years. The growth of India’s GDP in the July-September quarter was pegged at 6.9 percent, the lowest in two years on account of the weak global fundamentals and a tight monetary policy by the government. The export sector is also likely to witness a moderation given the bearish fundamentals gripping the world economy. The situation has been complicated further by a widening trade deficit in the current fiscal. Exports for the April-November period increased by 33.2 percent on year to $ 192.7 billion while imports rose by 30.2 percent on year to $ 309.5 billion.A gloom has also been witnessed in the investment climate of the country with a slowdown in the housing and construction industry, which are critical demand drivers for the cement industry. This view was further emphasized by Jayram Nambiar, Ex Managing Director, Pfeiffer India Pvt Ltd who stated, "there has been a substantial reduction in private investments in major capital projects in 2011. There has been low government expenditure on public projects and a fall in investment levels in the housing and construction industry. The cement industry is unlikely to see a revival in demand to the tune of 8-9 percent for some time."Indian Cement Industry : The year that wasThe negative sentiment in the economy has also found its reverberations in the cement sector.Jayram Nambiar, Ex Managing Director-Pfeiffer India Pvt Ltd has concurred "as per a report by the CMA, the country produced 98.81 mt of cement in April-October 2011 which is only 1.2 percent higher than 96.75 mt produced in 2010. A slowdown in demand for cement has been noticed from the housing industry and if the trend continues, the annual growth in demand for cement will remain in the range of 3 per cent on a year on year basis , in 2011-12". The year 2011 also witnessed low cement capacity utilizations compounded by a fall in capacity additions. It was further observed that inspite of an oversupply situation, increased cost of inputs such as fuel and commodities led to a rise in prices of cement across India. Commenting on the capacity parameters for the cement industry, Umesh Shrivastava, Executive Chairman, Holtec Consulting Private Limited stated, "the average capacity utilization, over the year is likely to be in the range of 70-75 percent, which despite being low, is pegged at a level higher than the breakeven point of 50 percent. A slowdown has also been observed in capacity additions, with only 12-13 mtpa of capacity commissioned till now. A capacity addition of around 30 mtpa was expected to come onstream in the period April 1, 2011-31 March 2012." The industry was expecting the installation of around 15-20 mtpa of capacity in 2011. However, a difference in value perceptions between prospective sellers and buyers led to the prospect remaining unrealized. As compared to a peak cycle witnessed during FY 2007-08, cement industry utilization rates witnessed a downslide in FY 2011-12. Commenting on this aspect, Sumit Banerjee, Vice Chairman, Reliance Cementation augured, "the cement sector is cyclical in nature and continues to witness peak and trough cycles. Following a peak capacity utilization rate of 98 percent in FY08, the industry witnessed a down cycle with utilization rate falling to 74 percent in FY 2011-12. Hopefully, this should be the bottom of the cycle with the utilization rate expected to record an improvement to 76 percent in FY 2012-13 and further to 79 percent in FY 2013-14."A moderate 3.1 percent year on year growth in dispatches was recorded by the Indian cement industry in FY 2011-12, following a year on year increase of 4.5 percent in FY 2010-11. The bleak scenario was a result of muted demand, especially in the Southern Indian state of Andhra Pradesh due to political instability. Demand growth for cement in fiscal 2011-12 was expected to remain lower at 4.5 percent due to a slowdown in the economy, sluggish growth in infrastructure and real estate projects and a low momentum in government sponsored housing and irrigation schemes.Cost pressures also added to the woes of the cement industry in this fiscal. There was a rise in limestone mining costs due to a hike in prices of diesel in June 2011. Heavy monsoons in the coal mining areas also forced cement companies to import coal at inflated price levels due to a fall in the value of the rupee. High input costs coupled with a fall in demand led to a pressure on the margins of companies. Commenting on the cost factor, Sumit Banerjee, Vice Chairman, Reliance Cementation said, "severe pressure has been exerted over cement production costs over the last two years. The underlying reason behind the same was an increase in costs incurred on raw material, fuel and power, and freight costs which account for around 70 percent of the overall costs for the manufacture of cement. This has affected the operating margin of the industry, which has gone down significantly inspite of higher cement prices."The year can also be noted for technological developments which included waste heat recovery systems and utilization of lower grades of limestone for making clinker. Positive moves were also witnessed on the part of stronger players in the domestic cement arena who tried to establish production capacities outside India and acquire sources for solid fuel.The road aheadThe future largely appears bleak for the cement industry in the fiscal 2012-13 due to prevalent weak economic fundamentals. Commenting on the adversities likely to be faced by the industry, Jayram Nambiar, Ex Managing Director, Pfeiffer India Pvt Ltd said, "looking ahead, the economic scenario the world over and in India is anti growth and the worst is yet to come. The problem in India has been compounded by the current unfavorable political climate. The coming general election is unlikely to lead to the emergence of a strong political party or coalition. The growth levels of 2008-09 are not likely to be witnessed over the next two years. The period is also likely to be tough for the cement industry. The industry will have to deal with problems like rising energy costs compounded with the depreciation of the rupee, higher freight and distribution costs and low price realizations due to weak demand." These problems shall further be exacerbated by a rise in labour costs due to inflationary trends and a rise in the cost of living index. However, price levels for cement cannot be expected to increase much due to high unutilized capacity far in excess of demand likely to prevail in 2012 and 2013. However, it should be noted that additional cement capacity of 20 million mtpa is being implemented and will be commissioned in 2012. If sufficient demand exists, a capacity utilisation of more than 85 percent is easily achievable. The weak economic climate will also have an impact on smaller cement producers and their operations, leading to a spate of consolidations. Concurring on this issue, Nambiar reiterated, "presently, 35 percent of the cement production capacity is in the hands of smaller producers for whom the future will be one of tribulation due to unfavourable economic conditions. The next two years will see a period of consolidation in the industry with the smaller players withdrawing from the industry by selling out to the financially stronger cement producers. Their share of the total cement capacity can be expected to increase to over 70 percent by 2014."Being a huge country, there will be a difference in the region wise demand for cement in the country which is broadly divided into the western, eastern, northern and southern regions. Elaborating on this aspect, Sumit Banerjee, Vice Chairman, Reliance Cementation stated, "demand for cement in the South is expected to go southward by 4 percent in FY2011-12, display lower than average growth at 5 percent in FY2012-13 and bounce back sharply in FY2013-14. A rise in growth will be witnessed by the Eastern and Central regions from the lower than average levels of 6 percent in FY2011-12 to 9 percent in FY2013-14. Demand for cement in the Northern region is expected to remain in the range of 7-9 percent while the Western region will show demand in the 10 percent range till FY2013-14."Reiterating on the capacity utilization differentials across different regions, Banerjee stated, "a moderation is expected to set in the average industry capacity utilization rate to 76 percent in FY2012-13 from 79 percent in FGY2010-11 before showing an upward curve to 79 percent in FY2013-14. The highest capacity utilization rates are likely to be witnessed by the Eastern and Northern regions at 90 percent levels in FY2012-13 while higher capacity additions could lead to a fall in capacity utilizations in Central India. Utilization rates are also likely to be impacted in the Western region due to pressure exerted on account of cement supply from Southern India."The industry is also optimistic that demand for cement will surge in the near future through the revival of economic activity by the government especially through investment in infrastructure projects. Expressing confidence that the government will initiate the demand push process, Umesh Shrivastav, Executive Chairman, Holtec Consulting Private Limited stated, "following the slump of 2011, demand for cement is likely to see a recovery process and will touch levels of 6-8 percent in 2012. The increase in growth will be triggered by the government’s drive to revive economic activity by initiating investment in infrastructure projects. A correction is foreseen in interest rates and improved regulation as regards land acquisition and environmental clearance leading to revival of several on-hold projects. Cement prices are likely to maintain an upward curve due to increasing production and ownership costs alongwith lower capacity utilizations."Challenges & Opportunities for Indian Cement Industry during 2012 onwards:The forthcoming year 2012 for the Cement Industry is likely to see more of consolidation but lower growth rate. The challenges and opportunities may be summarized as follows:??Extraordinary delay in mining lease sanction and delay in land acquisition & MoEF clearance.??Non availability of domestic coal clubbed with poor quality. Hence, industry has to depend upon high cost imported coal. ??Depreciation of Indian currency has further increased the cost of imported coal, Fuel, Gypsum & other raw materials.??Continuous hike in power tariff, due to increase in coal cost & cross subsidy. Though captive power plant appear to be a part solution, but CPP is again depending upon coal supply linkage, which is uncertain.??On top of it, total taxation including excise, VAT, royalty and cross subsidy amounts to approx. 39 – 40% of Ex-works sales realization. Cement being mass consuming item, such high taxation needs re-visit.??Low packing rate and low level of dispatches leading to IR – Labor issues as per the applicable rules & norms of wage board.??Cement Plant being a capital intensive unit, high interest cost is another disincentive for fresh investment in the sector.??Reduced spending on Government Projects and Slow down in infrastructure investment is another cause of worry for fresh investment.Some of the Indian Economy Strong Points & Stimulators relating to Cement Industry??Growing population of currently 1.2 billion with increasing spending power??Government pursuing structural reforms, facilitating pan-Asian trade, increasing FDI inflows??Recent push at Prime Minister’s level for large infrastructure projects such as Highways, Roads, Ports, Railways, Power, Housing, etc. ??Requirement of Accelerated industrialization to cater to infrastructure and consumer markets??India’s economic growth based on reforms and economic liberalization likely to sustain on long term basis.Measures to be implemented for stimulating cement demand:In order to stimulate demand in an already sagging industry, the government needs to initiate certain measures in the form of providing tax incentive to the industry, reduce the overall tax value on the commodity and phase out cross subsidy on supportive components. The government can also consider classifying cement as "Declared Goods" like steel having a uniform VAT rate of 4 percent throughout the country. To throw light on the matter further, P.K.Ghosh, Chairman, Ercom Engineers Pvt Ltd Ercom Group said, "the overall taxation value on cement can be brought down to a level of 20-25 percent of ex-works selling price from the current level. Tax incentive should be provided by the government for promoting blended cement in the larger interest of mineral conservation, waste utilization and bringing down carbon emission. Cross subsidy burden on electricity, diesel and railway freight should be phased out in a gradual manner. The supply of superior quality coal should be increased through merchant mining in private sector. Companies who have been allotted captive coal blocks should be asked to increase production for selling in the open market."Cement manufacturers need to maximize production of blended cement by utilizing industrial waste like fly ash and slag for conserving mineral resources. The current average blending ratio in the country is pegged at approximately 27 percent which needs to be increased to 40 percent over the next 4-5 years. High energy consuming old and inefficient equipment needs to be replaced with modern equipment for optimizing and minimizing energy consumption alongwith increasing capacity. The industry needs to adopt the latest technology for Green Cement grinding for reducing clinker consumption and deriving benefits of carbon credits. Ready Mix Concrete (RMC) business may be promoted by cement companies or small companies should be encouraged to undertake RMC business at various locations, leading to bulk supply of cement and consequent reduction in packaging cost.ConclusionIn a nutshell, the government needs to support the cement industry in reviving its fortune through initiatives like reducing tax burden, providing incentives and ensuring availability of superior quality coal.
You may like
Economy & Market
Leonard Unveils Dual-Head Robotic Arm for Hazardous Industrial Demolition
Published
5 days agoon
October 30, 2026By
admin
Leonard unveils Descender Duo, a dual-head robotic demolition arm designed to improve industrial safety and reduce shutdown time by up to 50 per cent.
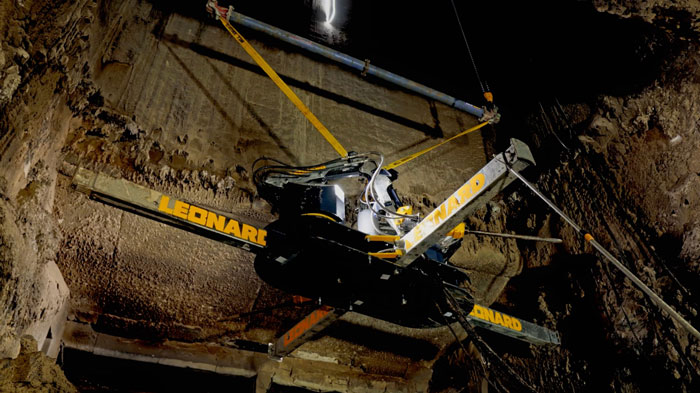
Industrial robotics and refractory services specialist Leonard has launched Descender Duo, a dual-head robotic demolition arm designed to improve safety, accelerate maintenance and reduce shutdown times in hazardous industrial environments. The system made its debut at Lisahally Power Station in Northern Ireland, removing 25 tonnes of slag material within hours.
Developed for the cement, metals, waste-to-energy and petrochemical industries, Descender Duo enables remote-controlled refractory demolition, anchor cutting and welding, and refractory spraying inside boilers, calciners and silos. Its vertical-access design eliminates the need for personnel to enter confined, high-risk spaces during these operations.
Weighing less than two tonnes, the pre-assembled system requires an access opening of just 1.2 m². Supported by an external overhead hoist, it uses electrically operated hydraulic stabilising legs to secure itself inside vessels. The robotic arm offers 360-degree rotation and is suited to vessels approximately 9 m in diameter, with its operating reach extendable through strategically positioned access points.
Equipped with two independently controlled robotic heads, Descender Duo can perform identical or different tasks simultaneously, including refractory demolition, anchor cutting and spraying. Its remote-control system incorporates live camera feeds, allowing operators to monitor operations without entering hazardous environments.
According to Leonard, the technology can deliver time savings of up to 50 per cent compared with manual methods. Its ability to operate at temperatures exceeding 100°C allows maintenance to begin as early as 24 hours after burner shutdown. An all-electric power supply further supports cleaner and more cost-efficient operations.
First Deployment Demonstrates Shutdown Efficiency
The system was first deployed at Burmeister & Wain Scandinavian Contractor’s (BWSC) Lisahally Power Station in Londonderry, Northern Ireland. The facility generates electricity from grade C waste wood, supplying approximately 40,000 homes and businesses.
Leonard and BWSC collaborated to develop a customised solution for the plant’s 26-metre furnace, where extensive external pipework created significant access challenges.
Mark Leonard, Managing Director, Leonard, said, “It required new thinking and rather than step away from the problem we were committed to solving it for the customer, with the customer. We’re relentless in our approach to tackling complex challenges, head-on. We took our years of cement plant experience, coupled with our working knowledge of the BWSC plant, and designed, engineered and tested a completely new vertical solution within just seven weeks from that initial conversation with the customer. That solution was the Descender Duo as we know it today.”
Traditionally, the furnace required a cooling period of up to 36 hours before preparatory work could begin, followed by manual slag removal using rope-access personnel. With Descender Duo, work commenced just 24 hours after shutdown, reducing downtime by up to one day.
The deployment removed 25 tonnes of slag within hours, eliminated the need for at least six workers to enter the hazardous furnace interior and saved 26 hours in the shutdown programme.
“The effectiveness exceeded expectation,” said Martin Doran, Plant Manager at Lisahally Power Station.
“When the Descender Duo concept was first discussed, we had to spend some time with the team from Leonard looking at how it was going to be moved into the furnace. Every site is different and that presented its own challenges, but nothing that the team couldn’t overcome. Once it was installed we were hugely impressed by its efficiency.”
Expanding Industrial Robotics Applications
Descender Duo joins Leonard’s existing portfolio of robotic maintenance solutions, including the Axis horizontal-access arm, Nano confined-space access arm, Charger cement mill media recharging system and Calibre cement mill media grading system.
Headquartered in Northern Ireland, Leonard provides robotic refractory demolition, installation, inspection and industrial maintenance services across the cement, metals, energy, biomass, glass and civil engineering sectors.
Formerly known as G Leonard, the company has more than 35 years of industry experience and operates across Europe, North America, the Middle East, Africa and Asia-Pacific.
The latest innovation reinforces Leonard’s focus on replacing hazardous manual processes with robotic systems that improve workforce safety, enhance operational efficiency and minimise industrial downtime.
Concrete
Martin Engineering Appoints Ashwini Khunte as India General Manager
Published
5 days agoon
October 30, 2026By
admin
Martin Engineering names Ashwini Khunte India General Manager to strengthen operations and drive growth across key bulk material handling sectors.
Pune
Martin Engineering, a global provider of bulk material handling solutions, has appointed Ashwini Khunte as General Manager of its India business, strengthening its leadership as the company expands its presence across the country’s cement, mining, steel, power and infrastructure sectors.
Khunte brings more than a decade of experience with Martin Engineering, having joined its Indian operations in 2013 as a Design Engineer, shortly after the company established its presence in the country in 2012.
A mechanical engineer by qualification, she spent her initial five years developing bulk material handling solutions in collaboration with the company’s operations team. During this period, she gained extensive experience addressing operational challenges in the steel, cement and coal industries. She subsequently moved into project engineering, managing major engineering, procurement and construction (EPC) and original equipment manufacturer (OEM) projects from initial enquiry to commissioning. Her responsibilities later expanded to overseeing Martin Engineering’s conveyor product portfolio in India, involving customer engagement, technical presentations and site visits across heavy industries.
In 2024, Khunte was promoted to Head of Sales & Marketing for the company’s Europe, Middle East, Africa and India (EMEAI) region. The position broadened her international market exposure and strengthened her strategic and commercial leadership capabilities.
Commenting on her appointment, Ashwini Khunte, General Manager, Martin Engineering India, said: “India represents a tremendous opportunity for Martin Engineering. The country’s continued investment in cement, mining, steel, power and infrastructure is creating increasing demand for safer, cleaner and more productive bulk material handling, and that’s exactly what we do. My priority will be to build on the strong foundations already established in India, while continuing to develop our people, strengthen customer relationships and bring practical solutions to the challenges faced by our industry.”
Robert Whetstone, Area Vice President – EMEAI, Martin Engineering, highlighted Khunte’s technical expertise, market understanding and leadership experience.
“Ashwini brings an exceptional combination of technical understanding, customer knowledge and commercial leadership. She has grown as Martin Engineering has grown, and has consistently demonstrated outstanding capability to transform her expertise into practical solutions. Her knowledge of the Indian market, together with her international experience, makes her ideally suited to lead our India business through its next stage of growth for years to come.”
Since establishing its Indian business in 2012, Martin Engineering has expanded its local workforce, manufacturing capabilities and dealership network. The company supplies conveyor products, transfer point solutions, material flow aids, training and technical support to bulk material handling industries. Khunte’s appointment positions the company to further strengthen customer relationships and expand its solutions portfolio in India’s growing industrial and infrastructure markets.
Concrete
Fornnax Wins AIRIA’s Special Export Award for Rubber Machinery in 2025-26
Published
2 weeks agoon
October 19, 2026By
admin
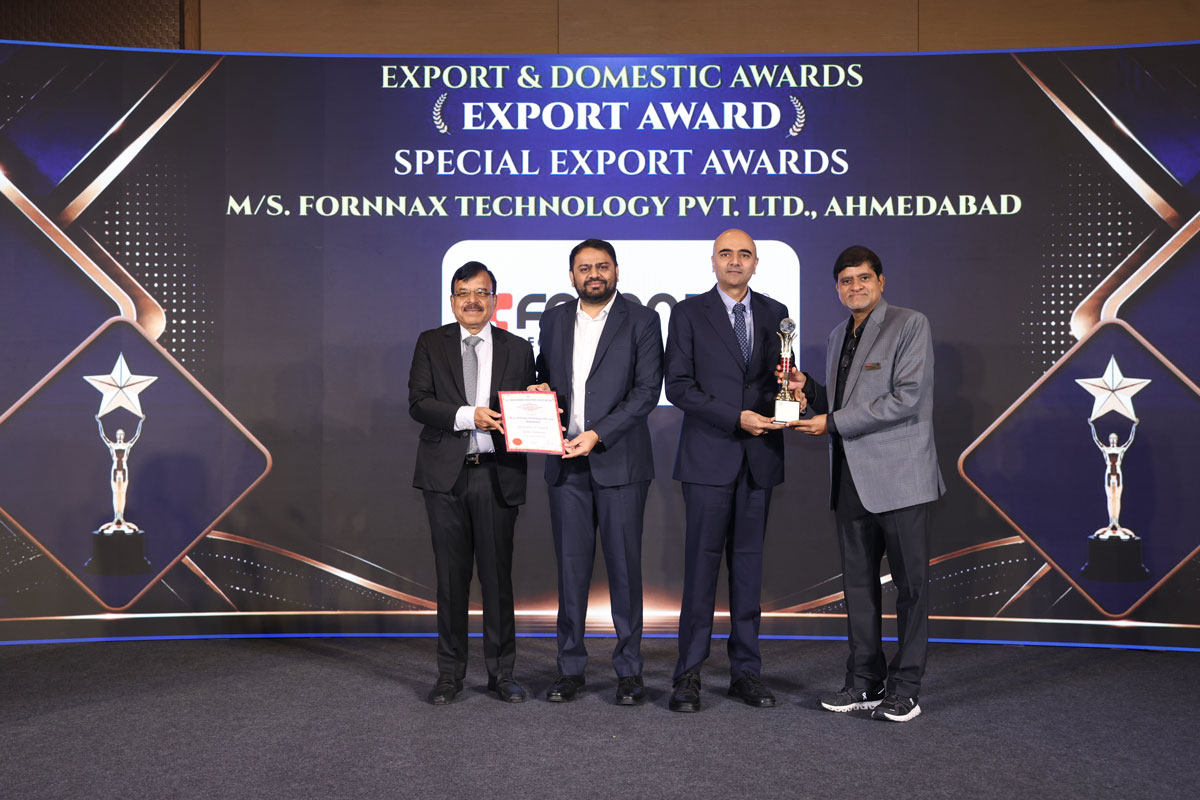
Fornnax Technology Pvt. Ltd. has been honoured with the Special Export Award – Rubber Machinery for 2025–26 by the All-India Rubber Industries Association (AIRIA), in recognition of its highest exports of tyre recycling plants to the European region.
With more than a decade of experience in India’s tyre recycling industry, Fornnax has contributed to the development of advanced recycling technologies and infrastructure. The company currently holds a 90% market share in India’s domestic tyre recycling sector, while exports account for 30% of its business, spanning markets such as Europe, Australia and the GCC.
The award marks another milestone for Fornnax, whose tyre recycling lines and advanced shredding technologies are supporting the growth of the circular economy in India and international markets.
Commenting on the recognition, Mr. Jignesh Kundaria, Founder and Director of Fornnax, said:
“This honour from AIRIA is a reflection of an incredible journey we have undertaken over the years. When we started Fornnax, there was no established recycling industry in India to follow. We chose to build for the future instead. Today, when you see India’s tyre recycling sector, it has already transformed into a dynamic, high-growth industry and we are extremely proud to have played our part in building it.”
Unlike standalone equipment suppliers, Fornnax focuses on developing complete, high-capacity recycling infrastructure. Its integrated systems combine multiple stages of shredding and size reduction to enable efficient, continuous operations. This system-level engineering approach helps recycling operators improve throughput, equipment reliability and operational consistency.
The recognition reinforces Fornnax’s commitment to developing engineering technologies that contribute to a more efficient and circular recycling ecosystem.
Looking ahead, the company aims to expand its international presence while continuing to develop advanced shredding and recycling solutions to address the growing volumes and evolving requirements of the global recycling industry.
For more information, visit: www.fornnax.com
India’s Cement Sector Cuts Energy Use, but Worker Safety Worsens
Ambuja Cements Expects Volume Growth to Outpace Industry in H2
JK Lakshmi Cement Begins Rs 110 Billion Assam Plant Project
Leonard Unveils Dual-Head Robotic Arm for Hazardous Industrial Demolition
JK Lakshmi Cement to Expand EV Fleet to 120 Vehicles by March 2027
India’s Cement Sector Cuts Energy Use, but Worker Safety Worsens
Ambuja Cements Expects Volume Growth to Outpace Industry in H2
JK Lakshmi Cement Begins Rs 110 Billion Assam Plant Project
Leonard Unveils Dual-Head Robotic Arm for Hazardous Industrial Demolition
JK Lakshmi Cement to Expand EV Fleet to 120 Vehicles by March 2027
Trending News
-
Concrete4 weeks agoShiva Cement Merges with JSW Cement
-
Concrete4 weeks agoJSW Cement Boards Approve Proposed Shiva Cement Merger
-
Concrete4 weeks agoUltraTech becomes first Indian cement firm to cross 2 GW green energy
-
Concrete4 weeks agoJSW Cement commissions additional 1 MTPA grinding unit at Nagaur