Connect with us

Economy & Market

CCUS has not yet reached commercial integration

Published

on

Shares

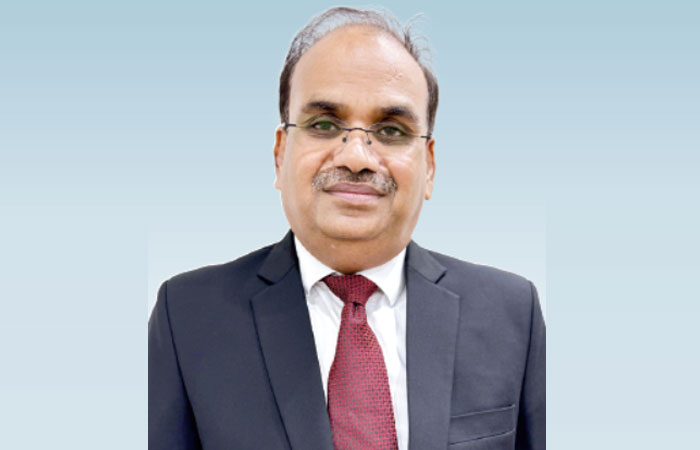
MM Rathi, Joint President – Power Plants, Shree Cement, suggests CCUS is the indispensable final lever for cement decarbonisation in India, moving from pilot-stage today to a policy-driven necessity.

In this interview, MM Rathi, Joint President – Power Plants, Shree Cement, offers a candid view on India’s CCUS readiness, the economic and technical challenges of integration, and why policy support and cluster-based infrastructure will be decisive in taking CCUS from pilot stage to commercial reality.

How critical is CCUS to achieving deep decarbonisation in cement compared to other levers?
CCUS is critical and ultimately indispensable for deep decarbonisation in cement. Around 60 per cent to 65 per cent of cement emissions arise from limestone calcination, an inherent chemical process that cannot be addressed through energy efficiency, renewables, or alternative fuels. Clinker substitution using fly ash, slag, and calcined clay can reduce emissions by 20 per cent to 40 per cent, while energy transition measures can abate 30 per cent to 40 per cent of fuel-related emissions. These are cost-effective, scalable, and form the foundation of decarbonisation efforts.
However, these levers alone cannot deliver reductions beyond 60 per cent. Once they reach technical and regional limits, CCUS becomes the only viable pathway to address residual
process emissions. In that sense, CCUS is not an alternative but the final, non-negotiable step toward net-zero cement.

What stage of CCUS readiness is the Indian cement sector currently at?
The Indian cement sector is currently at a pilot to early demonstration stage of CCUS readiness. A few companies have initiated small-scale pilots focused on capturing CO2 from kiln flue gases and exploring utilisation routes such as mineralisation and concrete curing. CCUS has not yet reached commercial integration due to high capture costs (US$ 80–150 per tonne of CO2), lack of transport and storage infrastructure, limited access to storage sites, and absence of long-term policy incentives.
While Europe and North America have begun early commercial deployment, large-scale CCUS adoption in India is more realistically expected post-2035, subject to enabling infrastructure and policy frameworks.

What are the biggest technical challenges of integrating CCUS into existing Indian kilns?
Retrofitting CCUS into existing Indian cement plants presents multiple challenges. Many plants have compact layouts with limited space for capture units, compressors, and CO2 handling systems, requiring modular and carefully phased integration.
Kiln flue gases contain high CO2 concentrations along with dust and impurities, increasing risks of fouling and corrosion and necessitating robust gas pre-treatment. Amine-based capture systems also require significant thermal energy, and improper heat integration can affect clinker output, making waste heat recovery critical.
Additional challenges include higher power and water demand, pressure drops in the gas path, and maintaining kiln stability and product quality. Without careful design, CCUS can impact productivity and reliability.

How does the high cost of CCUS impact cement pricing, and who bears the cost?
At capture costs of US$ 80-150 per tonne of CO2, CCUS can increase cement production costs by US$ 30-60 per tonne, potentially raising cement prices by 20 to 40 per cent. Initially, producers absorb the capital and operating costs, which can compress margins. Over time, without policy support, these costs are likely to be passed on to consumers, affecting affordability in a highly price-sensitive market like India. Policy mechanisms such as subsidies, tax credits, carbon markets, and green finance can significantly reduce this burden and enable cost-sharing across producers, policymakers, and end users.

What role can carbon utilisation play versus geological storage in India?
Carbon utilisation can play a supportive and transitional role, particularly in early CCUS deployment. Applications such as concrete curing and mineralisation can reuse 5 to 10 per cent of captured CO2 while improving material performance. Fuels and chemicals offer niche opportunities but depend on access to low-cost renewable energy. However, utilisation pathways are limited in scale and often involve temporary carbon storage. With India’s cement sector emitting over 200 million tonnes of CO2 annually, utilisation alone cannot deliver deep decarbonisation.
Long-term geological storage offers permanent sequestration at scale. India has significant potential in deep saline aquifers and depleted oil and gas fields, which will be essential for achieving net-zero cement production.

How important is government policy support for CCUS viability?
Government policy support is central to making CCUS commercially viable in India. Without intervention, CCUS costs remain prohibitive and adoption will remain limited to pilots.
Carbon markets can provide recurring revenue streams, while capital subsidies, tax incentives, and concessional financing can reduce upfront risk. Regulatory mandates and green public procurement can further accelerate adoption by creating predictable demand for low-carbon cement. CCUS will not scale through market forces alone; policy design will determine its pace and extent of deployment.

Can CCUS be scaled across mid-sized and older plants?
In the near term, CCUS is most viable for large, modern integrated plants due to economies of scale, better layout flexibility, and access to waste heat recovery. Mid-sized plants may adopt CCUS selectively over time through modular systems and shared CO2 infrastructure, though retrofit costs can be 30 to 50 per cent higher. For older plants nearing the end of their operational life, CCUS retrofitting is generally not economical, and decarbonisation efforts are better focused on efficiency, fuels, and clinker substitution.

Will CCUS become a competitive advantage or a regulatory necessity?
Over the next decade, CCUS is expected to shift from a competitive advantage to a regulatory necessity. In the short term, early adopters can access green finance, premium procurement opportunities, and sustainability leadership positioning. Beyond 2035, as emissions regulations tighten, CCUS will become essential for addressing process emissions. By 2050, it is likely to be a mandatory component of the cement sector’s net-zero pathway rather than a strategic choice.

– Kanika Mathur

Concrete

Wonder Cement appoints Mahesh Singh as VP Corporate Brand Communication 

Published

on

By

Shares

Singh brings 20+ years of brand and marketing experience, and will lead integrated corporate brand communication initiatives at Wonder Cement 

New Delhi

Wonder Cement, a leading cement manufacturer, has appointed Mahesh Singh as Vice President – Corporate Brand Communication. In his new role, he will oversee corporate brand strategy and communication, including digital and performance marketing, public relations, trade, events, exhibitions, sports and experiential marketing. 

Singh brings over two decades of experience across marketing and communications, with roles spanning the automotive industry, agencies and entrepreneurship. He spent more than a decade with Honda Motorcycle & Scooter India, working across integrated communication, media, digital, retail and consumer engagement. His stint also included helping build the company’s digital marketing capabilities. 

He moved to dentsu X India as Vice President – Strategy & Planning, working across categories such as automotive, auto components, electric vehicles, FMCG, consumer electronics, BFSI, apparel and brand consulting. His responsibilities included media and marketing strategy, product launches, content, performance marketing and consumer activations. 

Singh subsequently took an entrepreneurial route with Radiant Brands before joining Shriram Ltd (SPR Autotech) as Head – Marketing & Communications. There, his remit included brand and corporate strategy, communications, PR and ORM, retail identity, loyalty programmes and events. 

At Wonder Cement, Singh will be responsible for bringing together the company’s corporate brand communication initiatives across digital, performance marketing, PR, trade, sports and experiential platforms. The role will focus on creating an integrated approach to communication across consumers, trade partners and other key stakeholders. 

The appointment brings to Wonder Cement a marketer whose career has spanned the brand, agency and entrepreneurial sides of the communications ecosystem. 

Wonder Cement, part of the RK Group, is a cement manufacturer with roots in Rajasthan and a focus on quality, trust and transparency. The company has grown to six manufacturing plants, and a cement capacity of 21.5 MTPA. With more than 2,000 employees and a network of over 5,000 dealers, its operations span manufacturing, distribution and customer engagement, with a focus on consistent product quality and efficient execution. 

Continue Reading

Concrete

JSW Cement commissions additional 1 MTPA grinding unit at Nagaur

Published

on

By

Shares

With this commissioning, JSW Cement’s total cement grinding capacity has increased to 25.10 MTPA, 
Mumbai

JSW Cement, one of India’s leading green cement producers and part of the diversified JSW Group, today announced the successful commissioning of an additional 1.00 MTPA cement grinding unit at Nagaur, Rajasthan. The commissioning marks another significant milestone in the Company’s growth strategy.

With this commissioning, JSW Cement’s total cement grinding capacity has increased to 25.10 MTPA, while its total clinker manufacturing capacity, including clinker capacity at its joint venture, JSW Cement FZC, stands at 9.74 MTPA.

JSW Cement had commenced operations in North India in March 2026 with the Nagaur Integrated Plant, comprising a 3.30 MTPA clinkerisation unit and 2.50 MTPA cement grinding unit. With the commissioning of the additional 1.00 MTPA cement grinding unit, the plant’s total cement grinding capacity has increased to 3.50 MTPA, enhancing the company’s ability to cater to the growing cement demand across Rajasthan, Haryana, Punjab and the National Capital Region (NCR). The expansion has been funded through a strategic mix of equity and long-term debt.

During the quarter ended 30th September 2026, JSW Cement has also commissioned the Alternate Fuel Handling System and the Waste Heat Recovery system (WHRS) at the Nagaur Integrated Plant.

Nilesh Narwekar, CEO, JSW Cement, said: “The commissioning of additional 1.00 MTPA grinding capacity at Nagaur is a key strategic priority for us and will accelerate JSW Cement’s expansion into North India. We look forward to servicing the growing needs of the region and contributing to the economic growth of Rajasthan, Haryana, Punjab and the NCR area. I am delighted to share that the company has commissioned this grinding unit within the expected timeline, showcasing our project execution capabilities. Further, the Alternate Fuel Handling System and the Waste Heat Recovery system (WHRS) are expected to substantially reduce our production costs going forward.”

Continue Reading

Concrete

UltraTech becomes first Indian cement firm to cross 2 GW green energy

Published

on

By

Shares

UltraTech Cement has crossed 2 GW of captive green energy capacity, with renewables and waste heat recovery meeting 48 per cent of its power needs.

Mumbai

UltraTech Cement Limited has surpassed 2 GW of installed green energy capacity for captive use, becoming the first cement company in India to achieve the milestone. The Aditya Birla Group company commissioned 116.55 MW of wind capacity at its Inter-State Transmission System-connected wind-solar hybrid project in Barmer, Rajasthan, along with 10 MW of Waste Heat Recovery System capacity at Sarlanagar Cement Works in Karnataka.

With these additions, UltraTech’s cumulative installed green energy capacity has reached 2,024 MW. This includes 1,580 MW of renewable energy capacity and 444 MW of waste heat recovery capacity, together meeting around 48 per cent of the company’s current power requirements.

The company said the milestone reflects the progress of its long-term energy transition strategy. In FY27 so far, nearly one-third of UltraTech’s 76 manufacturing units in India have maintained green energy utilisation above 50 per cent of their electricity requirements, while five units have crossed 95 per cent.

K C Jhanwar, Managing Director, UltraTech Cement Limited, said, “Crossing the 2 GW green energy milestone is the result of a strategy we have pursued consistently over the past decade. Cement is an energy-intensive, hard-to-abate sector, and showing that reliability and growth can go hand in hand with a rapid shift to green energy sets a benchmark for the industry. With nearly half of our power needs now met through green energy, we are significantly less exposed to fossil fuel supply constraints and power price volatility. As we scale up renewables, waste heat recovery and battery storage across our operations, we are building an energy foundation for stable, long-term growth.”

UltraTech commissioned 430 MW of green energy capacity in FY26 and continues to expand its renewable energy and waste heat recovery portfolio.

The company is also progressively integrating Battery Energy Storage Systems across its operations to improve renewable energy utilisation and supply reliability.

In 2025, UltraTech operationalised what it described as India’s first on-site hybrid round-the-clock renewable energy project at Sewagram Cement Works in Gujarat. The project combines solar, wind and battery storage.

As part of its decarbonisation strategy, UltraTech said it has not invested in new captive thermal power capacity for either greenfield projects or brownfield expansions at its integrated units for more than a decade.

The company said its expanding green energy portfolio is helping reduce dependence on conventional grid electricity and fossil fuel-based power, while lowering exposure to fluctuations in coal and electricity prices.

UltraTech aims to increase green energy’s share in its total power mix to 85 per cent by 2030. As a member of RE100, it has also committed to meeting 100 per cent of its electricity requirement through renewable sources by 2050.

UltraTech Cement, the cement flagship of the Aditya Birla Group, has a total grey cement capacity of 210.1 MTPA and white cement and putty capacity of 3.5 MTPA. The company is also a signatory to the GCCA Climate Ambition 2050 and has committed to the GCCA Net Zero Concrete roadmap.

Continue Reading

Video Thumbnail
▶

    SIGN-UP FOR OUR GENERAL NEWSLETTER

    Trending News

    SUBSCRIBE TO THE NEWSLETTER


    Don't miss out on valuable insights and opportunities to connect with like minded professionals.


      This will close in 0 seconds