Connect with us

Concrete

The future shall demand less energy intensive greener cements

Published

on

Shares

Dr Sujit Ghosh, Executive Director – New Product and R&D, Dalmia Cement (Bharat), discusses the alternative raw materials that can be used in the production of cement and its impact on carbon emissions while underscoring the major challenges faced in using other cementitious materials.

What are the core raw materials used in the production of cement?

The core raw materials used in the production of cement are limestone (calcium carbonate) and clay (a source of silica). First, the limestone is roasted/calcined to create activated lime (CaO) in a calciner and then the activated lime along with siliceous clay is proportioned along with some other minor ingredients into a raw mix design and charged inside a kiln to form cement clinker; which is basically made of complex compounds of calcium-silica-oxides primarily, which when mixed with water, reacts, to form a cementitious gel paste that binds all aggregates together and when dried up provides strength to the concrete/plaster, made with cement and the aggregates.

Limestone (calcium carbonate) and clay (silica), which are both available in nature, are inert materials. Only when they are heat-treated at temperatures above 900oC, they become activated lime (CaO) and activated/amorphous silica (SiO2), and fuse inside the cement kiln in liquid form to form complex calcium-silica-oxides, that is cement or cement clinker.

What are the alternative raw materials that can be used in the production of cement? How does that impact the process of production? 

As explained in the previous paragraph, any activated lime (CaO) and/or activated/amorphous silica (SiO2), could be potential sources of cementitious material.  These could be alternative raw materials for cement production. Thus far, the most widely found and used sources of alternative materials are primarily ‘fly ash’ and ‘blast furnace slag’. Fly ash is a waste product from the burning of coal (as in a thermal power plant etc). It primarily contains amorphous/activated silica (SiO2), but very little active lime (CaO) in the Indian context. So, it is not reactive on its own, it needs activated lime (CaO) to become cementitious – which is available from cement clinker, when the two are co-processed in a cement manufacturing plant. Blast furnace slag likewise is a waste product from the steel manufacturing process and does contain some activated silica and activated lime, but again, not in the proportion/concentration to itself become cementitious. It also has to be co-processed with a cement clinker in a cement manufacturing plant. Overall, these alternative or supplementary cementitious materials, which are other industry wastes, due to the need for co-processing with cement clinker, may add some costs to the production process, but since the use of such alternative raw materials, reduces the dependence on highly energy-intensive clinker, they are welcome by the cement manufacturing fraternity, that helps lower the carbon footprint of production. These cements are called ‘blended cements’ – either fly ash blended (popularly known as PPC) or slag blended (popularly known as PSC) or fly ash + slag blended (popularly known as PCC).

How can the cost of production be reduced by using alternative or supplementary raw materials in cement production?

Since the use of alternative / supplementary cementitious materials has been prevalent in the world and in India, for blended cement production, for the last couple of decades, the demand for such other industry wastes (primarily from thermal power plant or steel plant) has been increasing steadily. This has led to a steep increase in prices for these industry wastes (mainly slags from steel plants) which otherwise were previously dumped in landfills, by opportunistic players and profiteering groups. Also, since steel plants and thermal power plants are not co-located with cement plants geographically, transportation costs of such bulky waste materials have also been increasing. Cost of blended cement production has to reduce or at least maintain at par, as well as, at the same time assist the nation in beneficially getting rid of other-industry-wastes. Cement players can do justice to climate-change by producing less energy intensive blended cements that are in no way inferior in quality to pure-clinker cements. Transport subsidies should also be provided to cement manufacturers by the government as well as at the same time try and administer some polluter-to-pay mechanism (so that these wastes are not conveniently dumped away in nearby landfills by the relevant industries).

Kanika Mathur

Click here to read more

Concrete

Cement Firms to Invest Rs. 130 bn in Green Energy by FY28

Cement companies plan to expand clean energy capacity to 6 GW by FY28
Published

on

By

Shares


India’s major cement companies are set to raise their clean energy capacity to 6 GW by March 2028 from around 4 GW at the end of March 2026, according to ratings agency ICRA. The planned expansion is expected to involve investments of Rs. 130 bn over the next two years.

The additional capacity could generate annual savings of Rs. 62 bn to Rs. 67 bn, resulting in an estimated payback period of 1.8 to 2.2 years. Cement is an emission-intensive industry, and leading producers have established net-zero roadmaps covering the next 15 to 20 years.

The calcination process accounts for 57 to 60 per cent of the sector’s total emissions, while fuel combustion contributes 27 to 30 per cent and electricity consumption accounts for 10 to 13 per cent. ICRA said the figures highlighted the need for a broad decarbonisation strategy involving green power, blended cement, alternative fuels and improvements in clinker efficiency.

Green energy is considered one of the most commercially attractive decarbonisation options because it can reduce emissions while lowering operating costs. Every 5 per cent increase in green power replacement can reduce power and fuel costs by Rs. 15 to Rs. 16 per tonne. A 25 per cent replacement level could therefore save Rs. 75 to Rs. 80 per tonne and expand operating margins by 140 to 160 basis points.

Cement producers are also assessing carbon capture, utilisation and storage, although high implementation costs, energy requirements and limited transport and storage infrastructure are expected to slow commercial adoption. The government has proposed Rs. 200 bn over five years to support deployment across key sectors. Meanwhile, companies are targeting thermal substitution rates of 10 to 15 per cent over the next three to five years, compared with the current industry level of around 6 per cent.

Continue Reading

Concrete

Centre Defers Clearance for Limestone Mine Near Bustard Habitat

Panel seeks revised mining plan and safeguards for pipelines and wildlife
Published

on

By

Shares


The Centre has deferred environmental clearance for a proposed limestone mine near a Great Indian Bustard habitat in Ramgarh, Rajasthan’s Jaisalmer district. The critically endangered species has an estimated wild population of about 130 in India.

Continue Reading

Concrete

Telangana to Supply Subsidised Cement for Indiramma Houses

Poor families allotted Indiramma houses to receive cement at Rs. 230 per bag
Published

on

By

Shares


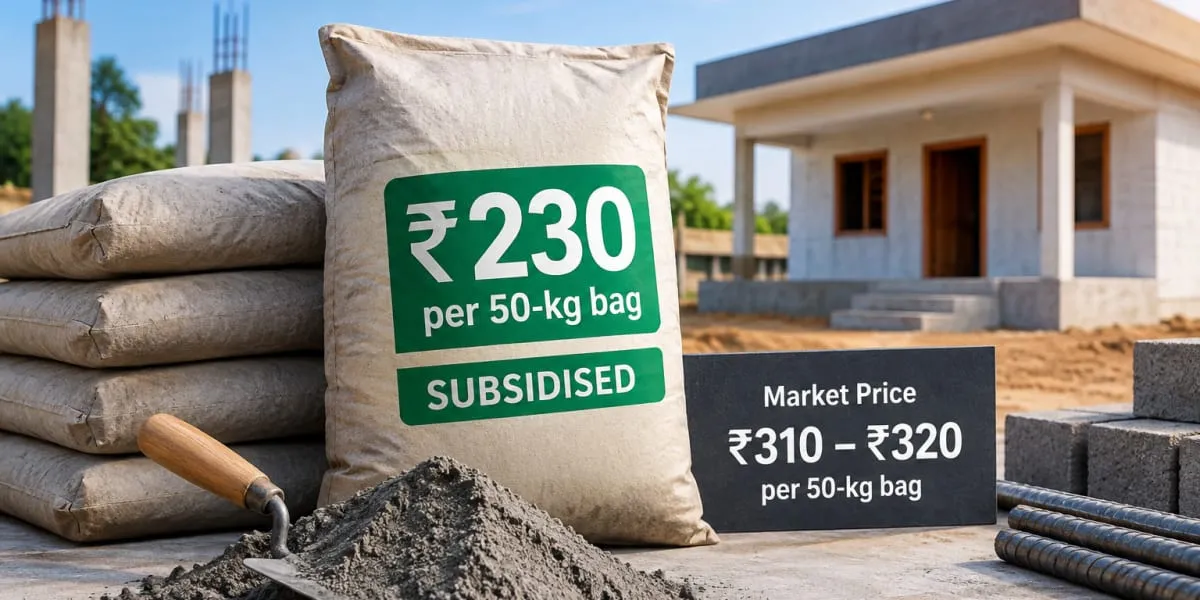
The Telangana government will supply cement at a subsidised price of Rs. 230 per 50-kg bag to poor and low-income families allotted Indiramma houses. The prevailing market price is between Rs. 310 and Rs. 320 per bag, the Assembly was informed on Thursday.

Continue Reading

Video Thumbnail

    SIGN-UP FOR OUR GENERAL NEWSLETTER

    Trending News