ICR deep dives into the cement industry’s value chain for alternative fuel and raw materials (AFR). It examines the economics of municipal solid waste segregation and biomass aggregation as well as advanced pre-processing, AI-driven kiln optimisation and the regulatory reforms needed to transform the sector into a circular economy anchor.
Alternative fuels and raw materials (AFR) are becoming central to cement decarbonisation because they address two of the industry’s most significant challenges: dependence on carbon-intensive fossil fuels and the extensive use of virgin mineral resources. Cement production is responsible for approximately 6 to 7 per cent of India’s greenhouse gas emissions, with limestone calcination accounting for about 56 per cent of sectoral emissions, fuel combustion 32 per cent and electricity use the remaining 12 per cent, according to the American Council for an Energy Efficient Economy. Replacing coal and pet coke with biomass, refuse derived fuel and other waste derived fuels can therefore directly reduce fossil fuel consumption, while the use of fly ash, slag, calcined clay and other supplementary materials can lower the clinker factor and conserve virgin resources. India has already made significant progress through blended cement, with PPC and PSC accounting for around 72 per cent of total cement output and the clinker to cement ratio declining to 0.67 by 2024, compared with a global average of 0.76, according to NITI Aayog.
However, substantial potential remains: only about 6 per cent of the thermal energy used in Indian cement kilns currently comes from alternative fuels, while recent decarbonisation pathways suggest raising the thermal substitution rate to 15 per cent to 20 per cent by 2030. AFR, thus, represents more than a fuel or material substitution strategy; it is a practical pathway towards a circular economy in which industrial and municipal waste can be transformed into productive resources, helping the cement industry reduce emissions, conserve natural resources and move closer to its long-term net zero ambitions.
The growing imperative
The imperative to scale alternative fuels and raw materials is being driven by the convergence of decarbonisation commitments, fuel security, resource constraints and India’s growing waste management challenge. Fossil fuels still account for an estimated 97 per cent of fuel consumption in India’s cement sector, making alternative fuels an important lever for reducing dependence on coal and petcoke, while the NITI Aayog roadmap identifies a 20 per cent thermal substitution rate by 2030 as a key decarbonisation opportunity. The opportunity is reinforced by the availability of waste: India generates around 70 million tonnes of municipal solid waste and 18.5 million tonnes of industrial hazardous waste, creating a substantial potential feedstock
base for co processing, provided waste is properly segregated, processed and converted into consistent kiln suitable fuels.
Saurabh Palsania, Joint President, Shree Cement, says, “The Indian cement industry has significant headroom to increase AFR substitution over the next five years, although the pace will depend on the availability of suitable waste streams, preprocessing infrastructure, supply chain reliability and plant level technology. Agricultural residues, municipal solid waste, industrial waste and other processed waste streams remain significantly underutilised, with agricultural residues offering particularly strong potential as alternative fuels and suitable industrial by products helping reduce dependence on conventional raw materials. The priority should be to achieve sustained, technically viable increases rather than pursue higher substitution at the cost of kiln stability or product quality.”
“The biggest enabler would be organised waste processing and aggregation infrastructure that can provide cement plants with a reliable supply of suitably processed and quality-controlled waste. Many waste streams remain fragmented across locations, making collection, segregation, preprocessing and transportation difficult and supply uncertain. Strengthening these systems would improve supply reliability, make AFR more commercially viable and give cement producers greater confidence to invest, enabling progressively higher substitution rates across the industry,”he adds.
At the same time, alternative raw materials and supplementary cementitious materials can reduce dependence on virgin resources and lower the clinker factor, thereby cutting both process and energy related emissions. The International Energy Agency notes that greater use of alternative fuels and supplementary cementitious materials will be essential to bringing cement emissions in line with net zero pathways. AFR adoption therefore represents a strategic shift towards a circular economy in which waste streams become productive industrial resources, helping cement manufacturers manage fuel costs and supply risks, conserve natural resources and create a more resilient pathway towards long term decarbonisation.
Turning waste into energy
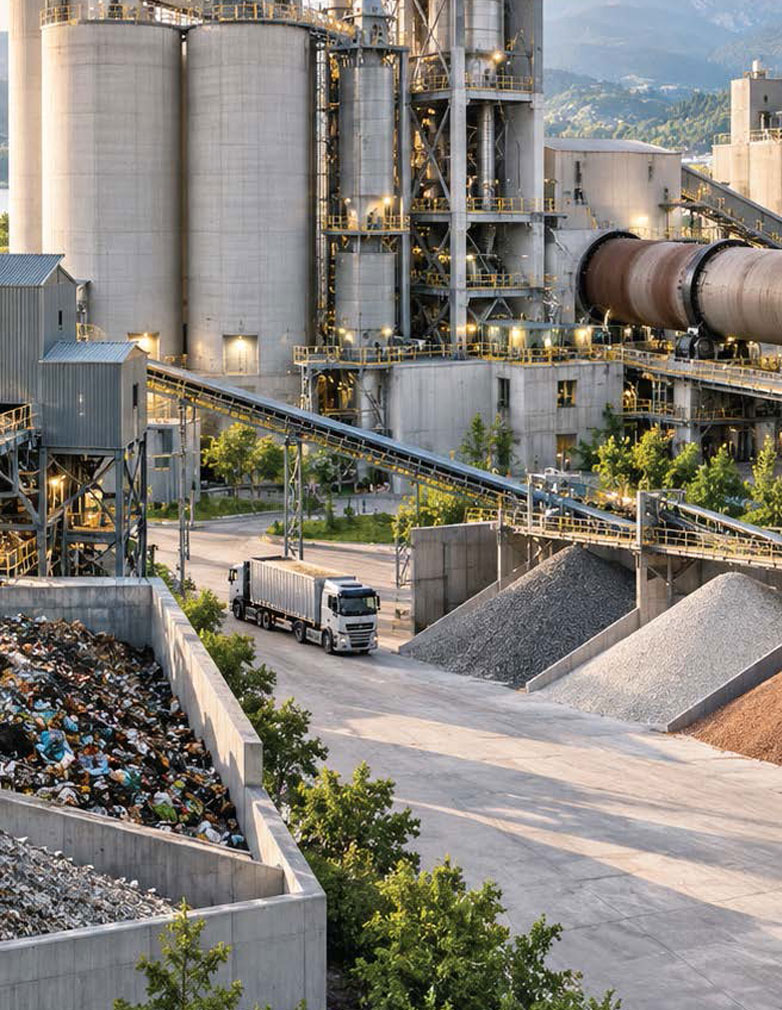
Alternative fuels offer the cement industry an opportunity to convert waste streams into a productive source of thermal energy while reducing dependence on coal and pet coke. Potential feedstocks include refuse derived fuel from municipal solid waste, non-recyclable plastics, industrial and hazardous wastes, used tyres, biomass, agricultural residues, waste oils and sewage sludge, each with different calorific values and processing requirements.
According to the Cement Manufacturers’ Association (CMA), typical calorific values range from 17 to 21 MJ per kg for RDF, 28 to 32 MJ
per kg for waste tyres and 11 to 14 MJ per kg for agricultural residues such as grain straw. India has a substantial resource base, with one assessment identifying 14.5 million tonnes per annum of surplus biomass, 4.5 million tonnes of RDF, 0.65 million tonnes of used tyres and 3.47 million tonnes of plastic waste as potential alternative fuel resources for the cement industry.
Raju Ramchandran, SVP & Head Manufacturing – Eastern Region, Safety and Sustainability, Nuvoco Vistas, says, “A diversified mix of waste-derived fuels and industrial by-products offers significant potential to reduce our dependence on conventional fossil fuels and virgin raw materials, while maintaining operational efficiency and product quality. On the alternative fuels front, RDF, biomass and agrowaste, as well as industrial wastes and liquid solvents,
offer strong substitution potential. In FY 2025-26, RDF and biomass/agrowaste contributed ~ 2.0 per cent and ~ 3.0 per cent, respectively, to our thermal fuel mix, with overall AFR utilisation at ~ 10.00 per cent.”
Yet the opportunity remains underutilised: the NITI Aayog cement decarbonisation roadmap places the current thermal substitution rate from alternative fuels at approximately 3 per cent, while other recent assessments estimate that alternative fuels supply around 6 per cent of kiln thermal energy, highlighting both progress and the significant scope for expansion. The key challenge is converting heterogeneous waste into a consistent kiln suitable fuel through segregation, sorting, drying, shredding and quality control, particularly because variations in moisture, particle size, chlorine and calorific value can affect kiln stability and clinker quality.
With modern cement kilns capable of co processing a wide range of suitably prepared waste materials, alternative fuels can simultaneously support fossil fuel substitution, reduce waste sent to landfill and strengthen the industry’s transition towards a more circular and lower carbon energy system.
Reducing dependence on virgin resources
Alternative raw materials are becoming increasingly important as the cement industry seeks to reduce its dependence on virgin limestone and other mineral resources while lowering the carbon intensity of cement and concrete. Industrial byproducts such as fly ash and blast furnace slag have already played a significant role in India’s transition towards blended cements, with Portland Pozzolana Cement and Portland Slag Cement accounting for around 72 per cent of total cement output, helping reduce the clinker to cement ratio to 0.67 in 2024, compared with a global average of 0.76.
However, the future raw material mix will need to become more diverse as the availability of fly ash and slag is expected to decline over time with the transition away from coal based power and conventional blast furnace steelmaking. NITI Aayog has therefore identified calcined clay, limestone, bio ash and construction and demolition waste as important future substitutes, noting that India has an estimated 1.5 billion tonnes of utilisable calcined clay reserves and that agricultural residues could potentially provide 15 million to 20 million tonnes per year of bio ash, subject to the development of effective supply chains.
Materials such as red mud, mineral wastes and suitably processed construction and demolition waste also offer opportunities to reduce the consumption of virgin resources and divert industrial waste from disposal. The decarbonisation potential is substantial: under India’s Net Zero pathway, the clinker ratio is projected to fall to 0.55 by 2070, with greater use of supplementary cementitious materials such as slag, calcined clay, limestone, fly ash, natural pozzolans and construction and demolition waste potentially avoiding around 100 million tonnes of clinker annually. The challenge will be to ensure consistent quality, adequate availability, processing infrastructure and suitable standards, but the direction is clear: expanding the range of alternative raw materials will be essential to creating a more resource efficient, circular and lower carbon cement industry.
The technology behind higher AFR substitution
Achieving higher alternative fuel and raw material substitution is increasingly a technology challenge as much as a waste availability challenge, because cement kilns require feedstocks with sufficient consistency to maintain stable operations and clinker quality. Waste preprocessing systems play a critical role in this process through segregation, sorting, screening, shredding, drying and removal of metals and other contaminants, converting heterogeneous municipal, industrial and commercial waste into a more uniform fuel with controlled particle size, moisture and calorific value. A report by CMA notes that the quality of alternative fuels can vary significantly, making preprocessing and quality control essential for efficient co processing. India has set an ambitious direction for scaling these technologies, with the NITI Aayog cement decarbonisation roadmap identifying an increase in thermal substitution
through alternative fuels from around 3 per cent currently to 20 per cent by 2030 as a key pathway for reducing emissions.
Rohit Kochar, Founder, Executive Chairman and CEO, Bert Labs says, “For brownfield plants, our approach begins by integrating IT and OT systems. IT infrastructure, including ERP, CRM, HRMS and other enterprise software platforms, is integrated with BERT Nova, our multi-tenant AI distributed and federated computing enterprise software platform. Operational technology, including the DCS, energy management, production management and quality management systems, is integrated into the same platform. This integration also enables greater centralisation of basic plant operations. Instead of each of 20 or 30 plants requiring large teams to independently manage operations, a significantly smaller central team can monitor multiple facilities through BERT Nova dashboards, covering safety, production, process management and product quality.”
Advanced feeding and dosing systems are equally important, enabling different alternative fuels to be introduced at appropriate points in the kiln system while managing variations in their physical and chemical characteristics. Automation, sensors and online monitoring can provide continuous information on fuel properties and process conditions, while AI and advanced process control can analyse these data streams to optimise fuel mixes, combustion conditions and kiln performance in real time. Digital twins can further enable manufacturers to simulate the operational impact of changing AFR characteristics before implementing adjustments on the plant floor. The future of higher substitution will therefore depend on integrating robust preprocessing with intelligent feeding and increasingly data driven process optimisation, allowing cement plants to increase the use of diverse waste streams without compromising thermal efficiency, production stability, emissions performance or product quality.
Overcoming challenges
Despite its considerable potential, large scale AFR adoption remains constrained by the quality and reliability of available waste streams. India generates approximately 62 million tonnes of municipal solid waste annually, but inadequate segregation and the heterogeneous nature of this waste can result in RDF with low calorific value, high moisture and ash content, making consistent kiln operation difficult. Contaminants such as stones, sediment and glass can damage equipment, while variations in waste supply caused by seasonal factors and short-term contracts further affect availability.
The technical implications are significant: high levels of chlorine, sulphur and alkalis can cause build ups within the kiln system, large fuel particles may not burn completely, and high moisture can increase specific heat consumption and reduce production capacity. Fuel ash can also affect clinker composition and quality, requiring careful control of the alternative fuel mix and raw meal chemistry. Quality assurance is therefore essential, with testing required for parameters including calorific value, moisture, ash, chloride, heavy metals and mineral composition before waste enters the kiln system. However, scaling up requires substantial investment in specialised storage, handling, preprocessing and feeding infrastructure; the CMA estimates that large scale coprocessing can require investments exceeding 25 to 30 crore per MTPA of clinker capacity at a thermal substitution rate of around 15 per cent.
Regulatory compliance adds another layer of responsibility, as cement plants must meet prescribed emission standards while ensuring that product quality and operational stability are not compromised. The challenge, therefore, is not simply to source more waste, but to build an integrated ecosystem of segregation, preprocessing, testing, long term supply arrangements and advanced kiln control that can transform variable waste streams into reliable industrial resources.
Building a circular and low carbon cement industry
India’s transition towards a circular and low carbon cement industry will depend on building a reliable ecosystem that connects waste generators, municipalities, waste processors, technology providers and cement manufacturers. The scale of the opportunity is substantial: India generates around 62 million tonnes of municipal solid waste annually, alongside significant volumes of industrial, agricultural and construction waste that could potentially be diverted from landfill and converted into useful fuels and raw materials through appropriate processing. However, scaling AFR requires stronger source segregation, consistent quality standards, long term supply arrangements and investment in collection, sorting, shredding, drying and preprocessing infrastructure. The NITI Aayog cement decarbonisation roadmap identifies increasing the thermal substitution rate through alternative fuels from around 3 per cent currently to 20 per cent by 2030 as an important pathway towards reducing the sector’s dependence on fossil fuels.
Industry Expert Dr SB Hegde says, “Carbon-adjusted profitability evaluates normal profit after explicit adjustment for carbon performance. A practical expression is: Carbon-Adjusted EBITDA = Conventional EBITDA – Carbon Cost + Green Premium Income. Carbon cost may be an internal carbon price, the actual cost of purchasing Carbon Credit Certificates under CCTS, or the opportunity cost of high emissions relative to peers. Green premium income arises when customers pay more for verified lower-carbon cement or when the company sells surplus credits. Tracking both conventional and carbon-adjusted profit side-by-side gives management a clearer picture of value creation under evolving market rules.”
Policy support will be equally important in creating clear standards for waste derived fuels, encouraging investments and strengthening collaboration between the cement and waste management sectors. The CMA report has also highlighted the potential for greater coprocessing to reduce landfill dependence while recovering both energy and material value from waste. With India committed to achieving
net zero emissions by 2070, AFR can become a significant part of the cement industry’s wider decarbonisation strategy.
Ultimately, the objective must move beyond treating waste as a disposal challenge and towards recognising it as a resource that can replace fossil fuels and virgin materials. By combining effective waste management, technological innovation, supportive regulation and industry collaboration, cement plants can emerge as important anchors of India’s circular economy while advancing towards a more resource efficient and lower carbon future.
Conclusion
Alternative fuels and raw materials are emerging as a critical pathway for the cement industry to reduce its dependence on fossil fuels and virgin resources while advancing its decarbonisation goals. By converting suitable waste streams and industrial byproducts into productive inputs, AFR can support greater resource efficiency, lower emissions and the transition towards a circular economy. However, scaling its adoption will require consistent waste quality, stronger supply chains, advanced preprocessing technologies and closer collaboration between industry, government and waste management stakeholders.















 Concrete4 weeks ago

 Concrete4 weeks ago

 Concrete4 weeks ago

 Concrete4 weeks ago