Connect with us

Economy & Market

Carbon Capture Systems

Published

on

Shares

Nathan Ashcroft, Director, Strategic Growth, Business Development, and Low Carbon Solutions – Stantec, explores the challenges and strategic considerations for cement industry as it strides towards Net Zero goals.

The cement industry does not need a reminder that it is among the most carbon-intensive sectors in the world. Roughly 7–8 per cent of global carbon dioxide (CO2) emissions are tied to cement production. And unlike many other heavy industries, a large share of these emissions come not from fuel but from the process itself: the calcination of limestone. Efficiency gains, fuel switching, and renewable energy integration can reduce part of the footprint. But they cannot eliminate process emissions.
This is why carbon capture and storage (CCS) has become central to every serious discussion
about cement’s pathway to Net Zero. The industry already understands and accepts this challenge.
The debate is no longer whether CCS will be required—it is about how fast, affordable, and seamlessly it can be integrated into facilities that were never designed for it.

In many ways, CCS represents the ‘last mile’of cement decarbonisation. Once the sector achieves effective capture at scale, the most difficult part of its emissions profile will have been addressed. But getting there requires navigating a complex mix of technical, operational, financial and regulatory considerations.

A unique challenge for cement
Cement plants are built for durability and efficiency, not for future retrofits. Most were not designed with spare land for absorbers, ducting or compression units. Nor with the energy integration needs of capture systems in mind. Retrofitting CCS into these existing layouts presents a series of non-trivial challenges.
Reliability also weighs heavily in the discussion. Cement production runs continuously, and any disruption has significant economic consequences. A CCS retrofit typically requires tie-ins to stacks and gas flows that can only be completed during planned shutdowns. Even once operational, the capture system must demonstrate high availability. Otherwise, producers may face the dual cost of capture downtime and exposure to carbon taxes or penalties, depending on jurisdiction.
Despite these hurdles, cement may actually be better positioned than some other sectors. Flue gas from cement kilns typically has higher CO2 concentrations than gas-fired power plants, which improves capture efficiency. Plants also generate significant waste heat, which can be harnessed to offset the energy requirements of capture units. These advantages give the industry reason to be optimistic, provided integration strategies are carefully planned.

From acceptance to implementation
The cement sector has already acknowledged the inevitability of CCS. The next step is to turn acceptance into a roadmap for action. This involves a shift from general alignment around ‘the need’ toward project-level decisions about technology, layout, partnerships and financing.
The critical questions are no longer about chemistry or capture efficiency. They are about the following:

  • Space and footprint: Where can capture units be located? And how can ducting be routed in crowded plants?
  • Energy balance: How can capture loads be integrated without eroding plant efficiency?
  • Downtime and risk: How will retrofits be staged to avoid prolonged shutdowns?
  • Financing and incentives: How will capital-intensive projects be funded in a sector with
    tight margins?
  • Policy certainty: Will governments provide the clarity and support needed for long-term investment
  • Technology advancement: What are the latest developments?
  • All of these considerations are now shaping the global CCS conversation in cement.

Economics: The central barrier
No discussion of CCS in the cement industry is complete without addressing cost. Capture systems are capital-intensive, with absorbers, regenerators, compressors, and associated balance-of-plant representing a significant investment. Operational costs are dominated by energy consumption, which adds further pressure in competitive markets.
For many producers, the economics may seem prohibitive. But the financial landscape is changing rapidly. Carbon pricing is becoming more widespread and will surely only increase in the future. This makes ‘doing nothing’ an increasingly expensive option. Government incentives—ranging from investment tax credits in North America to direct funding in Europe—are accelerating project viability. Some producers are exploring CO2 utilisation, whether in building materials, synthetic fuels, or industrial applications, as a way to offset costs. This is an area we will see significantly more work in the future.
Perhaps most importantly, the cost of CCS itself is coming down. Advances in novel technologies, solvents, modular system design, and integration strategies are reducing both capital requirements
and operating expenditures. What was once prohibitively expensive is now moving into the range of strategic possibility.
The regulatory and social dimension
CCS is not just a technical or financial challenge. It is also a regulatory and social one. Permitting requirements for capture units, pipelines, and storage sites are complex and vary by jurisdiction. Long-term monitoring obligations also add additional layers of responsibility.
Public trust also matters. Communities near storage sites or pipelines must be confident in the safety and environmental integrity of the system. The cement industry has the advantage of being widely recognised as a provider of essential infrastructure. If producers take a proactive role in transparent engagement and communication, they can help build public acceptance for CCS
more broadly.

Why now is different
The cement industry has seen waves of technology enthusiasm before. Some have matured, while others have faded. What makes CCS different today? The convergence of three forces:
1. Policy pressure: Net Zero commitments and tightening regulations are making CCS less of an option and more of an imperative.
2. Technology maturity: First-generation projects in power and chemicals have provided valuable lessons, reducing risks for new entrants.
3. Cost trajectory: Capture units are becoming smaller, smarter, and more affordable, while infrastructure investment is beginning to scale.
This convergence means CCS is shifting from concept to execution. Globally, projects are moving from pilot to commercial scale, and cement is poised to be among the beneficiaries of this momentum.

A global perspective
Our teams at Stantec recently completed a global scan of CCS technologies, and the findings are encouraging. Across solvents, membranes, and
hybrid systems, innovation pipelines are robust. Modular systems with reduced footprints are
emerging, specifically designed to make retrofits more practical.
Equally important, CCS hubs—where multiple emitters can share transport and storage infrastructure—are beginning to take shape in key regions. These hubs reduce costs, de-risk storage, and provide cement producers with practical pathways to integration.

The path forward
The cement industry has already accepted the challenge of carbon capture. What remains is charting a clear path to implementation. The barriers—space, cost, downtime, policy—are real. But they are not insurmountable. With costs trending downward, technology footprints shrinking, and policy support expanding, CCS is no longer a distant aspiration.
For cement producers, the decision is increasingly about timing and positioning. Those who move early can potentially secure advantages in incentives, stakeholder confidence, and long-term competitiveness. Those who delay may face higher costs and tighter compliance pressures.
Ultimately, the message is clear: CCS is coming to cement. The question is not if but how soon. And once it is integrated, the industry’s biggest challenge—process emissions—will finally have a solution.

ABOUT THE AUTHOR:
Nathan Ashcroft, Director, Strategic Growth, Business Development, and Low Carbon Solutions – Stantec, holds expertise in project management, strategy, energy transition, and extensive international leadership experience.


Concrete

Wonder Cement appoints Mahesh Singh as VP Corporate Brand Communication 

Published

on

By

Shares

Singh brings 20+ years of brand and marketing experience, and will lead integrated corporate brand communication initiatives at Wonder Cement 

New Delhi

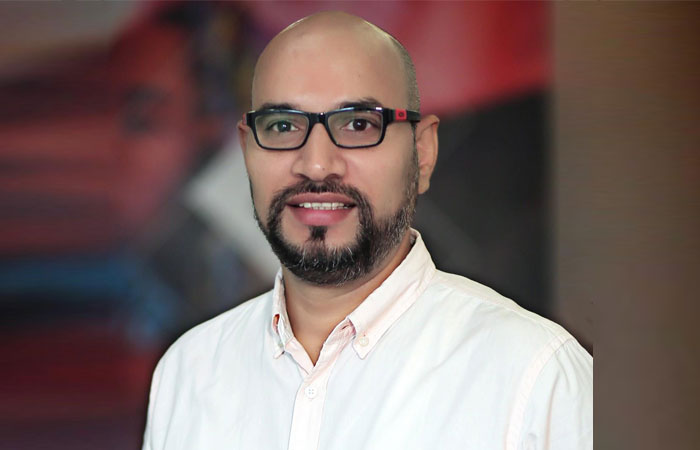
Wonder Cement, a leading cement manufacturer, has appointed Mahesh Singh as Vice President – Corporate Brand Communication. In his new role, he will oversee corporate brand strategy and communication, including digital and performance marketing, public relations, trade, events, exhibitions, sports and experiential marketing. 

Singh brings over two decades of experience across marketing and communications, with roles spanning the automotive industry, agencies and entrepreneurship. He spent more than a decade with Honda Motorcycle & Scooter India, working across integrated communication, media, digital, retail and consumer engagement. His stint also included helping build the company’s digital marketing capabilities. 

He moved to dentsu X India as Vice President – Strategy & Planning, working across categories such as automotive, auto components, electric vehicles, FMCG, consumer electronics, BFSI, apparel and brand consulting. His responsibilities included media and marketing strategy, product launches, content, performance marketing and consumer activations. 

Singh subsequently took an entrepreneurial route with Radiant Brands before joining Shriram Ltd (SPR Autotech) as Head – Marketing & Communications. There, his remit included brand and corporate strategy, communications, PR and ORM, retail identity, loyalty programmes and events. 

At Wonder Cement, Singh will be responsible for bringing together the company’s corporate brand communication initiatives across digital, performance marketing, PR, trade, sports and experiential platforms. The role will focus on creating an integrated approach to communication across consumers, trade partners and other key stakeholders. 

The appointment brings to Wonder Cement a marketer whose career has spanned the brand, agency and entrepreneurial sides of the communications ecosystem. 

Wonder Cement, part of the RK Group, is a cement manufacturer with roots in Rajasthan and a focus on quality, trust and transparency. The company has grown to six manufacturing plants, and a cement capacity of 21.5 MTPA. With more than 2,000 employees and a network of over 5,000 dealers, its operations span manufacturing, distribution and customer engagement, with a focus on consistent product quality and efficient execution. 

Continue Reading

Concrete

JSW Cement commissions additional 1 MTPA grinding unit at Nagaur

Published

on

By

Shares

With this commissioning, JSW Cement’s total cement grinding capacity has increased to 25.10 MTPA, 
Mumbai

JSW Cement, one of India’s leading green cement producers and part of the diversified JSW Group, today announced the successful commissioning of an additional 1.00 MTPA cement grinding unit at Nagaur, Rajasthan. The commissioning marks another significant milestone in the Company’s growth strategy.

With this commissioning, JSW Cement’s total cement grinding capacity has increased to 25.10 MTPA, while its total clinker manufacturing capacity, including clinker capacity at its joint venture, JSW Cement FZC, stands at 9.74 MTPA.

JSW Cement had commenced operations in North India in March 2026 with the Nagaur Integrated Plant, comprising a 3.30 MTPA clinkerisation unit and 2.50 MTPA cement grinding unit. With the commissioning of the additional 1.00 MTPA cement grinding unit, the plant’s total cement grinding capacity has increased to 3.50 MTPA, enhancing the company’s ability to cater to the growing cement demand across Rajasthan, Haryana, Punjab and the National Capital Region (NCR). The expansion has been funded through a strategic mix of equity and long-term debt.

During the quarter ended 30th September 2026, JSW Cement has also commissioned the Alternate Fuel Handling System and the Waste Heat Recovery system (WHRS) at the Nagaur Integrated Plant.

Nilesh Narwekar, CEO, JSW Cement, said: “The commissioning of additional 1.00 MTPA grinding capacity at Nagaur is a key strategic priority for us and will accelerate JSW Cement’s expansion into North India. We look forward to servicing the growing needs of the region and contributing to the economic growth of Rajasthan, Haryana, Punjab and the NCR area. I am delighted to share that the company has commissioned this grinding unit within the expected timeline, showcasing our project execution capabilities. Further, the Alternate Fuel Handling System and the Waste Heat Recovery system (WHRS) are expected to substantially reduce our production costs going forward.”

Continue Reading

Concrete

UltraTech becomes first Indian cement firm to cross 2 GW green energy

Published

on

By

Shares

UltraTech Cement has crossed 2 GW of captive green energy capacity, with renewables and waste heat recovery meeting 48 per cent of its power needs.

Mumbai

UltraTech Cement Limited has surpassed 2 GW of installed green energy capacity for captive use, becoming the first cement company in India to achieve the milestone. The Aditya Birla Group company commissioned 116.55 MW of wind capacity at its Inter-State Transmission System-connected wind-solar hybrid project in Barmer, Rajasthan, along with 10 MW of Waste Heat Recovery System capacity at Sarlanagar Cement Works in Karnataka.

With these additions, UltraTech’s cumulative installed green energy capacity has reached 2,024 MW. This includes 1,580 MW of renewable energy capacity and 444 MW of waste heat recovery capacity, together meeting around 48 per cent of the company’s current power requirements.

The company said the milestone reflects the progress of its long-term energy transition strategy. In FY27 so far, nearly one-third of UltraTech’s 76 manufacturing units in India have maintained green energy utilisation above 50 per cent of their electricity requirements, while five units have crossed 95 per cent.

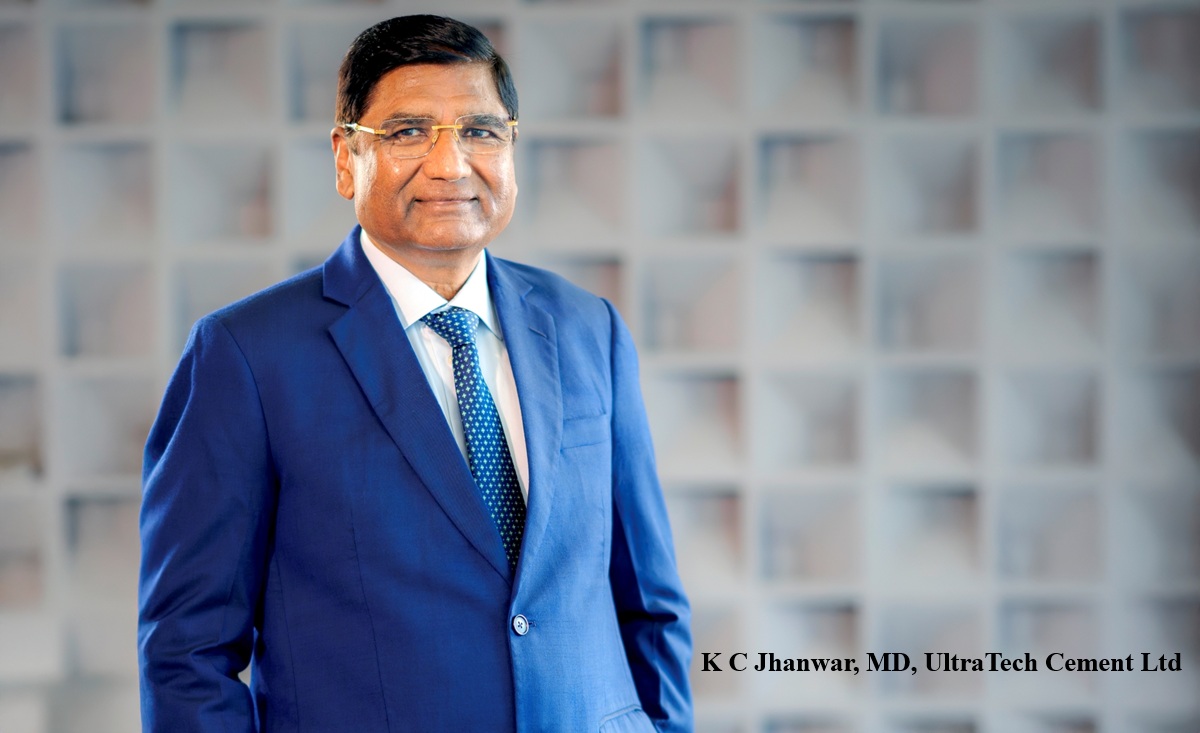
K C Jhanwar, Managing Director, UltraTech Cement Limited, said, “Crossing the 2 GW green energy milestone is the result of a strategy we have pursued consistently over the past decade. Cement is an energy-intensive, hard-to-abate sector, and showing that reliability and growth can go hand in hand with a rapid shift to green energy sets a benchmark for the industry. With nearly half of our power needs now met through green energy, we are significantly less exposed to fossil fuel supply constraints and power price volatility. As we scale up renewables, waste heat recovery and battery storage across our operations, we are building an energy foundation for stable, long-term growth.”

UltraTech commissioned 430 MW of green energy capacity in FY26 and continues to expand its renewable energy and waste heat recovery portfolio.

The company is also progressively integrating Battery Energy Storage Systems across its operations to improve renewable energy utilisation and supply reliability.

In 2025, UltraTech operationalised what it described as India’s first on-site hybrid round-the-clock renewable energy project at Sewagram Cement Works in Gujarat. The project combines solar, wind and battery storage.

As part of its decarbonisation strategy, UltraTech said it has not invested in new captive thermal power capacity for either greenfield projects or brownfield expansions at its integrated units for more than a decade.

The company said its expanding green energy portfolio is helping reduce dependence on conventional grid electricity and fossil fuel-based power, while lowering exposure to fluctuations in coal and electricity prices.

UltraTech aims to increase green energy’s share in its total power mix to 85 per cent by 2030. As a member of RE100, it has also committed to meeting 100 per cent of its electricity requirement through renewable sources by 2050.

UltraTech Cement, the cement flagship of the Aditya Birla Group, has a total grey cement capacity of 210.1 MTPA and white cement and putty capacity of 3.5 MTPA. The company is also a signatory to the GCCA Climate Ambition 2050 and has committed to the GCCA Net Zero Concrete roadmap.

Continue Reading

Video Thumbnail
▶

    SIGN-UP FOR OUR GENERAL NEWSLETTER

    Trending News

    SUBSCRIBE TO THE NEWSLETTER


    Don't miss out on valuable insights and opportunities to connect with like minded professionals.


      This will close in 0 seconds