Connect with us

Concrete

Weathering the monsoon blues

Published

on

Shares

India’s cement industry stands at a transformative juncture.
The recent launch of the nation’s first cluster of Carbon Capture and Utilisation (CCU) testbeds—an academia-industry collaboration aimed at the cement sector—is more than a symbolic stride. It signals a commitment to deep decarbonisation pathways, essential to achieving India’s net-zero emissions target by 2070. The CCU initiative holds promise not just for emissions mitigation, but as a scalable, commercially viable technology that could redefine the sustainability narrative across the value chain.
CCU in cement can unlock new revenue streams through utilisation pathways like building materials, fuels and chemicals. Stakeholders view this as a strategic enabler for compliance with tightening carbon regulations and investor scrutiny. The initiative may catalyse a robust carbon tech ecosystem, with ripple effects across allied industries. Success here could significantly reduce the sector’s carbon intensity per tonne of cement produced.
On the other side of the ledger, operational realities persist. A premature monsoon this year has tempered dealer optimism, with subdued despatches expected through June. Historically, the monsoon season dampens construction momentum, impacting cement off-take and putting short-term pricing power under pressure.
Despite such cyclical headwinds, FY25 closed on a robust note, with installed capacity touching 655 MTPA—up 4.8 per cent year-on-year. A notable 11 per cent surge in cement volumes in Q4, spurred by accelerated infrastructure execution and commercial real estate activity, offset the lukewarm performance in H1.
Looking ahead, FY26 is projected to deliver demand growth in the range of 6 to 7.5 per cent, underpinned by government push in roads, housing, and rural infrastructure. The industry will, however, need to balance this growth with rising ESG obligations, fluctuating fuel costs and evolving regulatory expectations.

Follow me on twitter @PratapPadode

Concrete

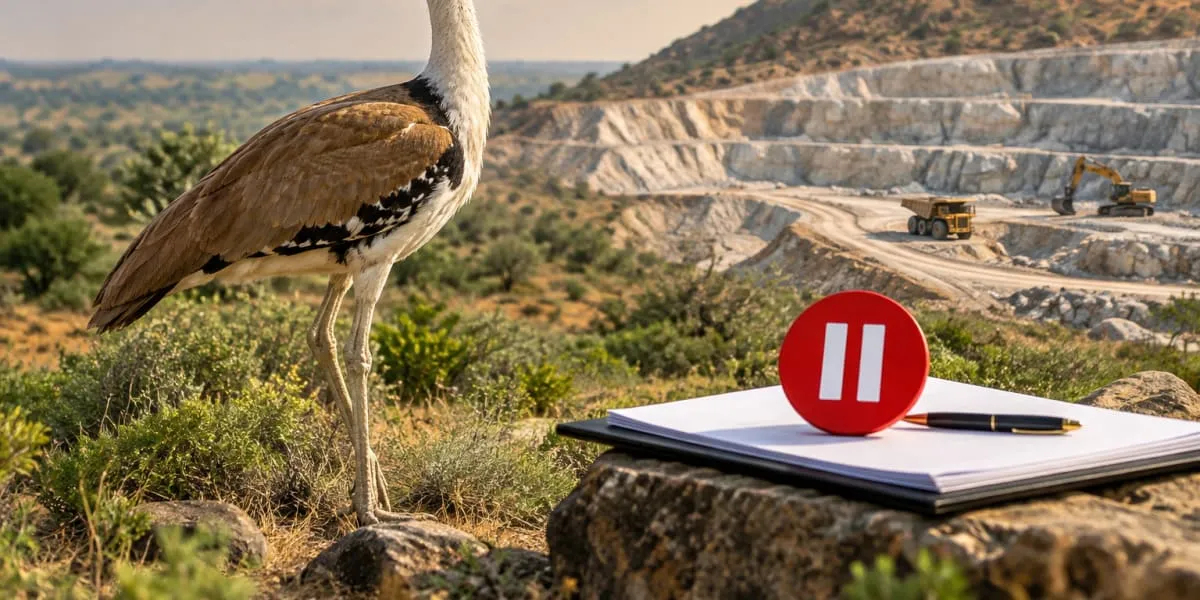
Centre Defers Clearance for Limestone Mine Near Bustard Habitat

Panel seeks revised mining plan and safeguards for pipelines and wildlife
Published

on

By

Shares

The Centre has deferred environmental clearance for a proposed limestone mine near a Great Indian Bustard habitat in Ramgarh, Rajasthan’s Jaisalmer district. The critically endangered species has an estimated wild population of about 130 in India.

Continue Reading

Concrete

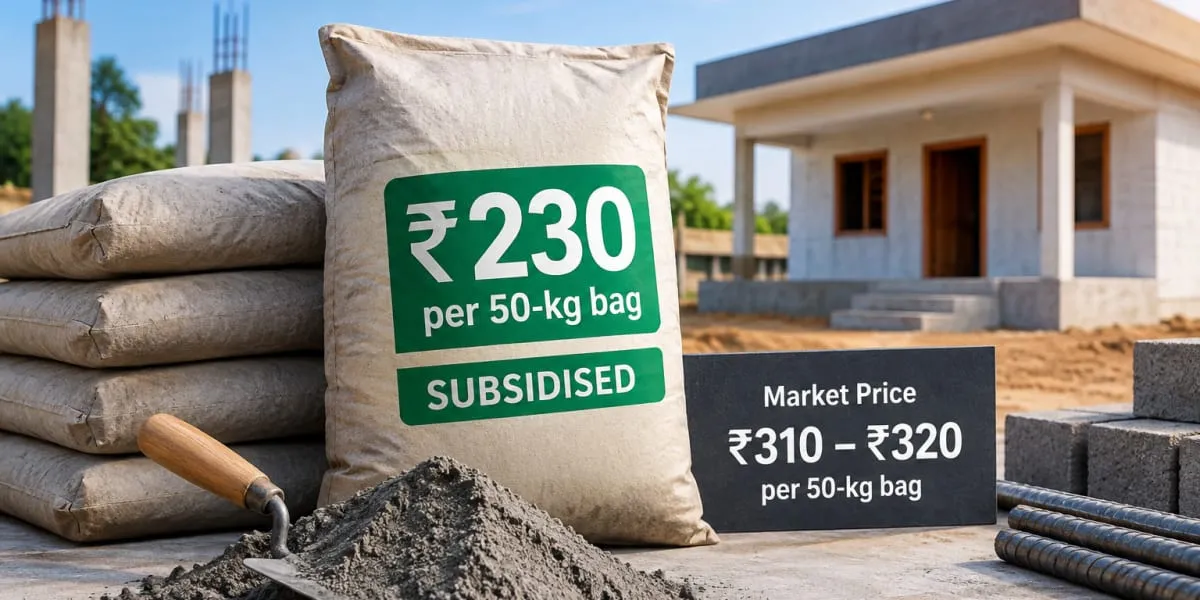
Telangana to Supply Subsidised Cement for Indiramma Houses

Poor families allotted Indiramma houses to receive cement at Rs. 230 per bag
Published

on

By

Shares

The Telangana government will supply cement at a subsidised price of Rs. 230 per 50-kg bag to poor and low-income families allotted Indiramma houses. The prevailing market price is between Rs. 310 and Rs. 320 per bag, the Assembly was informed on Thursday.

Continue Reading

Concrete

Cement Demand Strong As Prices Remain Stable

Volumes rise amid steady trade pricing and higher fuel costs

Published

on

By

Shares

Channel checks show cement demand remained healthy with volume growth estimated at six to seven per cent in July and August 2026. Trade prices were broadly stable while non-trade prices were volatile in the East, and attempted hikes were rolled back amid higher competition. Average fuel costs rose in August by five to nine per cent, lifting spot petcoke and coal prices.

All-India trade price remained flat month on month in August as increased rake supplies and competition offset early increases. Monsoon related demand softness limited sustained hikes and dealers indicated further attempts would depend on demand trends. Combined July and August volumes were estimated at six to seven per cent, supported by infrastructure spending while retail housing remained weather sensitive.

In the South, a Rs20 a bag hike in August did not hold and prices stayed flat month on month, while dealers planned Rs25 to Rs30 a bag from fifth September 2026 but with uncertain sustainability. In the East, trade prices were unchanged and non-trade prices corrected by Rs15 to Rs20 a bag amid weak construction in West Bengal, Jharkhand and Odisha.

The West remained most resilient on pricing and demand despite attempted hikes of Rs10 to Rs15 a bag, and Gujarat saw relatively better volumes in August. North and Central markets kept prices range bound as players focused on ramping up utilisation of new capacity, with schemes of up to Rs2 to Rs3 a bag used to meet month-end targets. Overall construction activity improved as the monsoon eased, aiding a pickup in several states.

Fuel cost pressures persisted, with South African coal at USD114 a t and petcoke around USD146 to USD147 a t in August, while spot imported petcoke and coal were higher. Imported coal consumption cost stood at Rs2.07 per Kcal and petcoke at USD2.11 per Kcal. Analysts estimate the all-India trade spread to decline by Rs90 to Rs100 a t quarter on quarter, weighing on near-term profitability and they prefer UltraTech Cement (UTCEM), JK Cement (JKCE) and Grasim Industries (GRASIM).

Continue Reading

Video Thumbnail

    SIGN-UP FOR OUR GENERAL NEWSLETTER

    Trending News

    SUBSCRIBE TO THE NEWSLETTER


    Don't miss out on valuable insights and opportunities to connect with like minded professionals.


      This will close in 0 seconds