The Indian cement manufacturers are likely to face serious challenges regarding gypsum availability and cost in the near future. Ramachandran, Chief Executive Officer, Zawawi Minerals LLC, Sultanate of Oman, discusses how identifying and ensuring a consistent supply of gypsum will become an on-going challenge.
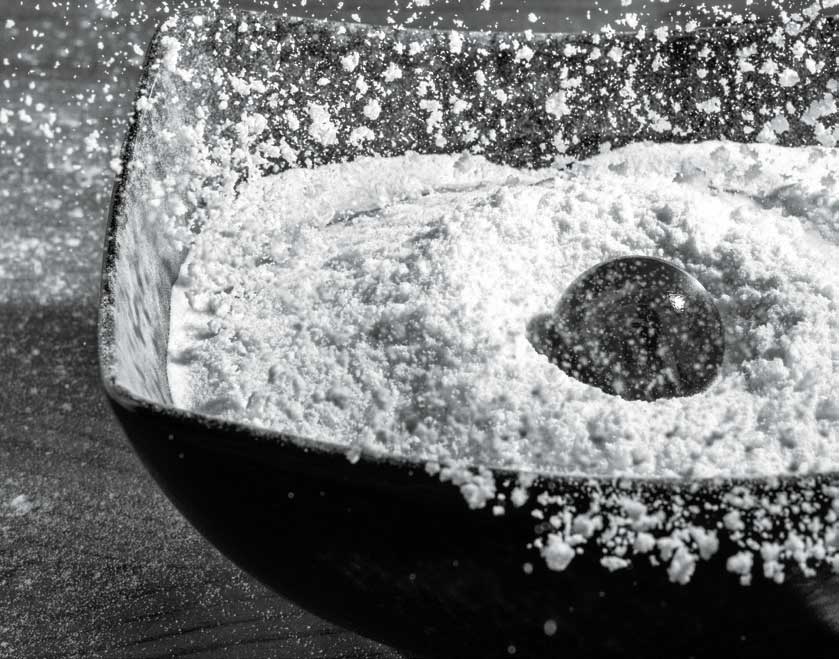
The Indian cement demand is set for its third straight year of growth with a 7 per cent to 9 per cent jump to over 400 million tonnes in fiscal 2024. Cement demand in India is expected to continue growing for the next few years, backed by the government’s push for infrastructure development and increasing demand in the housing sectors. However, India has a scarcity of domestic gypsum supplies, which does not bode well for the fast-growing cement industry. An essential, non-substitutable critical raw material, gypsum is required for all varieties of cement production.
Since 2009, the gypsum supply deficit in the Indian domestic market has led to increased dependence on largely imports of natural gypsum predominantly from the Sultanate of Oman, and other countries like Iran, Thailand, small volume from Pakistan and Bhutan by road to the northern part of India. This dependency shall continue in coming years and is growing day by day.
FY 2009 to 2023, India imported 57.09 million tonnes of gypsum cumulatively, witnessed at a CAGR of 16.60 per cent. The gypsum import volume represents nearly 35 per cent of the total gypsum consumed by the cement industry. The Sultanate of Oman alone supplied 28 million tons (49.05 per cent) and the remaining 29.09 million tonnes were from Thailand, Iran, Pakistan and Bhutan etc. FY 2022 to 2023 – India imported 5.76 million tons of gypsum, which represents 35 per cent of the total gypsum consumption. The Sultanate of Oman supplied 5.20 million tons (90.39 per cent) and the remaining 0.56 million tonnes are from Thailand, Iran and Bhutan.
According to the production growth of cement and gypsum board, the industry’s demand for gypsum is expected to reach nearly 380 million tons cumulatively by FY 2037-2038 with a CAGR of 5.15 per cent. The maximum local gypsum supplies could be around 200 million tons, which includes FGD gypsum, Phospho-gypsum, Natural gypsum etc. The limited availability of domestic gypsum will lead to supply constraints and increased dependence on imports, cumulatively needing to import nearly 180 million tonnes of gypsum to meet the domestic demands.
Natural Gypsum: India’s local natural gypsum production and supplies are limited due to deep seated gypsum reserves not feasible for mining.
Phospho-gypsum: Phospho-gypsum production in India is limited, the majority of the existing Phosphop-gypsum stockpile may be consumed for on-going road construction, as reported by the Ministry of Road Transport and Highways. Recently, the Central Road Research Institute (CRRI) carried out an R&D project to explore the feasibility of Phospho-gypsum for road embankment and subgrade construction. The performance of Phospho-gypsum was as good as conventional sand embankment. It was concluded that 100 per cent of Phospho-gypsum can be used for both embankment and subgrade construction.
An Indian fertiliser company has constructed a road using phosphor-gypsum, which was evaluated by the CRRI. Based on their report, the Indian Road Congress (IRC) has been accredited for using phosphor-gypsum waste material for the road constructions.
FGD (Flue Gas Desulphurisation) gypsum: The production growth of FGD gypsum uncertainty shall continue due to huge investments of over US$ 13 billion for installing FGD units by the heavy debt-burden coal power companies. India had initially set a 2017 deadline for 2,11,520 MW thermal power plants to install FGD units to cut Sulphur emissions. That was later changed to varying deadlines for different regions, ending in 2022, and further extended to a period up to 31st December 2026. According to the latest guidelines, the power plant which have plans to retire before 31st December 2027 will now be exempted from installing FGD units and if the non-retiring power plants fail to adhere to the new deadlines, they will have to pay ‘environmental compensation’ ranging from 20 paise to 40 paise per unit electricity generated.
According to the Central Electricity Authority (CEA) the FGD unit implementation status as of May 2023 – only 9,280 MW (4.40 per cent) capacity already installed and only 1,00,430 MW have been awarded bids for installing FGD units.
On the other hand, considering the huge capital investments, limestone costs for the FGD process and other operating costs, the FGD gypsum will not be available at a cheaper price for the Indian consumers – only the limestone cost itself for the production of per tonne FGD gypsum will be US$ 18 or above.
Gypsum Export Supply Outlook
Supply from Thailand: Asia’s past dominant gypsum exporter began to cap their exports with the goal of conserving resources for their own significant domestic industries. The government authority regulated the minimum FOB (Free on Board) export selling price. Presently Thailand exports its gypsum at an FOB price of over US$ 20 per tonne and exports over 97 per cent of its gypsum to the historical gypsum importing countries in Southeast Asia.
Supply from Iran: Iran gypsum export volume significantly started falling after tightening the sanction parameters. Gypsum exports to India started dropping, the exports dropped to 0.17 million tonnes in the FY 2022-2023 from 1.57 million tonnes in the FY 2021-2022, nearly 89.35 per cent dropped.
Historically, Iran exports around 10 per cent of its annual production of gypsum majority to India and other GCC countries like UAE, Qatar etc. If the sanctions are lifted, the Iranian construction and infrastructure sector will grow exponentially, and this will create an immense demand for gypsum in the local construction industries. Hence, the gypsum export volumes shall be limited and the FOB selling price may be increased to the level of the pre-sanction period, i.e., FOB US$ 14 -15 per ton or more.
Supply from the Sultanate of Oman: The World’s largest gypsum supplier – Oman exports nearly 10 million tonnes of gypsum yearly, which is 50 per cent of Asia, Southeast Africa and GCC countries’ imported gypsum demand. Oman exports 50 per cent of its total volume to India and the remaining 50 per cent are exported to the historical gypsum importers like Bangladesh, Indonesia, Malaysia, Vietnam, Philippines, Japan, South Korea, UAE, Southeast Africa etc.
Gypsum, key critical raw material for the cement and gypsum board manufacturing industries, much of the imported gypsum consuming the above countries is now turning to the Sultanate of Oman for its requirements of the commodity. The Sultanate of Oman is emerging as the single most important supply source for gypsum, with no rivals. However, Oman’s present exportable gypsum reserves are very limited.
The Government authority of the Sultanate of Oman introduced w.e.f. January 2017, a FOB floor price of US$ 12.50 per ton of raw gypsum exported out of the country, which is keen to increase the FOB prices in coming years to meet its own objectives, to increase the country’s non-oil export revenue.
Even though gypsum accounts for just 2 per cent to 3 per cent of the total cost of cement sales, the Indian cement manufacturers are likely to face serious challenges regarding its availability and cost in the near future. Identifying and ensuring a consistent supply of gypsum will become an on-going challenge.
Data Sources
- Global cement magazine
- Global gypsum magazine
- The Fertiliser Association of India (FAI)
- Central Electricity Authority of India (CEA)
- The Ministry of Energy and Mining – The Sultanate of Oman
- Directorate General of Foreign Trade (DGFT) – Government of India
- The Ministry of Road Transport and Highways of India
- The Central Road Research Institute (CRRI) of India
- Various published reports on Cement and Gypsum industries
ABOUT THE AUTHOR
Ramachandran is the Chief Executive Officer with Zawawi Minerals LLC in The Sultanate of Oman.














 Concrete3 weeks ago

 Concrete3 weeks ago
 Concrete4 weeks ago

 Concrete3 weeks ago