

Concrete
The Future Looks Green


Green Cement is no longer a distant thing, it is a concrete reality. As the Indian cement industry marches towards its net zero target, Dr Hitesh Sukhwal, Head – Environment, Udaipur Cement Works, gives an in-depth analysis of green cement and what the future holds for sustainability in cement manufacturing.
India is the second largest cement producing country in the world, after China, both in quality and technology. Indian cement plants are today the most energy efficient and environment friendly. The Indian cement industry is a frontrunner for implementing significant technology measures to ensure a greener future. The cement industry is an energy intensive and significant contributor to climate change. Cement production contributes greenhouse gasses directly and indirectly into the atmosphere through calcination and use of fossil fuels in an energy form. The industry believes in a circular economy by utilising alternative fuels and raw materials for making cement. Cement companies are focusing on major areas of energy efficiency by adoption of technology measures, clinker substitution by alternative raw material for cement making (blended cement), alternative fuels and green and clean energy resources. Cement industries are putting efforts on energy saving, reducing clinker factor (through blended cement) and CO2 footprint. All these efforts are being done for making green cement towards environment protection and a sustainable future.
Making Green Cement
While we talk about the carbon negative cement manufacturing process, our thrust is on green cement manufacturing. For cement industries, green is not a green cement in colour. It is a sustainable eco-friendly cement that can reduce the carbon footprint of cement production. The rise of blended cement, by utilising fly ash 30-35 per cent in Portland Pozzolana Cement (PPC) and slag 60-65 per cent in Portland Slag Cement (PSC), has made the cement green, which helps to reduce clinker factor and resultant minimise carbon footprint. The production of cement is estimated to rise over 600 million tonnes per annum by the year 2025. The Government of India has committed to five pledges called ‘Panchamrit’ at the COP26 summit.
- Reach net zero emission target by the year 2070.
- Installing non fossil fuel 500 GW electricity capacity by the year 2030.
- Generate half of all energy requirements by the year 2030 from renewable energy sources 4. Reduce emissions by 1 billion tonnes from now to 2030.
- Reduce emission intensity of GDP by 45 per cent by the year 2030.
The cement industries are a top source of carbon dioxide emissions generation through fuel as well as electricity consumption. Pressure for the cement industry to minimize carbon emissions has increased rapidly from investors and government, both. Cement industries are looking forward to various options to decarbonise cement through the decarbonisation road map.
Followings are considered for low carbon technology road map: - Energy efficiency measures
- Reduction of clinker factor through product mix (slag, fly ash, pozzolana and others)
- Generation of more power from waste heat recovery system
- Circular economy – utilisation of alternative fuel and raw materials (RDF, hazardous waste, etc)
- Use of renewable energy sources like solar and wind power
- Use biomass as an alternative fuel
- Modernisation/upgradation of manufacturing process
- Green supply chain: eco labelling, green sourcing, optimising transport routes and mode of transport (like railway, green fuel etc.)
- Technological innovation: carbon capture, use and storage technologies
- Carbon sequestration
Most of the cement plants have already implemented the above top seven points and minimised their carbon emissions. To reduce carbon emissions, the cement industry requires a large scale of investments on technologies for maintaining a low carbon technology road map.
Types of Green Cement
- Portland Pozzolana Cement (PP) – IS:1489-2015 (Part-I): Fly ash
- Portland Pozzolana Cement (PP) – IS:1489-2015 (Part-II): Calcined Clay
- Portland Slag Cement (PSC) – IS:455-2015
- Composite Cement – IS:16415-2015
- Sulphate Resisting Portland Cement – IS:12330-1988
- Super Sulphated Cement – IS:6909-1990
- Portland Limestone Cement (PLC)
- Portland Composite Cement (PCC)
- Portland Dolomitic Limestone Cement (PDC)
- Limestone Calcined Clay Cement (LC3)
- Reactive Belite reach Portland Cement (RBPC)
- Geopolymer Cement
Advantages of Green Cement
- It has potential to bring down carbon emission near about 80 per cent lower than the production of traditional cement.
- Best in construction for green building – acid resistance and lower atmospheric heat.
- Low chloride permeability as compared to OPC.
- Requires less amount of energy during manufacturing.
- Green cement is economically and environmentally friendly.
- Green cement reduces air and land pollution.
- High tensile strength and higher resistance to chemical corrosion.
- Low water demand thus water conservation.
- Natural resource conservation.
- Boost a circular economy.
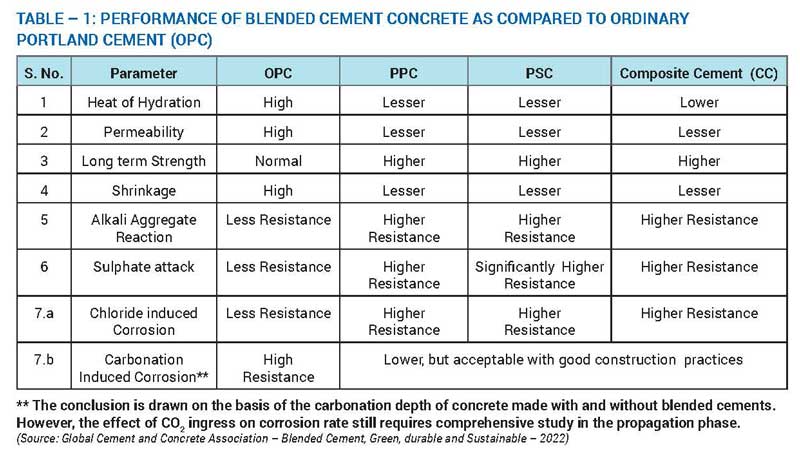
The analysis results from the above table, the performance of blended cement was observed better than OPC concrete excluding resistance against carbonation. Concrete made with PPC, PSC and composite cement has a longer service life as compared to OPC concrete in an aggressive environment.
Environmental Benefits of Green Cement
To analyse the environmental impacts of blended cement, various research is being performed by national and international agencies. In blended cement, as the clinker factor is reduced, the corresponding requirements of limestone, additives, coal and electrical energy for production of blended cement will be reduced proportionately. In PPC, PSC and composite cement, the clinker factor is reduced to 65 per cent, 40 per cent and 45 per cent respectively.
As per Indian standard specification IS: 455-2015, GBFS can be used in the range of 25-70 per cent in the PSC. Indian cement industries utilise about 92 per cent of granulated slag generated by the different steel plants. Currently, India produces approximately 25 million tonnes of blast furnace slag out of which 22 million tonnes of slag is granulated. At present, an average of 57 per cent (by weight) of GBFS is used in PSC in India1.
Fly ash is being used by the cement industry as a pozzolanic material in manufacturing of PPC. It saves both precious limestone and coal. The utilisation of fly ash in manufacturing of cement is a high value-added use. Fly ash conforming to standard IS: 3812 (1) 2013 can be used (up to 35 per cent maximum) in the manufacture of PPC as per IS: 1489 (part 1) 2015. The enhanced use of fly ash in PPC results in the reduction of clinker factor in cement, followed by lessened CO2 emissions through decreased fuel combustion and limestone calcination1.
In blended cement, while the clinker factor is reduced in PPC, PSC and composite cement, it will not only help to prevent land pollution due to increasing production of such types of high-volume industrial waste but also reduce corresponding direct emission of carbon dioxide.

Challenges
In the near future, as other industrial sectors are also having a decarbonise target, fly ash and slag from energy and steel industries could be in shorter supply as clinker substitutes. Biomass supply varies by region to region therefore its availability for utilisation as an alternative fuel could be a costly affair. The use of alternative fuels in the cement industry is growing rapidly to increase the Thermal Substitution Rate (TSR). The industry is now working towards TSR of 25 per cent by 2025 and 30 per cent by 2030 (CMA 2020 data). A region wise inventorisation of alternative fuel (like MSW, biomass, industrial byproduct, hazardous waste), which has high calorific value, is an urgent requirement. Moreover, there are several challenges associated like the segregation of MSW, collection of biomass, handling of hazardous waste etc.
Although the leading cement companies in India accepted the goal to achieve Net Zero target by 2050. However, carbon emission from calcination of limestone (process emissions) is still one of the biggest challenges for the cement industry. Here, technological innovations like carbon capture, use and storage (CCUS) and carbon sink require more R&D for mitigation of carbon dioxide emission, and hence for making more green cement.
Green is the Future
Green cement is the future of the cement industry and best for the environment. If we can reduce the clinker factor, it would reduce the significant amount of carbon emission during cement making. Besides manufacturing of PPC, PSC and Composite Cement, the cement industry is now doing R&D on PLC. The Indian cement industry is playing a catalytic role in natural resource conservation and boosting the circular economy. For making cement, utilisation of other industrial waste as an alternative fuel and raw material, adopting renewable energy sources, green procurement and supply chain management – all these efforts are put by cement industries for green cement production.
The use of PPC and PSC is permitted by national and international standards/specifications including most government bodies1. The partial replacement of clinker, which is an expensive component of cement as well as resource, energy and emission intensive, can be ground with these additives (like pozzolana and granulated blast furnace slag) to improve the sustainability of the material. Most importantly, the performance of cement can be improved through this replacement. The use of PPC conforming to requirement of IS:1489 in substructures of bridges is already permitted by the Ministry of Railways, Railway Board, Government of India.
In India, the production of OPC is continuously declining, with simultaneous increase in production of blended cements like PPC, PSC and composite cement based on granulated blast furnace slag and fly ash. Other cement formulations such as PLC and limestone calcined clay cement are also at different stages of development in India. At present, blended cements have a greater share (73 per cent) in comparison to OPC (27 per cent) of the total cement production. Blended cements provide the means to reduce the clinker factor even further soon, without a compromise on economy and safety1.
References
- Global Cement and Concrete Association – Blended Cement, Green, Durable and Sustainable – 2022
ABOUT THE AUTHOR:
Dr Hitesh Sukhwal is the Head – Environment at JK Lakshmi Cement. He is the Environment Coordinator for the North-West region units. He has MSc and PhD degrees in Environmental Sciences from Mohanlal Sukhadia University. His area of expertise is environment legislation.











Meghalaya Cabinet Approves MCCL Closure, Writes Off Rs. 244.3 mn

Fornnax Wins AIRIA’s Special Export Award for Rubber Machinery in 2025-26

Cement Prices Likely to Rise Rs. 10-15 per Bag from Mid-October

Nuvoco Marks 10 Years, Targets 35 MMTPA Capacity by FY28

J&K Government Notifies City Gas Distribution Policy
Meghalaya Cabinet Approves MCCL Closure, Writes Off Rs. 244.3 mn
Fornnax Wins AIRIA’s Special Export Award for Rubber Machinery in 2025-26
Cement Prices Likely to Rise Rs. 10-15 per Bag from Mid-October
Nuvoco Marks 10 Years, Targets 35 MMTPA Capacity by FY28
J&K Government Notifies City Gas Distribution Policy
-

 Concrete3 weeks ago
JSW Cement Receives Rs. 2.3 bn GST Demand Notice
-

 Concrete3 weeks ago
Andhra Pradesh Clears Rs. 30 bn My Home Cement Plant
-
 Concrete4 weeks ago
Jammu Division Begins First Cement Rail Traffic to Anantnag
-

 Concrete3 weeks ago
Montra Electric, Wonder Cement Deploy 250-Vehicle EV Fleet