Cement major JSW Cement is increasing installed capacities and moving fast towards becoming a green cement producer and a preferred partner in the construction sector.
JSW Cement, a part of the US$ 13 billion JSW Group, is one of India’s fastest growing cement companies and India’s largest green cement company. It is fast paving way to emerge as a leader in the construction sector, contributing to national projects and strengthening the nation’s infrastructure.
The company is engaged in the manufacturing of cement, clinker and related products, and is one of India’s top five cement companies with a wide portfolio of diverse products and an installed production capacity of 14 million tonnes per annum (MTPA). It has its manufacturing units in Vijayanagar in Karnataka, Nandyal in Andhra Pradesh, Salboni in West Bengal, Jaipur in Odisha, Dolvi in Maharashtra, as well as a clinker plant in Fujairah, UAE. It had acquired Shiva Cement in 2017.
The company has consistently been increasing its revenue and maintaining a strong financial position, despite the onset of the COVID-19-induced pandemic, and remains well positioned to contribute towards AtmaNirbhar Bharat through its world-class cement products. It is positioning itself closer to being listed on the Indian bourses as it moves towards an initial public offering (IPO) towards the end of CY2022. In its quest to be ranked among India’s top five cement players in India and its focus on increasing share of premium products, the Company is expanding its domestic cement manufacturing capacity. With this, it is set to realise its objective of becoming a 25 MTPA producing cement company by 2023.
Notably, within a span of four years, it has more than doubled its manufacturing capacity from 6 MTPA in 2019 to 14 MTPA currently. The cement major plans to augment its capacity mostly through a combination of setting up brownfield and greenfield projects and through inorganic growth opportunities. Currently, it is in the process of adding two cement plants of 5 MTPA each in Rajasthan and Chhattisgarh.
Attracting strategic investors
The company is partnering with new investors to accelerate growth and has begun diluting minority private equity stakes to select investors to accelerate its manufacturing capacity. In December 2021, State Bank of India picked up stake as a strategic investor through the private equity route, done through compulsorily convertible preference shares linked to its future business performance and valuation during IPO.
Prior to this, it raised Rs 1,600 crore from two global private equity investors – Apollo Global Management Inc. and Synergy Metals Investment Holding Limited through a structured private equity deal. Apart from receiving strategic capital to finance growth, these investments are bringing with them deep validation and brand trust. Financing its growth and expansion strategy also positions the company well for its forthcoming IPO.
Geographical diversification
The company has a strong business model with deep market presence in western, eastern and southern parts of India. It has established a reputation of having delivered superior quality products to some of India’s largest and prestigious infrastructural projects in the southern and western regions of the country. With a presence in Telangana, Andhra Pradesh, Karnataka, Tamil Nadu, Kerala, Maharashtra, Orissa, and Goa, it has gained a foothold in the relative markets. The cement company draws its key strengths from the Group’s well-established track record in project execution and cost management.
On the path of being a low-cost producer
The company’s state-of-the-art facilities and technological advancements are helping it expand to new markets and target newer customer segments. The acquisition of Shiva Cement’s clinker and grinding units in Orissa will act as a hub to service its manufacturing facilities across the eastern regions of India. It will provide a strategic advantage to service the needs of its customers in the eastern region and strengthen its leadership position as a green cement producer. The acquisition is targeted at turning the company into a low-cost producer of cement per tonne.
Further, it has also commenced a capex plan at the group level – that of expanding its grinding units at Dolvi, Maharashtra, and Nandayal, Andhra Pradesh. Another grinding unit is being added at Salem, Tamil Nadu. When commissioned, the expansion will help provide clinker to its manufacturing units at Salboni, West Bengal and Jajpur, Orissa at competitive rates, thus bringing down its cost curve.
Captive limestone mines
A significant benefit to the cement company is its ability to procure limestone from captive mines at Kurnool district, Andhra Pradesh, with proven reserves of 134 million tonnes. It has acquired limestone mining rights in Rajasthan, Chhattisgarh and Gujarat. Two years ago, it acquired new milestones in Kutch (125 MT) and Nagpur (205 MT). It has another 300 MT limestone reserve at Fujairah plant, UAE. It also has an agreement with steel players for procuring slag at bulk rates.
Locational advantage
The Company enjoys strategic locational advantage – that of being in close proximity to raw material sources and modes of transport. A majority of its raw materials are manufactured inhouse, and in close proximity to the manufacturing facilities, which gives it greater control over quality and consistency during the manufacturing process. Its target markets of Karnataka, Maharashtra, Andhra Pradesh, Telangana, Kerala, West Bengal, Tamil Nadu, Bihar, Jharkhand, Orissa and Goa are located adjacent to its manufacturing units. Cement being a capital-intensive industry, the locational advantage positively impacts its profitability.
Improving operating efficiency
The Company’s operating efficiency is improving on a consistent basis, largely driven by the sale of portland slag cement and grounded granulated blast furnace slag in southern and western India. The move is likely to result in lower consumption of raw material, power and fuel per tonne of cement. Further, its manufacturing facilities being in close proximity to sources of procuring raw material and its addressable markets also leads to reduction in freight cost. As a result, JSW Cement reported higher EBITDA per tonne of Rs 811 in FY2020 from Rs 700 in the two preceding years. This was facilitated by an increased sale of blended cement and the high-margin ground granulated blast furnace slag. Going forward, driven by improving realisation and receding input prices, the Company is likely to report higher EBITDA per tonne.
Building a greener planet
Strengthened with innovative and sustainable technology, the company is living its vision of being India’s top green cement producer. It has set a strategic roadmap towards achieving best-in-class energy efficiency in production. The company forayed into construction chemicals with the launch of a unique green product range. It has set up a 0.3 million tonne facility at Bellary in Karnataka. It also entered the ready-mix concrete (RMC) market with its first commercial unit in Chembur, Mumbai. This is a part of its larger strategy to increase customer base and offer integrated building material bouquet of offerings comprising cement, construction chemicals and steel with concrete. It maintains a unique focus on green building materials, which positions it as one of India’s leading manufacturers of green ‘sustainable’ cement. It is set to launch its unique eco-friendly concrete for use in commercial construction projects and expand its RMC business in southern and western India.
Growing demand
The demand for cement is set to increase in India owing to the growth in housing, infrastructure, industrial projects. Rise in affordable housing is also set to create rising demand for affordable housing units. Further, as rural housing recovers due to better Kharif season and improved food grain production, demand will further increase.
Benefiting from India’s infrastructure push
The growth potential in the Company is driven largely by the government’s push for large infrastructure projects and a boom in housing construction. India presents an exciting construction and infrastructure story as goes about significantly increasing its allocation for capital expenditure to support its investment cycle. The Government maintains a continued focus on infrastructure and construction sector with higher budgetary allocation year-on-year. During Union Budget 2022-23, Finance Minister allotted ?48,000 crore for housing projects under the affordable housing scheme, further boosting the prospects of cement companies.
The Government is working on upgrading the road length of 1,25,000 km under the National Infrastructure Pipeline (NIP) in the next five years. The NIP has expanded to 7,400 projects from the previous 6,835 projects, paving the way for increased demand for cement.
Key risks
However, JSW Cement’s lower capacity utilisation and limited portfolio diversification is a key worry. Also, the substantial capacity expansion planned exposes the company to risks related to project execution. Further, being in the commodity sector, the company is highly susceptible to volatility in input cost and realisation and also to cyclicality in the cement sector. It is also exposed to volatility in input prices for key components including freight, fuel, power and raw material, which has the capability to impact its Operating Profitability Margin.
Cement manufacturers in India are likely to raise prices by Rs. 10-15 per bag from mid-October, as they seek to offset persistent increases in power and fuel costs. Emkay Research said its channel checks indicated a high probability of an increase from October 12, supported by the start of the busy construction season and favourable demand-supply conditions.
The sector had implemented similar rate adjustments of Rs. 10-15 per bag during the first quarter, but the increases were insufficient to cover higher operating costs. Prices also softened during July and August because of the monsoon, widening the gap between realisations and input expenses. Delayed plant expansion programmes have pushed clinker utilisation rates towards 79 per cent by FY28, helping to balance market fundamentals.
Emkay Research said steady volume offtake was supporting cement consumption, with non-trade demand driving activity across regional markets. Industry volumes are expected to grow by 7-8 per cent year on year during the first half of FY27, while demand momentum is projected to remain firm over the following 18 months. The outlook includes the busy construction season in the second half of FY27 and infrastructure activity linked to general elections in the first half of calendar year 2029.
The brokerage expects overall cement demand to record a compound annual growth rate of about 7 per cent between FY26 and FY28. However, elevated operating expenses are likely to continue weighing on profitability. Input costs have risen by Rs. 300-400 per t over the past six to seven months, with the full impact expected to become visible in second-quarter earnings and remain persistent through the second half of FY27.
Spot prices for petcoke and imported coal are approximately 20 per cent and 16 per cent above their second-quarter averages, at USD 175 per t and USD 150 per t, respectively. Packing costs have also increased, with polypropylene granule prices rising above Rs. 135 per kg. Emkay Research estimated that second-quarter earnings could decline by Rs. 200-250 per t sequentially because of higher fuel bills and negative operating leverage, and said the sector requires sustained price increases of about Rs. 10 per bag to offset cost inflation.
Nuvoco Vistas Corporation Limited is celebrating a decade of operations under the theme ‘Dus Saal Bemisaal’, highlighting its expansion in India’s building materials sector. The company has grown from a single cement manufacturing facility into a diversified organisation operating across cement, ready-mix concrete (RMC) and modern building materials.
The company’s journey began in 2014 when its parent, Nirma Group, commissioned a 2 million metric tonnes per annum (MMTPA) greenfield cement plant at Nimbol, Rajasthan. A major milestone followed in October 2016 with the acquisition of Lafarge India, significantly expanding its manufacturing footprint.
Nuvoco strengthened its market presence through the acquisition of Emami Cement, now NU Vista Limited, in 2020, followed by its public listing in 2021. In April 2025, the company added Vadraj Cement to its portfolio, strengthening its presence in western India.
Nuvoco has an operating cement capacity of 27 MMTPA and 14 manufacturing units, including the Kutch and Sachana facilities in Gujarat, which are in advanced stages of completion. It also operates 58 ready-mix concrete plants across India and offers a range of modern building materials.
The company aims to increase its cement capacity to 35 MMTPA by FY2027-28, representing approximately 15-fold growth over the decade.
Reflecting on the milestone, Hiren Patel, Chairman, Nuvoco Vistas Corporation Limited, said, “From our beginnings at Nimbol to the organisation we are today, every milestone has added a new chapter to Nuvoco’s journey and strengthened our belief in building for the long term.”
The company continues to focus on capacity expansion, operational efficiency, innovation and sustainability while strengthening its position in India’s construction materials market.
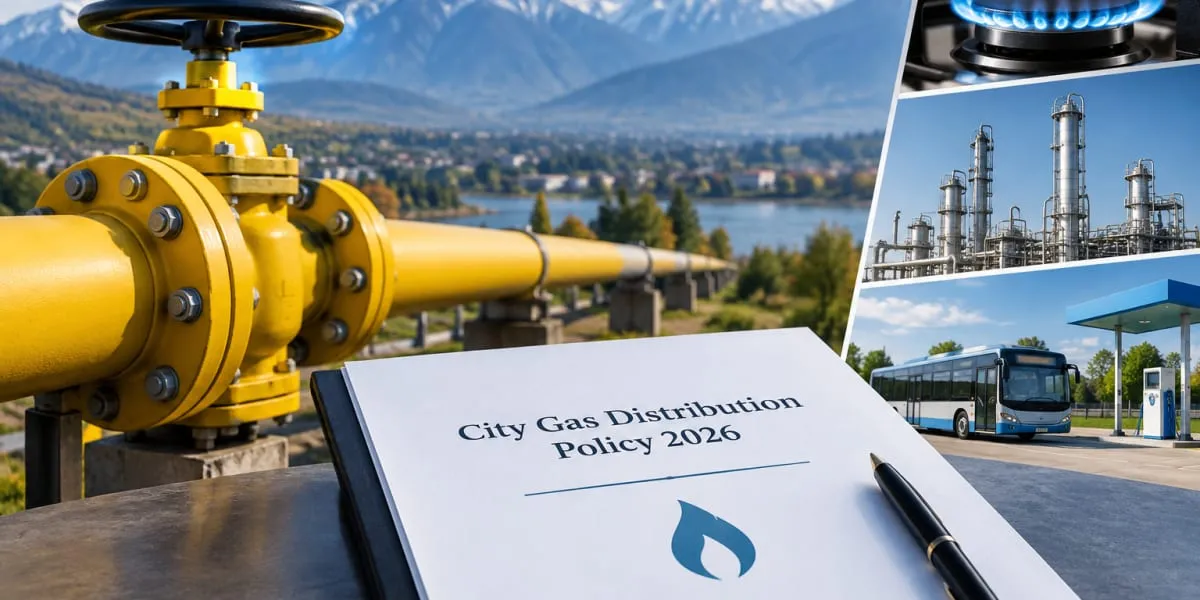
Jammu and Kashmir government has notified the City Gas Distribution (CGD) Policy, 2026, following its approval by the Council of Ministers headed by Chief Minister Omar Abdullah. The policy sets out a phased framework for expanding Piped Natural Gas (PNG) and Compressed Natural Gas (CNG) access for households, businesses, industries and the transport sector across the Union Territory.
CGD networks will be expanded in phases across all 20 districts, with the aim of bringing reliable natural gas closer to consumers and supporting a gradual shift from conventional fuels. The government said the policy is designed to improve energy access while creating an investor-friendly and time-bound environment for gas distribution projects.
The policy provides for single-window and time-bound clearances, streamlined procedures for setting up CNG stations and standardised norms for the Right of Way. These measures are intended to reduce procedural delays, simplify project implementation and facilitate investment in natural gas infrastructure.
It also prioritises gas connectivity for major industrial estates, including those in Kathua, Samba and Pulwama. Improved access to natural gas is expected to support industrial activity, enhance energy efficiency and help businesses manage fuel costs, while strengthening their competitiveness and encouraging investment in the clean-energy sector.
The policy is also expected to create opportunities for local employment, apprenticeships and skill development in the construction, operation and maintenance of gas distribution networks and related services. Abdullah described the measure as an important step towards cleaner growth, sustainable development and a modern energy ecosystem in Jammu and Kashmir, saying it would expand reliable energy access and support industry and investment.













 Concrete3 weeks ago

 Concrete3 weeks ago
 Concrete4 weeks ago
 Concrete3 weeks ago