Economy & Market
If we are provided a level playing field, we can compete with most cement producers
Published
5 years agoon
By
admin
Alok Sanghi, Director of Sanghi Industries
There are three major areas which we are concentrating on: logistics, energy efficiency and balancing the finance cost. This will help us cope with the reduced demand, and at the same time, help maintain profitability, says Alok Sanghi, Director, Sanghi Industries, in a chat with ICR. Sanghi shares his views on the current scenario of the cement industry, the strategies of the company. Excerpts from the interview.
How do you assess the current scenario regarding the Indian cement industry?
Currently, the cement industry is going through a somewhat challenging phase. There is oversupply in the market. The demand rate is also slowing down, putting some supply pressure and price pressure on the cement. We believe that this will continue for another year after which things will start improving; if the government policies take off, the demand should improve faster. The supply- demand mismatch should reduce this year and possibly by 2015, we should see it become equal. As far as we are concerned, the earlier capacity utilisation was 90 per cent. However, in the last couple of years, the ultilisation has come down to 72 to 73 per cent.
Has the slump in demand affected your performance?
Till 2009, we focused on capacity expansion. As there is already an over- capacity, it is illogical to increase capacity further. So our focus is more on cost reduction. There are three major areas which we are concentrating on: logistics, energy efficiency and third is balancing finance. This will help us cope with the reduced demand, and help us maintain profitability.
How has the company kept pace with the latest technologies?
The technology does not change all that rapidly in heavy industries. The only thing is, we need to keep upgrading the efficiency level within our plant, which is what we are doing. The technological advancement which has happened is in the product range. Instead of selling OPC which was the norm earlier the companies are now diversifying into blended cement. So they are making PPC, slag cement, and various other range of blended cement. All this really helps reduce the carbon footprint and achieve the path of sustainability.
What are the sustainability initiatives taken by Sanghi Industries?
We use fly ash generated from the thermal power plants and also use waste from steel plants. By manufacturing blended cements, we are adding to the sustainability of the country. We are one of the few companies in the country using the most eco-friendly mining technique. Instead of drilling and blasting, we use surface miners which have near zero pollution and have dust free emission techniques. Moreover, surface miners help reduces noise pollution. We operate in the region of Kutch where we face a lot of water scarcity, and we have promoted rain water harvesting there.
What are the measures taken by the company to maintain the standard and quality of the cement produced?
Most cement plants have a technical lab and are equipped with the latest technologies to test the product. Since BIS is mandatory in the cement industry, most of the companies maintain the standard. However, we use advanced processes; our equipment vendors are one of the best in the country, in the world. We have an X-ray analyser, a robotic lab, and various other facilities which allow us to maintain quality. We are authorised to sell our product in the European and African markets, thanks to our stringent quality control policies that get upgraded every year.
What was the motive for erecting Terminal C near Navlakhi Port?
The C Terminals are always closer to the markets and that helps give better service. It also helps us to have better control of the freight cost. In a nutshell, investing in the C Terminal helps reduce costs considerably. Wherever we have invested in C terminals we have saved about 20 per cent of costs. So we are very confident about this strategy. The sea route will be used to cost-effectively increase our geographical reach and grow our markets. At present, the company is serving Gujarat, Rajasthan, Madhya Pradesh and Maharashtra. The focus is to expand in the central and western regions, and in the coastal states.
What are challenges facing the cement industry currently?
The greatest challenge today is managing the demand-supply mismatch. The spiralling raw material costs, including coal and diesel, are other major challenges. The rise in the price of coal is due to the depreciating rupee, which is why we need to invest more in energy-efficient equipment.
What support would you require from the government at the policy level?
The excise duty on steel is just four per cent whereas for cement it is 12 per cent. My question is why should there be such a difference in excise duty between two building materials which are used for the same purpose? Ultimately, the cost of housing is increasing because of the increase in taxes. If you look at the ex- factory cost of cement and if you add the taxes which we are paying, it is equivalent to the luxury goods; and cement is essential goods. So I think the government really needs to focus on how they can reduce the cost of cement, either by reducing the royalties, or reducing the excise duty, VAT, etc.. As per my view, the most important thing the government can do is to increase the percentage spent on infrastructure development. For example, China spends almost 12 per cent of its GDP on infrastructure development whereas India spends less than 5 per cent of its GDP. So if the government increases its infrastructure spend, it will automatically have a huge impact on the demand for cement and that obviously will help in capacity utilisation.
There seems to be lot of demand for Pakistani cement. The general perception is that it is of better quality and cheaper too. What is your take on this?
I completely disagree with this. Pakistani cement is no way cheaper than Indian cement. It is the taxes that you pay that make the difference. When you import cement, the amount of taxes you are paying is less than what an Indian cement producer is paying. The government is giving a subsidy to Pakistani cement in form of exemption of taxes. Indian cement manufacturers are not permitted to sell cement in Pakistan, so should our government provide subsidy to cement manufacturers from Pakistan? Whatever facilities or provisions are being provided by the Pakistani government should be reciprocated by the Indian government. Or let us say, even if you are allowing Pakistani cement to come into India, put them on a level playing field; peg them at the same tax levels which we are subjected to, and then I don’t think there will be any problem in competing. But let me also tell you, the world over, we are competing with Pakistani cement, Iranian cement… Thailand, Malaysia, China, Japan etc. Indian cement quality is one of the finest in the world and is therefore widely accepted across the world. We are one of the largest exporters; and the technology we use is the latest in the world. So if we are provided a level playing field, we can compete with most cement producers.
Brief us about the company’s future plans.
We are not focused on expansion, since the companies are already on an expansion mode but are interested in ensuring that we are more profitable; thereby, the company is focused on reducing its debt, energy consumption and improving its logistics cost. These are the three focus areas for the company. However, to sell its additional volumes, we are looking at expanding our market. We are also opening up some markets in the south and going to MP.
Are there any acquisitions on the cards?
No, nothing really. We don’t have any plans to either acquire or diversify from cement as of this moment. The next two years will be a consolidation phase for the cement industry and we are very keen to remain in this business. I believe it is ultimately survival of the fittest. You must survive this downturn to even consider expansion and things like that.
You may like
-
Double Tap to Go Green
-
15th Cement EXPO to be held in March 2025 in Hyderabad
-
14th Cement EXPO
-
Vinita Singhania receives Lifetime Achievement Award at the 7th Indian Cement Review Awards
-
Increasing Use of Supplementary Cementitious Materials
-
Indian Cement Review Touts Decarbonisation Mantra & Awards Growth
Concrete
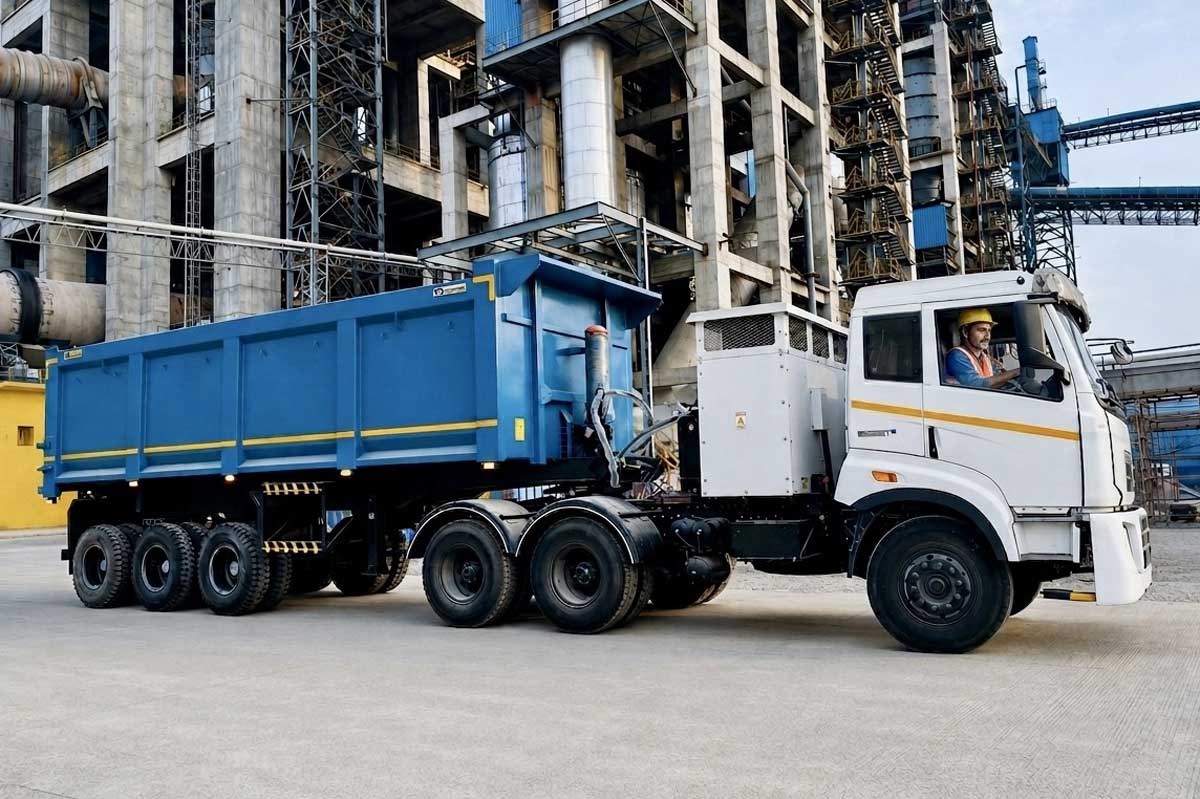
UltraTech Cement expands green logistics with 600+ electric truck fleet
Published
1 week agoon
September 3, 2026By
admin
The e-truck fleet will be used to transport five million MT of clinker and other key materials with potential of over 1,17,000 tonnes of net annual CO₂ reduction, displacing the equivalent of 39 million litres of diesel per year.
Mumbai
UltraTech Cement Limited, an Aditya Birla Group company and the world’s largest cement company by sales volume and capacity outside China, has announced that it will scale up its electric vehicle fleet in its logistics operations to 600+ EV trucks by December 2026.
UltraTech has signed service contracts with leading EV prime mover manufacturers including Tata Motors, Ashok Leyland, IPLTech, Energy in Motion and Sany, along with their subsidiaries and other third-party logistics providers, to deploy EV trucks.
The total fleet of 600+ EV trucks will transport about five million MT of clinker and other key materials per annum across Gujarat, Uttar Pradesh, Madhya Pradesh, Rajasthan, Chhattisgarh, Maharashtra and Odisha. Once fully operational, this fleet of over 600 EV trucks will enable a net annual CO₂ reduction of more than 1,17,000 tonnes, displacing the equivalent of 39 million litres of diesel per year.
K C Jhanwar, Managing Director, UltraTech Cement Limited, said, “UltraTech is expanding sustainability beyond its plants by adopting greener logistics solutions. This large-scale transition to green logistics underscores our focus on decarbonising every link of our value chain and supports our commitment to achieving Net Zero.”
UltraTech has been a pioneer in advancing sustainable transport in the cement sector, being the first cement company to deploy heavy-duty electric trucks for long-haul transport of clinker and other materials at scale. The company was among the first in India to introduce green logistics, deploying CNG trucks in 2021 and electric trucks in 2024. UltraTech currently operates 850+ trucks as part of its green logistics operations, including CNG and electric trucks.
UltraTech, with a grey cement capacity of over 200 MTPA in India, operates one of the country’s most complex logistics networks. Its electrification strategy covers the entire supply chain—from mine-to-plant movement to inter-plant transport of clinker and other key materials.
The $ 10 billion UltraTech, the cement flagship company of the Aditya Birla Group, has a total Grey Cement capacity of 205.5 MTPA and White Cement/Putty capacity of 3.2 MTPA. It is a signatory to the GCCA Climate Ambition 2050 and has committed to the Net Zero Concrete roadmap announced by GCCA.
In a research-backed article, Dr SB Hegde examines why carbon-adjusted profitability and LC3 will decide the next set of winners in cement manufacturing.
The Indian cement industry has achieved world-class operational efficiency through lower specific energy consumption, high plant utilisation and a reduced average clinker factor of approximately 67.5 per cent. These traditional measures of operational excellence remain essential. However, they are no longer sufficient. Carbon now carries a measurable financial cost under India’s Carbon Credit Trading Scheme (CCTS) and under European carbon markets. Future leadership will be defined by carbon-adjusted profitability, the ability to generate strong returns while systematically lowering the carbon intensity of every ton sold.
Limestone calcined clay cement (LC3) offers a practical, scalable pathway to achieve this dual objective. By replacing up to 50 per cent of clinker with calcined clay and limestone, LC3 can reduce CO2 emissions by 30–40 per cent while delivering comparable or superior durability performance.
This article examines the technical foundations of LC3, European industrial practices, the emerging Indian carbon market and a concrete roadmap for Indian companies to embed carbon-adjusted metrics and LC3 into daily operations, incentives and commercial strategy.
Limits of traditional operational excellence
For many years, plant performance has been judged primarily by five indicators: specific heat consumption, specific power consumption, kiln and mill utilisation, clinker factor and overall equipment effectiveness. These metrics drove continuous improvement and helped the industry reduce energy use and increase the share of blended cement. Three structural changes have rendered them incomplete as sole measures of success.
First, carbon now carries a real or opportunity cost. Plants that improve volume or lower cash cost while raising or stagnating emissions intensity create a hidden liability that will surface as CCTS trading matures and as green procurement expands.
Second, lower-carbon products such as LC3 and high-performance blended cements are creating differentiated market segments. Customers in infrastructure, real estate and export-oriented construction are beginning to specify embodied-carbon limits.
Third, investors and lenders increasingly treat carbon intensity as a financial risk factor. Traditional KPIs can mask the divergence between short-term cash profit and long-term carbon-adjusted value.
What is carbon-adjusted profitability?
Carbon-adjusted profitability evaluates normal profit after explicit adjustment for carbon performance. A practical expression is:
Carbon-Adjusted EBITDA = Conventional EBITDA – Carbon Cost + Green Premium Income
Carbon cost may be an internal carbon price, the actual cost of purchasing Carbon Credit Certificates under CCTS, or the opportunity cost of high emissions relative to peers. Green premium income arises when customers pay more for verified lower-carbon cement or when the company sells surplus credits. Tracking both conventional and carbon-adjusted profit side-by-side gives management a clearer picture of value creation under evolving market rules.
Table 1. Traditional KPIs versus Carbon-Adjusted Leadership Metrics
Traditional Focus New Leadership Metric Why It Matters
Specific energy consumption Emissions intensity (kg CO2/t cement) Directly linked to future CCTS and CBAM costs
Kiln utilisation Carbon-adjusted contribution margin Reveals true value of incremental volume
Clinker factor Share of lower-carbon products sold (incl. LC3) Measures commercial success of the transition
Power cost per tonne Effective carbon cost per tonne sold Expose hidden liabilities
Absolute EBITDA Carbon-adjusted EBITDA + green premium Aligning profit with future market reality
LC3: Technical foundations and performance advantages
LC3 is a ternary blended cement that typically combines approximately 50 per cent clinker, 30 per cent calcined clay, 15 per cent limestone and 5 per cent gypsum (the classic LC3-50 formulation). The decisive technical advantage is that clay is calcined at 700–850 °C, far below the 1,450 °C required for clinker production. This lower temperature, together with the substantial reduction in clinker content, delivers CO2 reductions of 30–40 per cent relative to ordinary Portland cement (OPC).
Chemistry is synergistic. Calcined kaolinitic clay (metakaolin) reacts with calcium hydroxide from clinker hydration and with limestone to form additional C-A-S-H gel and carboaluminate phases. These phases densify the microstructure, reduce porosity and improve durability.
Field experience shows superior resistance to chloride ingress, sulphate attack and alkali–silica reaction. Early-age strength can match OPC with high-reactivity clays; later-age strengths routinely meet 42.5 and 52.5 grade requirements.
Importantly, LC3 does not require high-purity kaolin. Clays with 40 per cent or even lower kaolinite content can be activated successfully, expanding raw-material availability across India. Calcination can use adapted rotary kilns or dedicated flash calciners, making the technology compatible with existing plant infrastructure and far less capital-intensive than carbon capture.
Economic analyses show that LC3 can be produced at equal or lower cost than OPC in many locations because of reduced energy demand and cheaper clay. Life-cycle assessments consistently report 30–40 per cent lower embodied CO2 per tonne of cement.
Table 2. Comparative profile: OPC versus LC3-50
Parameter OPC LC3-50
Typical clinker content ~95 per cent ~50 per cent
CO2 emissions (relative) Baseline (≈0.85 t CO2/t cement process + fuel) 30–40 per cent lower
Clay calcination temperature Not applicable 700–850 °C
Key hydration products C-S-H, portlandite, ettringite C-A-S-H + carboaluminates
Chloride & sulphate resistance Good Superior
Production cost potential Baseline Equal or lower in most locations
Infrastructure compatibility Existing High (minor adaptations)
In India, commercial adoption has begun in earnest. JK Cement commenced the first commercial production of LC3 in the Indian subcontinent at its Mangrol plant in Rajasthan in 2025 under BIS standard IS 18189.
By early 2026, approximately 2,000 tonnes had been produced and sold, avoiding an estimated 500 tonnes of CO2. JK Lakshmi Cement followed with commercial launch of its Green PRO LC3 grade from the Jaykaypuram plant. As of mid-2026, two producers are supplying LC3 to the market. The first large-scale infrastructure application is the Noida International Airport (Jewar), where LC3 was used in the runway and a building complex, demonstrating full constructability and performance under demanding conditions. These early volumes are still small relative to national cement demand, but they mark the critical transition from pilot to commercial reality. Companies that scale capacity now will be positioned to capture both CCTS credits and emerging green-procurement demand.
Why the shift is accelerating
According to the World Bank’s State and Trends of Carbon Pricing 2026, direct carbon pricing now covers nearly 30 per cent of global greenhouse-gas emissions and generated more than US$107 billion in public revenue in 2025. The average global carbon price stands at approximately US$21 per tonne, although regional prices vary widely.
In Europe, the EU ETS price has traded near €80–85 per tonen in mid-2026. Free allocation for cement is being withdrawn in parallel with CBAM. European producers therefore face a clear signal: every tonne of avoided CO2 improves both compliance and competitiveness. Holcim has scaled calcined-clay production, including Europe’s first dedicated line at Saint-Pierre-la-Cour (France) and a second line in the Czech Republic (2026). Heidelberg Materials, Cementir (FUTURECEM) and others have commercialised low-clinker calcined-clay blends across multiple markets, showing that carbon-adjusted profitability is already reshaping capital allocation in the world’s most mature carbon market.India’s CCTS is now operational. Binding emission intensity targets apply to 186 cement facilities for FY 2025–26 and FY 2026–27. Average required reductions for integrated plants are modest (around 2.7 per cent by FY 2027), yet the direction is clear.
Trading of Carbon Credit Certificates is expected in the second half of 2026, with early prices likely in the `800–1,500 per tonne range. Plants that outperform targets can sell credits; those that underperform must buy them or face compensation. Cement is well positioned to be a net supplier of credits if clinker factor continues to fall through LC3 and other low-clinker systems.
Way forward for India
India starts from a strong baseline, world-class energy efficiency and a clinker factor already lower than the global average. The next competitive frontier is the deliberate reduction of process emissions through clinker substitution at scale. LC3 is uniquely suited to Indian conditions because suitable clays are widely distributed, the technology fits existing kiln and grinding infrastructure, and the resulting product can meet the performance demands of both infrastructure and building construction.
A practical national pathway contains five interlocking elements:
- Standards and acceptance: Accelerated finalisation and promotion of BIS specifications for calcined-clay and limestone–calcined-clay cements will remove a key barrier to commercial uptake. Alignment with European practice (EN 197-5) can facilitate knowledge transfer and export readiness.
- Supply-chain development: Investment in flash calcination capacity and systematic characterisation of regional clay deposits will secure reliable, low-cost feedstock. Existing rotary kilns can be adapted for initial volumes while dedicated calciners are built.
- Incentive alignment: Part of variable compensation for plant managers, sales teams and senior leadership should be linked to emissions intensity reduction and to the volume of lower-carbon products (including LC3) sold. Without this link, traditional volume and cost targets will continue to dominate behaviour.
- Product-level carbon accounting: Reliable measurement of emissions intensity at the individual cement grade level, supported by third-party verification where required, is essential for both CCTS compliance and credible green claims.
- Demand-side pull: Green public procurement policies that specify maximum embodied-carbon thresholds for major infrastructure projects will create a predictable market for LC3 and other low-carbon cements, accelerating scale and cost reduction.
Companies that treat LC3 as a strategic product line rather than a niche offering will be better positioned to generate surplus Carbon Credit Certificates, capture any emerging green premium, and protect margins as carbon costs rise.
Organisational changes required
Technical capability alone is insufficient. Three organisational shifts are required.
Daily management: Emissions intensity must appear on the same daily and monthly dashboards as heat consumption, power consumption and utilization. Plant reviews should examine both conventional and carbon-adjusted results.
Incentives: A meaningful portion of bonuses for plant heads, technical teams and sales leadership should be tied to lower emissions intensity and successful commercialisation of LC3 and other low-carbon grades.
Commercial approach: Sales teams need clear volume and pricing targets for lower-carbon products, supported by technical service that helps customers specify and place the material correctly. Without commercial pull, excellent technical performance remains under-utilised.
Table 3. Three-stage roadmap to carbon-adjusted profitability
Time Horizon Priority Actions Expected Outcome
Next 12 months Add emissions intensity to plant dashboards; establish internal carbon price; initiate LC3 pilot production and customer trials Visibility and early organisational learning
12–24 months Revise incentive systems; scale LC3 and other low-carbon grades to key accounts; secure third-party verification capability People and sales aligned with carbon goals
24–36 months Embed carbon-adjusted metrics in board reporting and capital allocation; expand calcined-clay capacity Full system integration and competitive advantage
Questions senior leaders should ask
Boards can accelerate the transition by insisting on answers to a short list of questions:
• Is our carbon-adjusted profit improving, stable or declining relative to conventional EBITDA?
• Did recent volume growth improve or worsen our emissions intensity?
• What share of sales already comes from lower-carbon products, including LC3, and what is the trajectory?
• How exposed is our capital expenditure plan to rising carbon costs under CCTS and potential CBAM-related requirements?
• Do our incentive systems still reward only volume and cost, or have they been updated to include carbon performance?
Treating carbon with the same seriousness as energy cost or kiln utilization does not diminish operational excellence; it expands the definition of excellence to match the new competitive reality.
Looking ahead
By 2030 the gap between leading and lagging cement companies will not be decided by who records the lowest specific heat consumption. It will be decided by who delivers the strongest carbon-adjusted profits.
Absolute emissions may still rise as national production grows. That is not the issue. Companies that reduce intensity year after year and successfully sell cleaner products will pull ahead in both domestic and export markets. Those that do not will fall behind, even if their traditional efficiency numbers look strong.
Operational excellence built the Indian cement industry. It remains the foundation. It is no longer the complete picture. Carbon-adjusted profitability is the clearer measure of success.
LC3 is not a distant technology. It is available now. It cuts CO3 by 30–40 per cent, works with existing plants, and is already in commercial production in India. Companies that treat it as a strategic product, not a pilot, will protect their margins and generate tradable credits.
Leaders who act now will place carbon metrics on daily dashboards, link incentives to intensity reduction and LC3 sales, invest in calcined-clay capacity, and build commercial capability to sell lower-carbon products. They will shape the next chapter of the industry.
References
- World Bank. (2026). State and Trends of Carbon Pricing 2026. Washington, DC: World Bank Group.
- International Carbon Action Partnership (ICAP). (2026). India Carbon Credit Trading Scheme – Status and Coverage. Berlin: ICAP.
- Ministry of Environment, Forest and Climate Change / Bureau of Energy Efficiency. (2025). Greenhouse Gases Emission Intensity Target Rules, 2025. New Delhi: Government of India.
- Scrivener, K., Martirena, F., Bishnoi, S., & Maity, S. (2018). Calcined clay limestone cements (LC3). Cement and Concrete Research, 114, 49–56.
- RMI. (2024). The Business Case for LC3. Rocky Mountain Institute.
- European Commission. (2026). EU Emissions Trading System – Allowance Price Data and Free Allocation Phase-out Schedule. Brussels.
- Holcim. (2025–2026). Scaling Calcined Clay for Sustainable Building – Corporate Updates on European and Latin American Capacity. Zurich: Holcim Ltd.
- LC3 Project / EPFL. (2026). LC3 – A Guide to Best Practices for Scalable, Affordable and Sustainable Low-Carbon Building. Lausanne: École Polytechnique Fédérale de Lausanne.
- Business Today / Industry Reports. (2026). First Large-Scale LC3 Application at Noida International Airport, Jewar. New Delhi.
- NITI Aayog / Industry Analyses. (2026). Roadmap and Baseline Performance Indicators for the Indian Cement Sector. New Delhi.
- Springer / Innovative Infrastructure Solutions. (2026). LC3 Systems: A Review of Chemistry, Performance, Durability and Sustainability toward Market Adoption.
- Cementir Holding / Industry Sources. (2025–2026). FUTURECEM and Related Low-Clinker Technologies in Europe.
- Climate Risk Horizons & Independent Analyses. (2026). Assessment of Emission Intensity Targets under India’s CCTS for Cement and Other Hard-to-Abate Sectors.
- GCCA / TERI. (Various years). Decarbonization Roadmaps for the Indian Cement Industry.
- EN 197-5:2021. Cement – Part 5: Portland-composite cement CEM II/C-M and Composite cement CEM VI. European Committee for Standardization.
Concrete
More Oversight Makes Cement Plants Less Safe
Published
2 weeks agoon
August 28, 2026By
admin
Dijam Panigrahi makes a counterintuitive but data-backed argument that routing every sensor alert through human approval does not make cement plants safer.
India’s cement industry has spent the last two years wiring kilns, mills and coolers with sensors and automated control systems, and the safety case for doing so is strong on paper. Contract workers still make up the majority of the industry’s workforce, and fatal accidents remain a recurring problem. The Indian National Cement Workers Federation has noted that around 83 per cent of workers in the sector hold precarious positions, a fact that resurfaced after an oxygen cylinder explosion killed three contract workers at a plant in Chhattisgarh.
Industry tallies compiled by IndustriALL found cement plants recorded at least seventeen accidents in one year with 21 workers killed, and ten accidents the following year with nine killed, most of them contract staff. Automated monitoring, in theory, closes that gap. A sensor never gets complacent and never skips a check because a shift is short staffed.
However, plants that respond by routing every anomaly reading to a person for approval are quietly building a system that fails the same way understaffing does. When operators receive dozens of flagged deviations a shift, most of them minor, they learn a simple lesson: the fastest way through the queue is to approve without reading closely. The safety benefit disappears, not because the technology failed, but because the humans supervising it adapted to the volume.
Why alerts get ignored
A study cited by manufacturing technology publisher Applied SmartFactory found more than 95 per cent of alarms in a semiconductor fab were low priority, and only about 4 per cent ever triggered an action, with just 100 out of 5,000 alarms accounting for 70 per cent of all alarm activity. The mechanism is the same whether the trigger is a vibration sensor or an AI model flagging a kiln temperature swing. Once the ratio of noise to signal crosses a threshold, workers stop treating the system as a decision aid and start treating it as a formality to clear.
The scale of AI deployment underway makes this more than a theoretical risk. Stanford’s 2026 AI Index Report found organisational adoption of AI has reached 88 per cent, even as documented AI incidents rose to 362 in 2025, up sharply from 233 the year before, according to analysis of the report. The Index also found only about a third of organisations have adopted a formal governance framework, with NIST’s AI Risk Management Framework cited by 33 per cent and ISO/IEC 42001 cited by 36 per cent.
Most manufacturers are deploying monitoring systems faster than they are building the judgment for when a flagged event actually needs a person’s attention. In India, plants run by JK Cement have begun pairing CCTV feeds with AI to define safe zones around heavy machinery, a promising direction that still depends on operators trusting and reading the alerts the system generates.
A three-tier model for cement plant
The fix is not less monitoring or more monitoring. It is classifying decisions by risk and by novelty, rather than treating human oversight as a single switch that is either on or off. A workable model sorts factory floor events into three tiers.
The first tier, proceed, covers deviations the plant has seen before that fall within known safe bounds, such as a kiln feed rate adjustment within an established range. These should run without a stop for approval, because routing them to a person only trains that person to click through.
The second tier, pause, covers events that are unusual but not yet dangerous, such as a vibration reading trending toward a limit or a fuel blend shifting outside its typical mix. These warrant a brief human check before the system proceeds, giving an operator the chance to apply judgment the model does not yet have.
The third tier, escalate, covers events that are both high risk and unfamiliar, such as a pressure reading combined with a temperature spike that has no close precedent in the plant’s history. These should stop the process entirely and require a decision from someone with the authority to shut down a line.
Who should set the threshold
Where these tiers get drawn matters as much as the framework itself. Threshold setting is frequently handed to the vendor supplying the monitoring software or to a plant’s IT department, both of which understand the technology but not the specific tolerances of a given kiln, mill or line. Operations staff, who know that a particular grinding unit runs hotter under monsoon humidity or that a calciner behaves differently after a refractory reline, are better positioned to calibrate what counts as routine on their own equipment.
Handing threshold ownership to operations does not remove IT or vendors from the process, but it puts the calibration decision closest to the people who live with its consequences on the floor.
Signals that oversight is actually working
A few concrete indicators reveal whether a monitoring setup is functioning as intended or simply providing the appearance of safety. The escalation rate over time is the first: a rate that stays flat or climbs slowly as operations mature is healthy, while one that spikes and then falls sharply often means operators have started overriding the system rather than engaging with it. Time to resolution is the second: escalations that take progressively longer to close suggest fatigue or confusion about ownership, not diligence. The third, and most telling, is how accurate the system’s own uncertainty estimates turn out to be, meaning whether events flagged as high risk actually correlated with real incidents, and whether events waved through stayed incident free. A system whose escalations do not track with actual outcomes trains operators toward the same complacency that unmonitored equipment produces.
None of this argues against automation in Indian cement manufacturing, where a labor structure built on contract work and a track record of serious accidents make better monitoring an urgent need. It argues for treating human oversight as a design problem with three distinct settings, rather than a single
dial turned up whenever a plant wants to look safer on paper.
About the author:
Dijam Panigrahi, Co-founder and COO, GridRaster, is a spatial computing platform for industrial enterprises and manufacturers.
Cement Demand Strong As Prices Remain Stable
Aditya Birla Group Launches Ultravolt Wires And Cables Business
Ramco Cements Mine Restoration Gets Global Biodiversity Certification
Central Technical Team To Survey Sites For Bhadradri Kothagudem Airport
Kirby India Breaks Ground on Fourth PEB Plant in Tamil Nadu
Cement Demand Strong As Prices Remain Stable
Aditya Birla Group Launches Ultravolt Wires And Cables Business
Ramco Cements Mine Restoration Gets Global Biodiversity Certification
Central Technical Team To Survey Sites For Bhadradri Kothagudem Airport