Connect with us

Economy & Market

“Railways consider private terminals as their competitors”

Published

on

Shares

Yogesh Mehta Joint Vice President – Commercial, Shree Cement

Government policies must be so framed as to encourage bulk cement transport in India. There are many ways to boost logistical efficiencies at plant and government level. Yogesh Mehta shares with ICR what Shree Cement is doing at its plant and how the government can help to do more. Excerpts from the interview…

How much is the contribution of the logistical expenses to the cost of the product? How can one reduce this cost?
Logistics is one of the major cost contributors to cost and has significant influence on the final price of the product. Factors leading to the high cost mainly include transportation and warehousing costs, maintaining distribution networks and the expenses of procuring raw materials. Overall the cost amounts to almost 25 per cent of final cost of product.

There is a need to identify major cost drivers in logistics and to replace traditional forms of cost allocation structures with more appropriate methods. Well organised logistics management can have significant impact on overall return on investment and ultimately bring value to the stakeholder.

To reduce logistical expenditure, the cement industry can adopt the following measures:

  • Encourage big cement users for bulk/loose cement transport. This will reduce packing cost and is also eco-friendly. It is beneficial for both – the seller and the buyer
  • Establish grinding units, blending or packing units in big market area for direct delivery of materials
  • Plan dispatches in a way that reduce rail freight/rail freight on return journeys availed for procurements
  • Maximise dispatches directly to the end user so that warehousing/distribution cost can be reduced, and
  • Optimise truck size/fleet capacity, timing of vehicle engaged in cement and raw material loading, unloading as well as the transit time, so that operational cost of vehicle is reduced by maximising efficiency of every trip made by the vehicle.

How do you synchronise your production volume with respect to fluctuating market demands?
Looking at the nature of cement commodity, no one can produce excess and store it for long period. Hence all cement industries plan their production according to their sale projections/targets. Being a smart producer of cement, the industry maintains cement stock just sufficient to meet the demand for next to 2-3 days at production centre and similarly a stock of 2-3 days in kept in transit and at godowns. So on an average the company maintains around 5 days stock to absorb fluctuations in a timely manner.

Besides that, most importantly, extra cement grinding capacity can be planned while setting up various production units based on future projected demand/fluctuation.

What are the problems faced by the cement industry in the last mile delivery?
Hurdles in last mile delivery may be classified as encountered with big and small consumers. Both have different types of problems, which need to be resolved in manner that ensures that the deliveries are made in minimum lead time. These challenges are as under:

Big consumer:

  • Maintaining supply according to their consumption schedules
  • Cement storage constraints at consumption sites
  • Labour unavailability and unloading issues at night
  • Sudden spurt in demand in short of period making it difficult to arrange vehicles for transport, and
  • Lack of rail wagons for small delivery for far-off destination, where road delivery is not feasible.

Small consumer:

  • Meeting demands of small quantity with minimum lead time
  • Requirement of product at remote locations, and
  • Lack of storage space.

The problems mentioned above can be tackled by doing well-planned supply co-ordination with consumer, supported by strong logistic backbone having commitment towards costumer?s satisfaction. Big consumers have their own planning of consumption which is fulfilled from plant directly by adopting any mode, i.e., rail or road. To overcome storage issues, stock on wheels is one of the best options considering unloading of cement vehicles within stipulated time frame with excellent coordination with consumer. However, small users may be served better by the cement dealer networks or from nearest warehouses. Therefore such delivery networks/warehouses need to be situated at strategic locations from where supply can be made effectively.

In SCL, we encourage regular and big consumer to use bulk (loose) cement, which can be stored easily in vertical silos with minimum requirements. Here we faced a hurdle where the bulk cement users were not able to use their existing compressor facility. The pumps were not compatible with all of the individual bulk carrying vehicles. To overcome this, we have installed compressors mounted on mobile vans.

By using loose cement, customers, industry and builders can reduce their dependency on manual intervention to a great extent. The labour involvement in cement bag unloading as well as feeding in silos could be avoided.

To give delivery at long distances, SCL has established cement production units near consumer areas, from where multiple consumer deliveries are clubbed together for last mile delivery with minimum lead time.

Bulk cement small deliveries are also catered through bulk cement loading terminal, where customers can take loose cement delivery in short lead time and in small lots as per their convenience. In this way all customers are served by SCL in the loose cement too. SCL is one of the leaders in implementing eco-friendly initiatives. The company has converted PP bag-using consumers into bulk cement users.

How do you ensure that your fleet is performing at its best?
There is a variety of vehicles that ply cement for us. Some vehicles are dedicated for cement dispatches, which form 80 per cent of the fleet. The rest of the cement dispatch is done through return vehicles, which normally ply in open market. Market trucks are attracted to us due to surety of load availability, i.e., assurance. Dedicated vehicles require load planning with lowest turnaround trip time. So the optimum use of vehicles achieved by maximum quantity loaded to earn more revenue in defined period serves as an incentive to them. In SCL?s case, we have a fixed size of our truck fleet that plies on our dedicated route dispatches. After restricting the number of trucks (by reducing fleet strength by 25 per cent), we observed that the rate of vehicle utilisation has improved. Now maximum quantity is dispatched using minimum number of vehicles. As a result, our benchmarking freights are achieved as well as revenue to truckers has also increased.

To further improve the performance of the fleet, SCL increased laden run km of vehicles by 9 per cent in last fiscal year, i.e., 53 per cent in FY 2013-14 from 44 per cent in FY 2012-13, by providing return load of raw material to dedicated fleets. This ensures increased revenue for every run km.

Also, while ensuring dedicatedly fleet performance, SCL encourages market fleet to approach SCL?s independent/impartial reverse freight bidding system, in which they can decide their own revenue, as result of their own choice routes available for transit.

Do you think that it is a good idea to outsource logistical functions?
Looking at the huge involvement of logistics cost in total cost of product, at first instant the obvious answer is NO to outsource logistical functions in SCL. In logistic function huge dedication is required for customer satisfaction which is possible with personal involvement only, with an object of cost reduction.

By outsourcing, it is not necessary that we get financial benefits but on the contrary, purity of work and quality of service both may disturb or get affected and the result may not up to the mark. Scarcity of expert and experienced employees will always be there since none of the outsourced party will give preference to priority work in a dynamic company which is objective/essence of logistics. Secondly the pipeline of experienced manpower, in a growing organisation which has need of expert people, will become dry because outsource people do not necessarily have cultural acquaintances.

How do you assess the potential of coastal shipping and IWT? What are the major hurdles that dent the growth potential of IWT?
Coastal shipping can be a very good option for reduction of cost for plants located close to water bodies. However, there is an unmet need of small jetties for delivery at unloading point as well as connecting with road to consumption centres across coast. In Bihar, industries are located in Southern region, but the main consumer market of Bihar lies in north. As of now no infrastructure is available to let heavy commercial vehicles cross Ganges River, except rail, which is already insufficient to meet the growing demand.

IWT has very good potential in India. IWT can be used where we have limitations in road/rail transportation, but are blessed with plenty of rivers and other water bodies. SCL is one of the first cement companies to associate with Inland Waterways Authority of India (IWAI) to move cement trucks via waterways by Roll on-Roll off of trucks from vessels. IWAI provides facility for cement laden trucks to disembark vessels at Patna (South Bihar) and then roll-off at Chhapra road (North Bihar) accounting to a lead distance reduction by 60 km. This not only conserves natural resources like fuel but also prevents congestion on overburdened road/rail infrastructure.

To make IWT a success, the government is expected to build the infrastructure of small loading and unloading jetties through IWAI as-well-as dredge the river channels regularly. The government should provide freight subsidy for using IWT to encourage its use at large scale.

Why has cement transport via BCCW not picked up that well in the country?
In India, the use of bulk (loose) cement is not as popular as it is in the international market. Compared to packed cement, use of bulk cement is just 8-9 per cent since no infrastructure or encouragement is provided for bulk cement transport and use. BCCW transport to be economically viable requires minimum order size of 3000+ MT of cement in one way single trip and the wagon must bring back fly ash from the nearest source from the cement dispatch point. Consumers are not always located near to the railway line. Cement companies have to establish packing units at rail site to take two way advantage. Since two way movement of cement and fly ash cannot be done on rail line, use of BCCW has not yet picked up in India.

There is lack of co-ordination amongst government enterprises both at the Centre and at State level. The Railways department should develop industrial parks along the rail terminals jointly with the state governments. The suggestions for rail terminal location should be invited from industrial organisations. As government initiative, a high level coordination committee should be formed, consisting of experts from industry, railway, and the Centre and State governments with an objective to promote return logistic in railway.

This initiative will develop many industries at a small cost of coordination. Cement industry alone cannot bear the cost of huge fly ash evacuation system at power plant. It should be a part of the government policy for power project?s in-built approvals that they should compulsorily develop fly ash filling system at their railway siding for BCCW type wagons.

The cement industry can develop infrastructure at their plants, but they cannot build infrastructure at fly ash sourcing point. Huge costs are involved at factory level for creation of storage silos for cement/fly ash, with compressor and transportation system from rail siding to their main plant.

What are the hindrances in setting-up private rail terminals?
Basic hindrances in setting-up private terminals are as under:

  • Discouraging policies of railways towards private terminals. It is as if railway considers private terminals as their competitors, instead as supporters who will take on the load from overburdened rail system.
  • Long and difficult approval process prevalent at various railway departments where approvals are required separately from commercial, technical, civil, rail transporter department, etc.
  • Difficulties inland acquisition and high lease licensing for railways land for siding takeoffs.
  • Clearances from various government bodies, i.e., road/highways authorities for ROB and RUB, State Electricity Boards for relocation of cable tower, etc. Take too much time.
  • No incentive is offered by railway for cost recovery of infrastructure created by private terminals. Earlier Rs 40/- PMT was committed by railway as terminals charges but they have been withdrawn unexpectedly.

The Liberalised Wagon Investment Scheme (LWIS) seems to be skewed in favour of Railways. What is your take on this and what needs to be done?
LWIS policy does not correlate with huge investment. A wagon costs around Rs 60 lakh, whereas railway policy gives rebate on railway freight instead of ensuring return on investment (ROI) for a wagon. Only if the scheme is modified by way of freight rebate to investment based return will the LWIS be successful. Even if railway plans to give return by way of freight rebate then they have to ensure free movement of wagons on railway infrastructure, without any restriction. The freight rebate should match ROI at 15 per cent. This will help LWIS serve its true purpose.

Cement being the 3rd largest revenue earner for Indian railways, should there be preferential treatment given to the industry especially when restrictions are necessary to be imposed?
Cement is put on ?D? category for wagon allotment preference by railways. Hence, cement has low priority in comparison to ?B? category food grains and fertilisers. The cement industry has to suffer heavily on account of wagon shortages, being non priority in wagon allotment. Choking of rail infrastructure at loading and unloading points with large storage areas occupied by ?B? category seasonal items, puts restrictions on cement industry. Cement should be considered in par with other commodities.

Coastal shipping can be a good option for plants located close to water bodies. However, there is an unmet need of small jetties for delivery at unloading point as well as connected road network.

Continue Reading
Click to comment

Leave a Reply

Your email address will not be published. Required fields are marked *

Concrete

Nuvoco Vistas, CleanMax Partner for Wind-Solar Hybrid Project in Rajasthan

Published

on

By

Shares

The project – comprising 20 MW of wind and 26.4 MWdc of solar capacity – will support Nuvoco’s cement operations with cleaner power while strengthening its renewable energy and decarbonisation strategy.

Mumbai, September 29, 2026

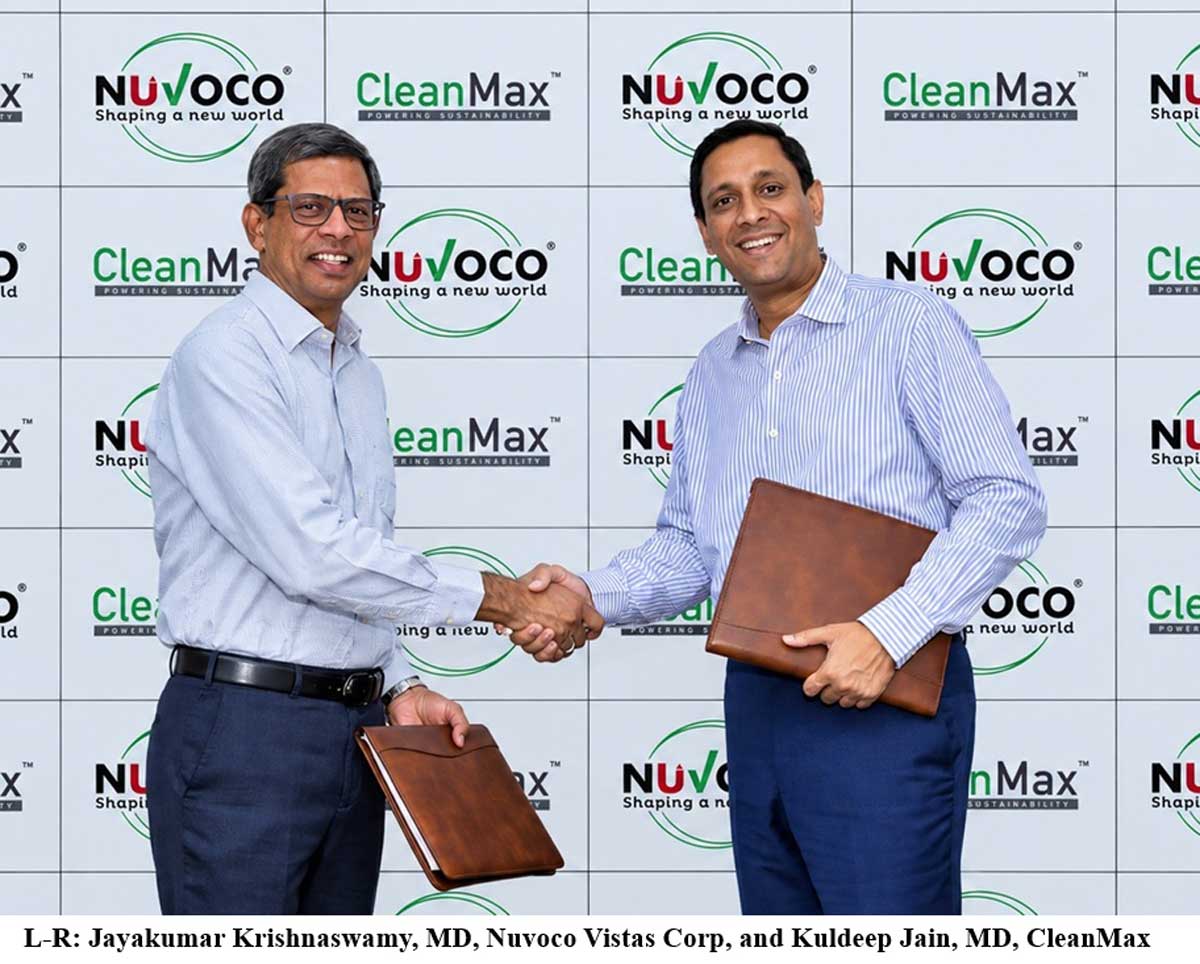
Nuvoco Vistas Corp Ltd, part of Nirma Group and one of India’s leading cement companies, has partnered with Clean Max Enviro Energy Solutions Limited (CleanMax), a renewable energy solutions provider for the commercial and industrial (C&I) sector, to develop a 46.4 MW wind-solar hybrid renewable energy project in Rajasthan.

The project will support Nuvoco’s cement operations with cleaner power while strengthening its renewable energy and decarbonisation strategy. It is expected to increase the share of renewable energy in Nuvoco’s power mix, reducing fossil fuel consumption and associated emissions.

Developed by CleanMax, an Independent Power Producer (IPP), at Bhikamkhore, Rajasthan, the project will comprise 20 MW of wind capacity and 26.4 MWdc of solar capacity, along with a 2-MWh Battery Energy Storage System (BESS). Power generated from the facility will be supplied to Nuvoco through the State Transmission Utility (STU) Open Access network.

The hybrid project is expected to generate approximately 100 million units (MU) of renewable electricity annually and help avoid around 1,25,485 tonnes of CO₂ emissions every year across Scope 1 and Scope 2 emissions.

The initiative supports Nuvoco’s ongoing efforts to reduce the carbon intensity of its manufacturing operations through renewable energy adoption, Waste Heat Recovery Systems (WHRS), energy-efficiency measures and increased use of alternative fuels. It also aligns with the company’s DIRE (Digitalisation, Innovation and Renewables) agenda, which focuses on climate action, renewable energy transition, water stewardship, circularity and biodiversity conservation across its manufacturing ecosystem.

Commenting on the initiative, Jayakumar Krishnaswamy, Managing Director, Nuvoco Vistas Corp Ltd, said, “This marks an important step in advancing Nuvoco’s journey towards more sustainable and resilient operations. Our collaboration with CleanMax will increase the share of renewable energy across our Rajasthan operations, strengthening our energy mix while improving long-term cost efficiency and reducing our dependence on conventional power sources. Initiatives such as these reinforce our commitment to operational excellence and responsible growth, while supporting our vision of Building a Safer, Smarter and Sustainable World.”

Kuldeep Jain, Founder and Managing Director, CleanMax, said, “Cement plants run continuously, so the power behind them has to be dependable for decades, not years. We’re seeing manufacturing industries view clean energy as an integral part of their core operations and long-term strategy. Our partnership with Nuvoco reflects that shift, and we’re pleased to support its decarbonisation journey. This wind-solar hybrid project is designed to deliver long-term cost certainty while supporting the Company’s transition to cleaner power.”

Nuvoco has been advancing its sustainability initiatives through renewable energy, operational efficiency and technology-driven solutions. The company operates across Cement, Ready-Mix Concrete (RMX) and Modern Building Materials (MBM) segments, with a presence across East, North and West India.

The company began operations in 2014 with a greenfield cement plant in Nimbol, Rajasthan, and later acquired Lafarge India Limited, which entered India in 1999, along with Emami Cement Ltd in 2020 and Vadraj Cement Limited in April 2025. With planned expansion initiatives, including a new grinding mill at the Arasmeta Cement Plant and multiple debottlenecking projects, Nuvoco aims to achieve a cement capacity of 35 MMTPA.

The company reported total income of Rs 113.62 billion in FY 2025-26, reflecting its continued growth trajectory. Its cement portfolio includes Concreto, Duraguard, Double Bull, PSC, Nirmax and Infracem brands, while its RMX business offers products under Concreto, Artiste, InstaMix, X-Con and Ecodure brands. Nuvoco also provides construction solutions under its Zero M range of modern building materials.

Continue Reading

Concrete

UltraTech Cement achieves 100% green energy milestone at Chhattisgarh plant

Published

on

By

Shares

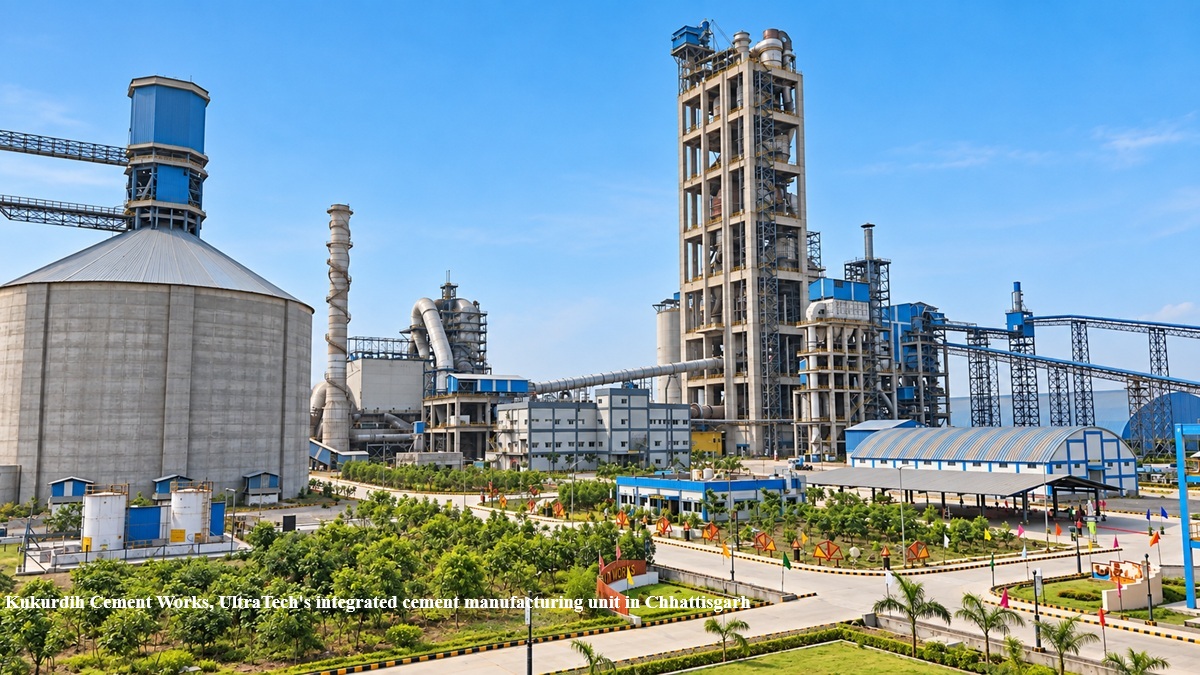
UltraTech Cement’s Kukurdih Works becomes its first integrated unit to meet 100 per cent electricity needs through green energy every month.

Raipur (Chhattisgarh)

UltraTech Cement Limited, the world’s largest cement company outside China, has achieved a significant decarbonisation milestone, with its Kukurdih Cement Works integrated unit in Chhattisgarh meeting 100 per cent of its electricity requirement through green energy every month since April 2026.

Commissioned in 2024, Kukurdih Cement Works has an installed grey cement capacity of 3.3 million tonnes per annum. The unit achieved this milestone through a combination of renewable power sourcing and Waste Heat Recovery Systems (WHRS), which now collectively meet its entire electricity demand while ensuring operational reliability.

Since April 2026, nearly one-third of UltraTech’s 76 manufacturing units in India have maintained green energy utilisation above 50 per cent of their electricity requirements. Five units, including Kukurdih, have exceeded 95 per cent green energy utilisation. The company is also progressively deploying Battery Energy Storage Systems (BESS) across its network to enable deeper renewable energy integration.

As part of its decarbonisation strategy, UltraTech has not invested in additional captive thermal power capacity for greenfield projects or brownfield expansions at its integrated units for over a decade.

As of Q1FY27, the company’s captive green energy capacity stood at 1,897 MW, comprising 1,463 MW of renewable energy capacity from solar, wind and hybrid sources, along with 434 MW of WHRS capacity. Under its RE100 commitment, UltraTech aims to increase the share of green power in its total energy mix to 85 per cent by 2030 and achieve 100 per cent by 2050.

UltraTech Cement Ltd, the cement flagship company of the Aditya Birla Group, is a $10-billion building solutions company and the largest cement producer globally by sales volume outside China. The company has a total grey cement capacity of 210.1 MTPA and white cement/putty capacity of 3.5 MTPA. It is a signatory to the GCCA Climate Ambition 2050 and has committed to the Net Zero Concrete roadmap announced by GCCA.

Continue Reading

Economy & Market

From First Mile to Last Mile

Published

on

By

Shares

Praveen Vashistha, Founder, Gxpress Solutions, speaks about building a holistic logistics network that encompasses latest technology and current challenges faced by logistics service providers.

Logistics may seem to only entail transporting a package from one location to another. However, there is more to this term than just that. Logistics refers to the entire process of controlling all movement, transfers and decisions in the correct way at the right time and cost and with the desired level of visibility.

People nowadays want to receive more than just the delivery. They want quick, efficient, reliable and transparent logistics service. On the other hand, companies are facing higher operating costs, broken supply chains, congested cities, changing habits of consumers and growing complexity of logistics services. In this situation, a full logistics package is gaining importance not only as a competitive advantage but also as a necessity for a successful business.

The main challenge lies in uniting the first mile, the middle mile and the last mile into one seamless process.

The journey begins before the package moves

First-mile logistics may be the least recognised part of the logistics chain, but they have a crucial influence on all that follows.

This stage starts from the moment the shipment leaves the manufacturer, supplier, farm, warehouse or distribution centre. Depending on the industry, first-mile logistics may involve grouping shipments from multiple suppliers, compiling paperwork and checking the inventory before sending the shipments to a central hub.

Flaws in first-mile logistics produce effects later down the supply chain. Delays in cargo pickup can affect warehouse operations; improper packaging can damage goods in transit; and incorrect inventory information may cause stockholding or unnecessary replenishments.

This is why building a reliable network involves simplifying the operations done at the beginning of the supply chain.
Companies require accurate demand forecasts, supplier visibility, standard procedures, and software to capture information from the moment a shipment enters the supply chain. Route planning and fleet management are also important at this stage, especially as it may involve contacting multiple suppliers.

The main goal is simply to make the first mile predictable.

The middle mile: Where scale meets complexity

When products leave the original site, they travel through the ‘middle mile,’ which connects fulfilment centres, warehouses, sorting centres, and regional distribution points. In this phase, logistics networks begin operating on a large scale. A shipment can pass through several facilities before reaching the final destination. Each additional transfer entails the risk of delay or damage and information losses. Accordingly, the ideal solution is not to minimise the number of transfers but rather to optimise them. The use of hub-and-spoke networks, regional distribution centres, and strategically placed distribution centres can help companies shorten transportation routes and optimise distribution costs. Besides, data can be used to determine the optimal placement of inventories.

For instance, a retailer may find that it takes more time and is more expensive to deliver goods to customers if everything is stored in a central warehouse. Meanwhile, regional distribution helps meet the customer’s needs quicker and more efficiently.

The last mile is where the customer judges you

When it comes to the logistics experience, the customer experience comes down to the delivery. While the last mile might comprise a small part of the entire journey in actual distance, it could also entail expensive and difficult processes. Delivery runs through densely populated cities, through traffic jams, through unsuccessful delivery attempts, and through changing consumer preferences and narrowed time frames.

Customers want to have control over their delivery. Delivery means that customers expect to know the exact moment when their order is delivered. They need to receive current updates about their orders and the ability to decide whether they want scheduled deliveries, or whether they want their order to be dropped off at a designated location far from their house.

As a result, last-mile logistics must incorporate both efficiency and experience. The technology may be used to ensure timely and accurate delivery, through such products as route optimisation and real-time delivery tracking.

However, technology is not enough to guarantee success in terms of last-mile delivery. Knowledge of the local area is still an important aspect that contributes to successful delivery.

One network, not three separate operations

First, the common mistake that organisations can make is treating the first mile, the middle, and the last mile separately.

An effective first mile of logistics does not matter much if the shipment waits in a hub for many hours. A perfectly working warehouse does not make a happy customer if the last-mile delivery fails. Therefore, even the fastest last-mile delivery can become an expensive operation if the supply is not well geographically positioned.

The three moments should work together as one whole system.

This implies having a common view on inventory, transport capacities, shipment statuses and demand. The Transportation Management System, Warehouse Management System and order management system should give information to each other instead of acting like separate islands.

That is where real-time information comes into play!

If something happens, such as a vehicle gets delayed, the company has to know that from the start. If not, someone from Customer Service should be informed about the situation.

Visibility is the new infrastructure

Previously, companies had to rely on physical assets, such as warehouses, trucks, and sorting facilities, to create their logistics networks. Today, they have an additional layer of technology providing visibility.

Command-and-control systems now include GPS tracking, Internet of Things devices, bar-coding, RFID, cloud computing, artificial intelligence, and analytics, which allow companies to know what the goods are doing, how well they are doing, and what is going to happen next.

Predictive analytics reveal possible delays. AI-powered forecasting increases availability. Digital dashboards enable the manager to monitor all operations in one place. The efficiency of such technologies is not measured in the amount of information they gather, but rather in their capability of converting data into knowledge.

Logistics managers should be able to answer the following questions: Where is it? When is it supposed to arrive? What causes the delay? What impact does it have? Can it be delivered some other way? How much will it cost?

The sooner the answers are given, the more resilient the logistics system is.

Resilience must be designed into the network

The events of recent years have highlighted the vulnerability of interconnected supply chains. Geopolitical tensions, bad weather, a lack of labour, poorly developed infrastructure and an unexpected spike in demand are some events that can cause problems for logistics systems without prior notice. Thus, companies should create an end-to-end network not just for normal times but also capable of functioning quickly in problematic situations. In order to create such a network, it is necessary to find alternative suppliers, use several means of transportation, create several routes of delivery, and establish inventory. It is also important to use scenario planning to define what to do if the main hub becomes unavailable or any means of transportation is blocked.

Sustainability: Part of the delivery equation

The future of logistics will also be shaped by environmental considerations.

As delivery volumes rise, businesses are under increasing pressure to reduce emissions without compromising service. Better route planning, load optimisation, electric vehicles, alternative fuels, renewable-energy-powered warehouses and consolidated deliveries can all contribute. The most sustainable shipment is often the one that does not require unnecessary movement in the first place.

Better demand forecasting and inventory placement can reduce empty miles and avoid repeated transportation. Consolidating deliveries can improve vehicle utilisation. Reverse logistics can ensure that products, packaging and materials return efficiently instead of becoming waste.

Sustainability, therefore, should not be treated as a separate initiative. It should be incorporated into network design itself.

The future belongs to connected logistics

An end-to-end logistics network ultimately seeks to close existing gaps between various processes.

Every mile of the process should be interconnected with the other miles. Warehouses should be aware of the restraints imposed by transportation. Delivery crews should be able to know at every moment the inventory at their disposal. Clients must have access to this useful information.

Companies that will be successful in this area will not necessarily be the ones with the biggest fleets or the most warehouses. They will simply be the ones that can employ their resources in the most effective manner.

The future of logistics will be represented by an ecosystem consisting of the combination of the physical aspect, digital intelligence, and personnel decisions. Every mile in the process of delivery is important. However, the key advantage here is getting those miles to work together.

For companies, it means having minimal resistance, enhancing their efficiency and improving customer care. For clients, it means simply having the right product delivered at the right time.

About the author: Praveen Vashistha, Founder, Gxpress Solutions,

Continue Reading

Video Thumbnail
▶

    SIGN-UP FOR OUR GENERAL NEWSLETTER

    Trending News

    SUBSCRIBE TO THE NEWSLETTER


    Don't miss out on valuable insights and opportunities to connect with like minded professionals.


      This will close in 0 seconds