Connect with us

Economy & Market

A perfect distribution?

Published

on

Shares

The distribution of cement to the end user from the manufacturer is a major cost factor in the landed cost of cement at the user end. ICR takes a look at the major obstacles in cement distribution.

Till 80s cement was available only as a commodity, and the production and distribution of cement was controlled by the Government. One had to apply to a district collector to get cement allotted for a job. It is only during the late 80s that cement was decontrolled and as a result many players entered into cement production, triggering competition into the cement industry.

It has been almost 28 years since cement has been decontrolled. Since then industry has witnessed high level of competition which has forced all the players to create their brand image in the minds of the customer so they can fetch premium price over competitors. But slowly all the companies have started replicating the activities undertaken by any pioneer company and so the companies were forced to control their cost in order to ensure reasonable profits during the lean period, i.e., when the demand is low and prices are under pressure. It is important to note the recent development of selling cement through online shops like Snapdeal, etc.

Mechanics of distribution channels
Companies invariably hire carry and forwarding agents (CFAs) to transport cement to their own or dealers? warehouses, which is either done via road or railways. From CFAs or warehouses, the cement is then transported to dealers/distributors and further to sub dealers who finally sell it to the end user. The physical ownership of goods every time does not get transferred. In the other case, dealers and sub dealers take order from buyers and place it to the companies, distributors coordinate and monitor for the timely dispatch of said orders, transportation of goods and final delivery and in return get their commission. It must be borne in mind that it is high volume and low margin business as stated by both – Nikhil Phadke, Partner, Vaidya & Co, and Senan Shah, Om Swastik Trading.

Distributor network in cement industry is highly dominating, and companies are compelled to hire the services as they rarely have any rapport or contact with the end consumer of their product. Apart from this, distributors have storage facilities, which enable them to control the supply chain. Therefore it becomes an important link in the business chain.

Three major factors affect the cost of cement. These include: logistic (20 to 22 per cent), excise and VAT of which excise and VAT are Government duties and thus cannot be controlled by the manufacturer. So only cost that is in the hands of manufacturer is the logistic cost, and in order to reduce the logistic cost, the companies try to sell their production in the nearby areas.

Moreover as the cement plant has to be installed nearby limestone deposits, plants of various companies are located very near to each other. This creates an intense competition in the nearby areas as all the companies try to sell their product with minimal logistic cost. Largely this is applicable to all the cement plants but as the big companies have huge production capacity at the single plant they have low cost of production and so they can afford to distribute their product at far off places at a slightly higher price. But the small players have limited production capacity so they try to increase their profits by saving on the logistic cost by selling in a limited area, and this technique of saving on logistic cost is shrinking their area of operation. This can be experienced in the states of Telangana and Andhra Pradesh. Thus intense competition is experienced in local areas as big players have to sell some part of their production in local area to get higher realisation and the local companies have to sell in local areas as they cannot afford to sell in far-off places due to increasing logistic cost. Moreover the transportation cost always has an increasing trend, so every company prefers to sell their maximum possible production in the nearby area which increases competition to a great extent.

Today we can say, in all the developed countries, cement is still treated as a commodity whereas in India it is somewhere between commodity and brand. In short, for a retail buyer, companies sell it as a brand whereas for institutional buyers it is sold as a commodity. The dealer is extremely important for both buyer and manufacturer.

Distribution Channel: Cement v/s FMCG
The business is driven on relationship more than that of a brand. The market is extremely price-sensitive and therefore the brand cannot fetch a value beyond a certain level. Typically the institutional buyers squeeze the manufacturers and dealers to a maximum. The systems of payment and collection are better in FMCG sector than that of cement. The channel has to improve on that. Many a times as referred by Phadke, deliveries are effected just on telephone calls without any documentation and dealers have been exposed to a great risk. Probably the younger generation has to learn from it and correct their actions.

According to Rahul Akkara, Associate Vice President – Brand, JSW Cement, "In the cement business, the dealer is accountable for expanding the base across his/her territory and for doing this, he/she needs to have a good sub dealer base, which would help him achieve this. Also the dealer should also have good networking with influencers such as contractors, engineers, masons and builders, who are also equally responsible to increase business for a cement brand in his territory."

Exclusivity so called is meaningless and forced only by the companies even though they understand that exclusive dealers are doing business with other brands, may be in equal volumes only under different names. Secondly as expressed by Phadke, it is not legally enforceable but still cement companies are going on creating exclusive dealers. It needs second thinking.

Cement bags does not carry an expiry date but it does not mean that the old stock can be put to use for any job like casting a slab or column. Here it differs far from that of FMCG products and procedures. Leftover or damaged products are returned to the manufacturers, however it does not apply to cement. Another major difference with that of FMCG products is that the manufacturer scores over that of the distributor and he is dominant where as in cement business chain the dealer is more valued than the manufacturer.

The other issue raised by Phadke is very valid but has no immediate answer. CFAs are becoming cement dealers and competing with traditional channel members. It is important to remember that as CFAs have access to very vital information about the dealers customers and that can be used to compete with them. Even legally it will not be possible for any one to stop such entry but what can be done is they can be allotted different territory for doing business so as to protect the interest of the existing dealers. On the other hand some of the existing dealers have been investing money to have their own transport but it has not been very common.

Surprisingly no one has talked about the loss of cement either by the way of using hooks or because of transloading of shipment. The quantum of loss is significant but since it is a high volume business no one seems to be worried.


Concrete

Wonder Cement appoints Mahesh Singh as VP Corporate Brand Communication 

Published

on

By

Shares

Singh brings 20+ years of brand and marketing experience, and will lead integrated corporate brand communication initiatives at Wonder Cement 

New Delhi

Wonder Cement, a leading cement manufacturer, has appointed Mahesh Singh as Vice President – Corporate Brand Communication. In his new role, he will oversee corporate brand strategy and communication, including digital and performance marketing, public relations, trade, events, exhibitions, sports and experiential marketing. 

Singh brings over two decades of experience across marketing and communications, with roles spanning the automotive industry, agencies and entrepreneurship. He spent more than a decade with Honda Motorcycle & Scooter India, working across integrated communication, media, digital, retail and consumer engagement. His stint also included helping build the company’s digital marketing capabilities. 

He moved to dentsu X India as Vice President – Strategy & Planning, working across categories such as automotive, auto components, electric vehicles, FMCG, consumer electronics, BFSI, apparel and brand consulting. His responsibilities included media and marketing strategy, product launches, content, performance marketing and consumer activations. 

Singh subsequently took an entrepreneurial route with Radiant Brands before joining Shriram Ltd (SPR Autotech) as Head – Marketing & Communications. There, his remit included brand and corporate strategy, communications, PR and ORM, retail identity, loyalty programmes and events. 

At Wonder Cement, Singh will be responsible for bringing together the company’s corporate brand communication initiatives across digital, performance marketing, PR, trade, sports and experiential platforms. The role will focus on creating an integrated approach to communication across consumers, trade partners and other key stakeholders. 

The appointment brings to Wonder Cement a marketer whose career has spanned the brand, agency and entrepreneurial sides of the communications ecosystem. 

Wonder Cement, part of the RK Group, is a cement manufacturer with roots in Rajasthan and a focus on quality, trust and transparency. The company has grown to six manufacturing plants, and a cement capacity of 21.5 MTPA. With more than 2,000 employees and a network of over 5,000 dealers, its operations span manufacturing, distribution and customer engagement, with a focus on consistent product quality and efficient execution. 

Continue Reading

Concrete

JSW Cement commissions additional 1 MTPA grinding unit at Nagaur

Published

on

By

Shares

With this commissioning, JSW Cement’s total cement grinding capacity has increased to 25.10 MTPA, 
Mumbai

JSW Cement, one of India’s leading green cement producers and part of the diversified JSW Group, today announced the successful commissioning of an additional 1.00 MTPA cement grinding unit at Nagaur, Rajasthan. The commissioning marks another significant milestone in the Company’s growth strategy.

With this commissioning, JSW Cement’s total cement grinding capacity has increased to 25.10 MTPA, while its total clinker manufacturing capacity, including clinker capacity at its joint venture, JSW Cement FZC, stands at 9.74 MTPA.

JSW Cement had commenced operations in North India in March 2026 with the Nagaur Integrated Plant, comprising a 3.30 MTPA clinkerisation unit and 2.50 MTPA cement grinding unit. With the commissioning of the additional 1.00 MTPA cement grinding unit, the plant’s total cement grinding capacity has increased to 3.50 MTPA, enhancing the company’s ability to cater to the growing cement demand across Rajasthan, Haryana, Punjab and the National Capital Region (NCR). The expansion has been funded through a strategic mix of equity and long-term debt.

During the quarter ended 30th September 2026, JSW Cement has also commissioned the Alternate Fuel Handling System and the Waste Heat Recovery system (WHRS) at the Nagaur Integrated Plant.

Nilesh Narwekar, CEO, JSW Cement, said: “The commissioning of additional 1.00 MTPA grinding capacity at Nagaur is a key strategic priority for us and will accelerate JSW Cement’s expansion into North India. We look forward to servicing the growing needs of the region and contributing to the economic growth of Rajasthan, Haryana, Punjab and the NCR area. I am delighted to share that the company has commissioned this grinding unit within the expected timeline, showcasing our project execution capabilities. Further, the Alternate Fuel Handling System and the Waste Heat Recovery system (WHRS) are expected to substantially reduce our production costs going forward.”

Continue Reading

Concrete

UltraTech becomes first Indian cement firm to cross 2 GW green energy

Published

on

By

Shares

UltraTech Cement has crossed 2 GW of captive green energy capacity, with renewables and waste heat recovery meeting 48 per cent of its power needs.

Mumbai

UltraTech Cement Limited has surpassed 2 GW of installed green energy capacity for captive use, becoming the first cement company in India to achieve the milestone. The Aditya Birla Group company commissioned 116.55 MW of wind capacity at its Inter-State Transmission System-connected wind-solar hybrid project in Barmer, Rajasthan, along with 10 MW of Waste Heat Recovery System capacity at Sarlanagar Cement Works in Karnataka.

With these additions, UltraTech’s cumulative installed green energy capacity has reached 2,024 MW. This includes 1,580 MW of renewable energy capacity and 444 MW of waste heat recovery capacity, together meeting around 48 per cent of the company’s current power requirements.

The company said the milestone reflects the progress of its long-term energy transition strategy. In FY27 so far, nearly one-third of UltraTech’s 76 manufacturing units in India have maintained green energy utilisation above 50 per cent of their electricity requirements, while five units have crossed 95 per cent.

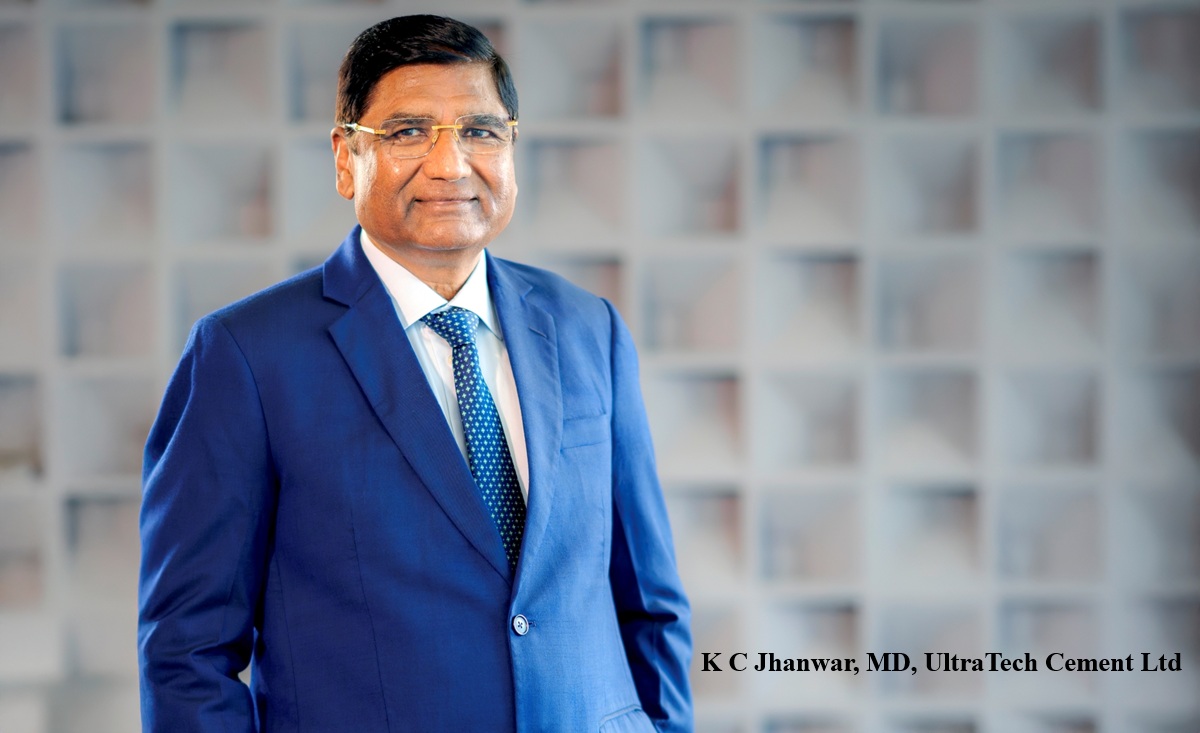
K C Jhanwar, Managing Director, UltraTech Cement Limited, said, “Crossing the 2 GW green energy milestone is the result of a strategy we have pursued consistently over the past decade. Cement is an energy-intensive, hard-to-abate sector, and showing that reliability and growth can go hand in hand with a rapid shift to green energy sets a benchmark for the industry. With nearly half of our power needs now met through green energy, we are significantly less exposed to fossil fuel supply constraints and power price volatility. As we scale up renewables, waste heat recovery and battery storage across our operations, we are building an energy foundation for stable, long-term growth.”

UltraTech commissioned 430 MW of green energy capacity in FY26 and continues to expand its renewable energy and waste heat recovery portfolio.

The company is also progressively integrating Battery Energy Storage Systems across its operations to improve renewable energy utilisation and supply reliability.

In 2025, UltraTech operationalised what it described as India’s first on-site hybrid round-the-clock renewable energy project at Sewagram Cement Works in Gujarat. The project combines solar, wind and battery storage.

As part of its decarbonisation strategy, UltraTech said it has not invested in new captive thermal power capacity for either greenfield projects or brownfield expansions at its integrated units for more than a decade.

The company said its expanding green energy portfolio is helping reduce dependence on conventional grid electricity and fossil fuel-based power, while lowering exposure to fluctuations in coal and electricity prices.

UltraTech aims to increase green energy’s share in its total power mix to 85 per cent by 2030. As a member of RE100, it has also committed to meeting 100 per cent of its electricity requirement through renewable sources by 2050.

UltraTech Cement, the cement flagship of the Aditya Birla Group, has a total grey cement capacity of 210.1 MTPA and white cement and putty capacity of 3.5 MTPA. The company is also a signatory to the GCCA Climate Ambition 2050 and has committed to the GCCA Net Zero Concrete roadmap.

Continue Reading

Video Thumbnail
▶

    SIGN-UP FOR OUR GENERAL NEWSLETTER

    Trending News

    SUBSCRIBE TO THE NEWSLETTER


    Don't miss out on valuable insights and opportunities to connect with like minded professionals.


      This will close in 0 seconds