As decarbonisation reshapes cement manufacturing, refractory systems have become pivotal to both operational resilience and future-ready kiln design. Professor Procyon Mukherjee explains how their evolution now defines the limits and possibilities of the industry’s transformation.
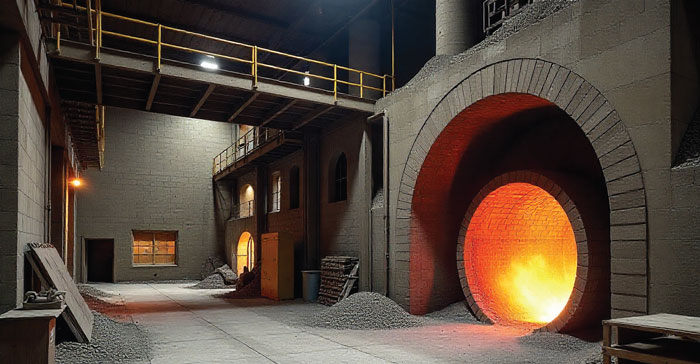
Refractory materials and pyro-processing remain the beating heart of cement manufacture. As attention shifts from incremental efficiency gains to decarbonisation and resilience, refractories and kiln-system technologies are both constraint and opportunity: they determine how fast plants can adopt alternative fuels, electrified heat, oxy-fuel systems or CCS, and they often account for a material portion of operating cost, downtime risk and capital renewal. In this article, I have tried to synthesise market signals, emerging technologies, green pathways, supplier developments and the cost outlook you need to brief for designing strategic investments for the cement industry in particular.
Demand drivers and industry structure
The global refractories market — of which cement is a major end-use alongside steel and glass — is large and growing, driven by construction activity in APAC, replacement demand (wear and corrosion), and investments related to kiln retrofits and decarbonisation projects. Recent market analyses place the refractories industry value in the multiple tens of billions of dollars and forecast steady mid-single-digit growth over the coming decade, with Asia (especially China and India) accounting for the largest regional share.
Market structure is oligopolistic at the high end. A handful of global players (RHI Magnesita, Vesuvius, Calderys/Imerys, Saint-Gobain, Krosaki Harima, Morgan Advanced Materials, etc.) supply engineered refractories, backed by regional and specialist vendors that dominate lower-cost or commodity segments. Mergers and vertical integration around alumina/magnesia feedstocks are active themes as refractory firms seek to secure raw-material supply and control quality and costs. A recent example is RHI Magnesita’s strategic acquisition of the U.S. alumina producer Resco, aimed at supply-chain security for alumina-based refractories. Most strategic sourcing models are moving to long term partnerships, which could extend to service models as well.
From the purchaser’s side, refractory selection is now evaluated not only against thermal and chemical resilience but on a broader life-cycle basis: uptime impact, ability to tolerate alternative fuels (biomass, waste-derived fuels, SRF/plastics), compatibility with oxy-fuel or electrified heat, and the ease of condition monitoring and targeted repairs. Key technical drivers include:
- Resistance to alkali attack and melt penetration under high-chloride / high-alkali fuels.
- Thermal shock tolerance as preheater/cooler cycling increases with flexible operation.
- Low thermal conductivity with structural strength to reduce heat losses.
- Compatibility with sensor embedding and digital monitoring to enable predictive maintenance.
These needs are changing refractory specifications — and therefore supplier offerings — quickly.
Emerging technologies
Several material and process innovations are maturing that directly affect kiln reliability and total cost of ownership:
1. Advanced engineered monolithics and castables: Improved bonding chemistries, nano-modifiers, and lower alkali reactivity variants lengthen campaign life and reduce patch repairs. These allow quicker repairs and less kiln downtime.
2. 3D printing and prefabricated brick assemblies: Additive manufacturing of complex refractory shapes (for riser ducts, burner blocks, throat areas) enables bespoke geometries and faster onsite installation with better dimensional control where space/access is constrained.
3. Sensorised refractories and embedded monitoring: Thermocouples, acoustic emission sensors
and distributed fibre-optic temperature measurement are being embedded to give real-time maps of lining health. These digital twins enable condition-based maintenance rather than calendar-based shutdowns.
4. Hybrid lining systems: Combining high-performance bricks in the hot face with insulating monolithics behind them to optimise performance vs cost.
Publications and industry trials in 2023–25 show pilot uptake of these technologies; embedding sensors and using predictive analytics is particularly impactful for reducing unplanned outages.
Pyro-processing trends
Decarbonisation is reshaping kiln-system choices more than any other factor this decade:
- Fuel flexibility and waste fuels: Plants are accepting higher shares of SRF, biomass and RDF. These fuels introduce chemical aggressors (chlorides, alkalis) that stress refractories and increase corrosion; refractory chemistry and cooling strategies must adapt.
- Electrification and high-temperature electricity: Technologies ranging from electrified calciners to resistive or induction heating for preheaters are under review. Recent reviews highlight electrified process heat and electrochemical routes as credible pathways, especially where grid decarbonisation is advanced.
- Oxy-fuel combustion and CCS readiness: Oxy-fuel retrofits enable easier CO2 capture but change the thermal and chemical environment in the preheater and kiln. Some pilot CCS projects in Europe, linked to cement plants and clustered transport/storage (e.g., projects coordinated out of Norway), are already operational or scaling. Cement companies with aggressive Net Zero targets are factoring refractory compatibility into their CCS roadmaps.
- Hydrogen and power-to-X: Hydrogen co-firing trials have started at modest scales; hydrogen changes flame temperature profiles and may accelerate certain refractory degradation modes if not managed.
From an engineering standpoint, conversion choices are constrained by refractory life: a kiln that can’t tolerate the chemical profile from high biomass firing, or the different flue-gas composition from oxy-fuel, will force expensive lining redesigns.
Green initiatives
Sustainability actions in cement are not solely about CO2 numbers; they alter operating envelopes:
- Clinker substitution: LC3 and blended cements reduce kiln duty and thermal load per tonne of cement, indirectly lowering refractory wear rates per unit of cement produced. LC3 deployment at scale (notably in India and other markets) is beginning to change clinker demand profiles and feedstock strategies.
- Energy efficiency upgrades: Improved preheaters/coolers and waste heat recovery change temperature gradients and gas flows; refractories must be specified for the new steady-state and transient regimes.
- Circularity in refractory materials: Recycling of spent refractories (where feasible) and substitution with lower embodied carbon raw materials (e.g., using locally sourced calcined clays or tailored industrial by-products) are receiving attention in R&D and supplier pilot programs.
- Carbon capture deployment: As CCS is pilot-scaled, refractory selection increasingly considers compatibility with capture solvents and altered flue-gas chemistries.
New suppliers and supply-chain resilience
While the well-known global refractory houses dominate engineered solutions, the landscape sees three simultaneous moves:
1. Vertical integration by majors: Acquisitions of alumina producers and feedstock businesses (e.g., RHI Magnesita’s purchase moves) to secure quality and reduce volatility.
2. Regional challengers and Chinese manufacturers: Lower-cost suppliers are increasing capacity and technical capability; large cement groups in Asia often source locally, pressuring pricing and forcing global suppliers to differentiate on performance, warranties and service.
3. Specialist technology start-ups: Firms focusing on 3D-printing of refractory shapes, sensor embedding or novel binder chemistries are becoming acquisition targets for established players.
For procurement teams, this means re-assessing TCO: supplier choice is now as much about data services, installation competence, and lifecycle guarantees as it is about price per ton of bricks.
Where are costs headed?
Costs for refractory systems will be driven by four linked forces:
1. Raw-material price pressure: Prices of magnesia, bauxite/alumina and specialty clays move with energy, mining constraints and geopolitical supply; vertical integrations indicate producers expect sustained volatility.
2. Capex for decarbonisation: Retrofits for oxy-fuel, electrification, CCS readiness, and hydrogen blending often require modified kiln internals and more frequent, higher-quality linings; these add upfront cost but can lower total emissions and long-term operating risk.
3. Service and digital premiums: Sensorised systems, data analytics and condition-based maintenance contracts add cost but lower unplanned downtime and extend campaign life — often commercially attractive for large plants.
4. Regional divergence: Costs will diverge geographically. Plants in jurisdictions with strong carbon pricing, subsidies for CCS, or higher electricity costs will see different economics than plants in low-cost coal regions. Market reports forecast moderate refractory price inflation overall, but with pockets of higher increase tied to feedstock bottlenecks and decarbonisation capex.
Practical recommendations for senior engineers and CMOs and CPOs:
1. Embed refractory strategy in decarbonisation planning: Any decision to scale biomass, oxy-fuel, hydrogen or CCS must have a refractory impact assessment and budget for both material and installation adaptations.
2. Specify for monitorability: Require suppliers to support embedded sensors and data interfaces; insist on warranties that link lining life to clearly defined operating envelopes.
3. Partner on trials: Work with one global and one regional supplier on co-funded trials for 3D-printed shapes, new monolithic mixes, or sensorised linings — accelerate learning before full retrofit.
4. Stress test supply chains: Given recent upstream consolidation, model raw-material failure modes and engage in off-take agreements or joint-stock buffering where alumina or magnesia supplies are strategic.
5. Financially model TCO, not unit price: Factor in longer campaign life, reduced outage probability, and digital services when comparing quotes.
Conclusion
Refractories and pyro-processing are no longer ‘just materials.’ They are strategic assets that determine whether a cement plant can safely and economically transition to lower-carbon fuels and new heat sources. The coming decade will be shaped by a mixture of material science advances (3D printing, sensorised linings, hybrid systems), operational technologies (electrified heat, oxy-fuel, CCS), and shifting supplier dynamics (vertical integration and new entrants). Senior engineers must therefore treat refractory strategy as a cross-functional lever — part of the decarbonisation, reliability and procurement playbook — and design decisions with total cost, not short-term price, at the fore.
About the author:
Professor Procyon Mukherjee, ex-CPO Lafarge-Holcim India, ex-President Hindalco, ex-VP Supply Chain Novelis Europe, holds deep expertise in logistics, procurement, operations and supply chain management. An author and academic, he now teaches at leading institutions and advises global firms on SCM, industrial leadership, and the aluminum and cement sectors.