

Concrete
(Re)discovering Alternative Raw Materials are Essential to the Green Cement Plant

As the realities of climate change continue to hit home, social pressure on heavy emitters is increasing and financial pressure will follow, forcing cement producers to act. The cement industry has a responsibility to follow through on its promises to decarbonise.
As a leading supplier to the industry, FLSmidth feels this responsibility keenly. This article is an overview of the options to decarbonise – reducing the clinker factor. As we will learn, the green cement plant of the future may not look so different from a plant you would see today, but it is. The difference is in the way it is operated, what is being put into it, and some of the supporting technology.
Fly ash – set to get a second wind
As the cement industry faces increasing scrutiny over its environmental footprint – no stone is left unturned in attempts to reduce CO2 emissions. Fly ash has been used for decades to avoid the resource intensive limestone clinker, but shortages have led experts to debate; have we reached the full potential for fly ash in cement or could harvesting landfills give fly ash a second wind?
Fly ash is a great supplementary cementitious material – it has the right properties, meaning that it reacts with lime to form cementitious compounds. It is a by-product from coal-firing industries, but in some cases has ended up in landfills – especially up until 1929, when it was first used in concrete to minimise the use of cement when building the massive Hoover Dam on the Colorado River in the USA.
With the potential to replace up to 30 per cent of traditional clinker, fly ash quickly became very attractive to the cement industry and a sought-after commodity. Today, as the green transition of power plants and other heavy industry is accelerating – some countries are phasing out coal and turning towards green energy, natural gas, and/or biofuels, with the result being that fly ash is now in short supply.But just as steel, paper and sugar industries are eager to minimise their environmental footprint, so is cement. And the use of fly ash is both a proven and effective ingredient. The shortage of fresh fly ash has led more and more industry stakeholders to turn their attention towards the centuries of landfilled fly ash.
To date, billions of tonnes of fly ash have been landfilled. ‘Harvesting’ fly ash from these landfills makes some industry experts confident that this waste-product could have a second wind in cement.
“As we strive towards fulfilling our MissionZero promise of enabling net zero cement production by 2030, we need every tool in the toolbox. Reducing the clinker factor is a key element to that. Fly ash is a proven and well-integrated SCM – to pursue the exploitation of landfilled fly ash would obviously boost our efforts.”
To Thomas Petithuguenin, Head of Research and Partnerships for Cement, FLSmidth, every possible path to MissionZero needs to be explored.
“I am not saying that fly ash harvesting is a quick-win, but from a product point of view, it is a known ingredient and gives confidence in terms of quality and performance. The challenge is the logistics and infrastructure, which we need to investigate with stakeholders across the value chain.”
Upcycled concrete – a massive business opportunity
Repurposing of construction waste is a global, multi-billion-dollar business – to the cement industry it looks to be a win-win situation. As the world’s leading equipment supplier to both the Cement- and Mining industries, FLSmidth is well-positioned to support its customers in capturing a piece of the pie, says Petithuguenin.
At an annual growth rate of 4 per cent, the global construction and demolition waste management market is projected to be worth $142.92 billion in 2028. Combined with the cement industry’s acute need to reduce its environmental footprint, we see an increasing interest from customers exploring how to enter the market.
The recycling of concrete is not a new business case – different technologies and applications have been deployed for decades, but most often in terms of ‘downcycling’ where material will end up as road fill. Today, the average Construction and Demolition Waste (CDW) recycling rate in Europe is around 70 per cent and even though it still substitutes the use of virgin material, actual ‘upcycling’ has a massive potential of producing high-value materials out of tonnes of construction waste every year.
By upcycling concrete, we are not only able to leave virgin, raw materials in the ground, we are also able to reduce the need for traditional, resource-intensive clinker. At a time when no stone is left unturned in the quest for CO2 savings from cement production, reusing recycled cement fines as a filler, supplementary cementitious material (SCM) or by converting them into belite clinker is an attractive business-case.
The sustainability aspects of upcycling go hand-in-hand with cost-savings from eliminating the excavation of new raw-materials and a majority of the fuel and energy required for the calcination process of limestone.
According to the International Energy Association, the integration of emerging technologies like lowering the clinker-factor in cement and carbon capture is identified to provide some of the largest cumulative CO2 reductions in the 2-degree Celsius Scenario (2DS) compared to the Reference Technology Scenario (RTS) by 2050.
As we move into an industrial scale process of turning old concrete to a new cementitious material, we would need to do a few extra steps to get as pure aggregates, sand and cement fines as possible. A procedure that involves process knowledge within crushing and screening and just as important, some heavy-duty equipment such as a jaw crusher, impact crusher, cone crusher, elliptical screens, classifiers, and bag filters.
After crushing, the aggregates and sand are used in new concrete, with the potential to substitute 100% of the natural aggregates and sand needed. The cement fines, left from the crushing and grinding are ready to be converted into a belite clinker, most likely at an urban processing plant, whereafter it is mixed with OPC clinker at a 30-70 per cent ratio and reused on site – reducing the climate footprint of both the old and new building, bridge or road project. Another option is to take the cement fines back into the cement industry and carbonate them, which will activate them to SCMs – allowing their mixing with clinker (and reducing the clicker proportion, therefore, the CO2 emissions).
Today, an office building has an expected lifespan of 20 years, and a residential building a lifespan of 30-50 years. That’s extremely short and underlines the need for upcycling. If the industry is to support an accelerating urbanisation, the winners of the construction industry will be the ones who see opportunities in waste, which can be used again and again. And they will be the ones getting the building-licences from government authorities.
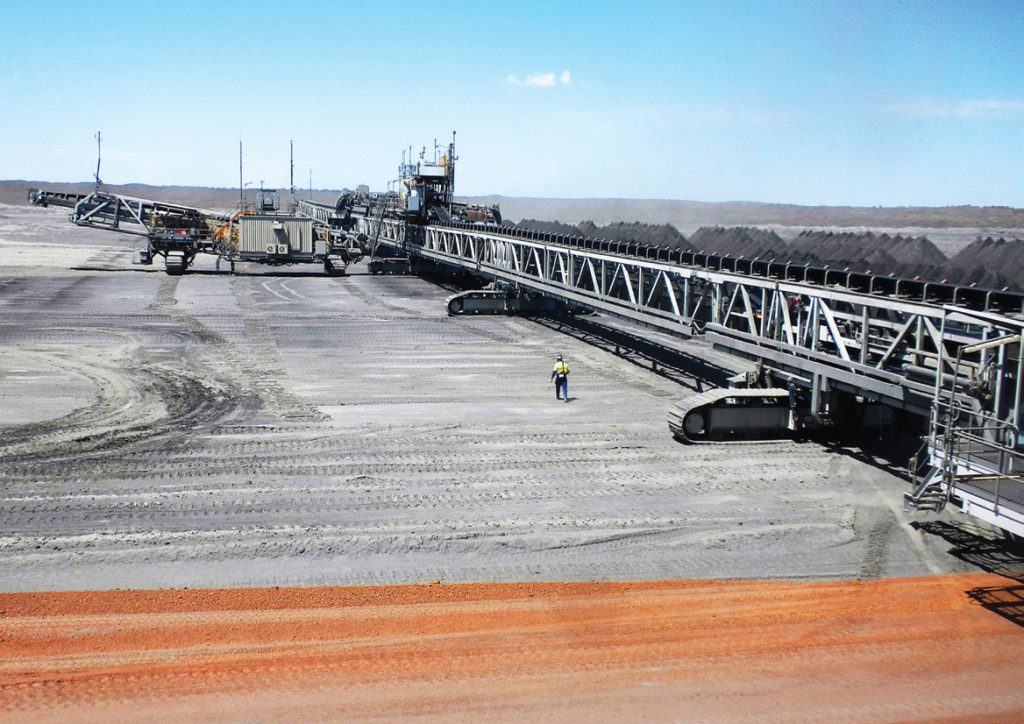
Mine tailings – a potential goldmine for cement
Tailings are both a safety issue and a huge financial burden to miners. But to cement and concrete producers they might hold a massive reservoir of untapped potential. With a shared ambition to reduce the environmental footprint of both cement and mining operations, FLSmidth is well-positioned to support its customers inturning mine tailings into value-added products, says Petithuguenin.
Mine tailings are the leftovers after the processing and extraction of metals and minerals from the basic ores. The total amount of mine tailings in active and inactive, closed storages around the world is estimated at more than 200 km3. Any attempt to describe the volumes easily fails as these enormous amounts are hard to grasp, but imagine a cube, six by six kilometres, weighing approximately 280 billion tonnes.
As an old proverb goes, ‘one man’s trash is another man’s treasure’. To miners, mine tailings are a costly by-product, which are difficult to manage due to the large quantities. They can pose a safety risk due to the instability of storage facilities further hampered by the material fineness and moisture content. Some of these challenges are mitigated with tailings storage solutions such as dry-stacking, backfilling the tailings material in old mine pits, and using them as aggregates in the construction industry. However, for many miners, safe and secure tailings storage is still a major issue.
To others, the mine tailings present an opportunity as an alternative building material or potentially even a carbon sink if there is a CO2 source nearby. Recent research shows that mine tailings can be processed to form supplementary cementitious materials (SCM) or geopolymers.
The mining industry recognises the prospect of turning mine tailings into value-added products, while also focusing on reducing tailings altogether.
“Increasing demand for metals critical to the energy transition, such as copper and nickel, will lead to greater production of mine waste like tailings under the current production processes. Alongside our members’ commitment to the safe management of their tailings facilities, ICMM’s goal is to significantly reduce or eliminate tailings. As part of this, we are working with members to make operations at their mine sites more circular by improving process efficiencies to reduce waste at its source, as well as creating value from waste such as tailings,” says Christian Spano, Director of Innovation, International Council on Mining and Metals (ICMM).
Reducing the use of the resource-intensive clinker in cement production is one of the technologies that will provide the largest cumulative CO2 reductions in the 2-degree Celsius Scenario (2DS), according to the International Energy Association. And with the urgency of climate change – no stone should be left unturned by the cement industry in its quest for CO2 saving – reusing mine tailings as a filler or an SCM can be an attractive business-case.
“As a leading supplier to both the cement and mining industry, FLSmidth is in a unique position to engage both parties to establish an efficient and commercially viable value chain for both industries,” says Petithuguenin – working closely with colleagues on both sides of the aisle to connect the dots. “The idea of using mine tailings in construction is not new, but the increasing need for sustainable SCMs is accelerating efforts to establish large-scale processes. In this work, which will include universities and experts from across different sectors, FLSmidth will use its vast process knowledge to optimise designs of the technology needed to produce a quality output.”







Concrete
India’s Cement Sector Cuts Energy Use, but Worker Safety Worsens
iFOREST finds efficiency gains alongside water and safety concerns

Concrete
Ambuja Cements Expects Volume Growth to Outpace Industry in H2
Ambuja Cements sees stronger trade and institutional demand in H2 FY27.

Concrete
JK Lakshmi Cement Begins Rs 110 Billion Assam Plant Project
The 2.5 MTPA integrated cement plant is expected to be completed by FY2029.



India’s Cement Sector Cuts Energy Use, but Worker Safety Worsens

Ambuja Cements Expects Volume Growth to Outpace Industry in H2

JK Lakshmi Cement Begins Rs 110 Billion Assam Plant Project

Leonard Unveils Dual-Head Robotic Arm for Hazardous Industrial Demolition

JK Lakshmi Cement to Expand EV Fleet to 120 Vehicles by March 2027
India’s Cement Sector Cuts Energy Use, but Worker Safety Worsens
Ambuja Cements Expects Volume Growth to Outpace Industry in H2
JK Lakshmi Cement Begins Rs 110 Billion Assam Plant Project
Leonard Unveils Dual-Head Robotic Arm for Hazardous Industrial Demolition
JK Lakshmi Cement to Expand EV Fleet to 120 Vehicles by March 2027
-

 Concrete4 weeks ago
Shiva Cement Merges with JSW Cement
-

 Concrete4 weeks ago
JSW Cement Boards Approve Proposed Shiva Cement Merger
-

 Concrete4 weeks ago
UltraTech becomes first Indian cement firm to cross 2 GW green energy
-

 Concrete4 weeks ago
JSW Cement commissions additional 1 MTPA grinding unit at Nagaur