Economy & Market
Looking EAST
Published
9 years agoon
By
admin
Vaibhav Agarwal of PhillipCapital India reviews the ups and downs of the cement industry in 2017 and also shares the expectations from the industry in 2018.
The year 2017 has remained a challenging year for the cement industry. As per the Department of Industrial Policy & Promotion, cement production fell 2 per cent yoy in April-October 2017. However, the validity of these numbers is uncertain. GV’s checks pointed at 3-4 per cent industry growth in this period, most of which was led by east-India markets. The demand in the east remains most robust (in double digits) followed by central, north, south, and west markets. Cement manufacturers who have been through a consolidation phase or have increased their capacities (organically or inorganically) continue to outperform in terms of volume growth. The industry saw multiple challenges in 2017, most of which were structural and permanent, including:
Latent effect of demonetisation – mainly dented the southern markets
GST rollout – though this was not a major concern, it created teething troubles in the initial months
Strict loading compliances severely dampened the earnings of several manufacturers – Shree Cement remains the worst affected (led to its de-rating by nearly 20 per cent)
Accommodating the largest consolidation move in the sector – UltraTech acquiring Jaypee
Sand mining bans dented cement demand in several states
Pet-coke ban (implemented by the Supreme Court of India, subsequently withdrawn on a conditional basis)Latent effect of demonetisation
In the initial phases of demonetisation, the southern markets, being less-cash, were least impacted. However, this less-cash nature was limited to the cement distribution system while end markets such as real estate and contractors continued to depend on cash and were negatively affected, which in turn hurt distributors. In order to keep business as usual, cement distributors sought support from cement manufacturers in the form of extended credit periods, which increased the working capital cycle of the industry, especially of southern manufacturers.GST rollout for the cement sector
The rollout was smooth, except for initial teething troubles and a few structural changes in the distribution system, which impacted short-term demand dynamics. The rollout led to the proportion of ex-factory sales increasing multifold, as all buyers were inclined to take full credit of the GST impact by paying the requisite GST on freight component. Because of GST, the differential EBITDA contribution gap between trade and non-trade sales reduced significantly (to just about Rs 10 per bag say from Rs 20-25 earlier), as the differential in cost of sales for cement manufacturers narrowed. While this was more of an initial challenge (now streamlined), it is a key structural change in the distribution system of the sector (but for the better).Strict loading compliances: The dampener
After GST, and given the very strong retaliation on overloading by various NGOs/environmentalists, it is a thing of the past for the cement sector. Ground checks revealed extremely strict adherence to overloading norms in almost all regions of the country. GST has made it extremely difficult for cement manufacturers to not to comply with truck-loading norms, as the processes of invoicing and transportation have become much more transparent. It is very unlikely that this will reverse, and ground checks suggest a sustained impact of Rs 4-10 per bag (depending on region of operation and lead distance travelled).
North and east markets have seen very high overloading in the past, so much so that few plants in east India were shut on grounds on non-compliance to environmental norms. The overloading practices of these plants were severely damaging the roads around the plant and hurting the local habitat. In order to avoid local agitation, in many cases, loading compliance has also been applied to dumpers for limestone transfer from mines. Manufacturers such as Shree Cement have been worst hit, visible in the structural de-rating of the stock by nearly 20 per cent.UltraTech buying Jaypee
This was the sector’s largest consolidation move which had wide-ranging implications. It impacted the distribution dynamics of the states in which the acquisitions were made as UltraTech needed to be accommodated in terms of volume share. Volume pushers such as Shree Cement had to compromise on its volume push strategy – likely to be visible in its Q3 numbers. Another problem was the difference in the mindsets of the managements of UltraTech and Jaypee. While UltraTech has always been predominantly a brand-conscious company, Jaypee’s business model has been based on a volume-push strategy. It was difficult to convince erstwhile Jaypee distributors to come on board UltraTech’s strategy.Sand-mining bans dent demand
Sand is essential for cement usage. For manufacturing concrete, with every tonne of cement nearly four tonnes of sand is needed. For all other usage, for every one tonne of cement nearly eight tonnes of sand is required. Broadly, the ballpark ratio of cement to sand is 1:6. Many state governments of the country such as Tamil Nadu, Bihar, West Bengal, Rajasthan, and Uttar Pradesh have been regularly intervening in sand mining, denting the availability of sand. The worst impacted state is Tamil Nadu, where no resolution seems to be in sight. Various NGOs and environmentalists have raised regular concerns about sand mining, because in many cases this activity is done beyond the allotted quota, leading to illegal sand mining. As a result, many states are now depending on ‘crush sand’ for their requirements. The problem is that all states do not have enough crush-sand infrastructure (factories, licenses) – and this continues to affect sand availability. Though this issue is longstanding, 2017 was one of the worst years for cement demand because of lack of sand availability in the states mentioned above.
Pet coke ban implemented by the Supreme Court, subsequently withdrawn In November 2017, the Supreme Court of India issued an order implementing a ban on pet coke usage by cement manufacturers in overall plant operations in Rajasthan, Haryana, and Uttar Pradesh. GV found that many cement manufacturers in other regions voluntarily changed their fuel (to coal from pet coke) anticipating a ban. Few state governments also issued ‘soft notices’ to cement manufacturers; while these did not outright ban pet coke, they seemed to advise cement manufacturers to stop using or avoid using pet coke.
The industry filed a petition arguing that as long as emission norms of cement factories are within prescribed environmental norms, the industry should be allowed to use any fuel. This plea was partially successful and cement manufacturers were allowed to use pet coke in kiln operations, subject to the plant fulfilling environmental norms. However, the power plants may not be able to use pet coke again. This was another setback for the industry in 2017, and if this stay, which lasted for nearly a month, is implemented permanently, it will definitely have cost implications for cement manufacturers.
All the issues that the industry faced in 2017 are structural and will have long-term implications for the sector:
- After demonetisation, the distribution network, aggregate manufacturers, and other raw material suppliers have learned to be more organised.
- GST brought more parity to the industry’s product mix and in many markets the realisations and EBITDA contribution from trade and non-trade sales have moved more closer.
- The largest cement major of the sector UltraTech acquiring Jaypee has brought major consolidation into the sector, which will take a couple of quarters more to play out. It will be a challenging task for both UltraTech and as well as the industry to accept this consolidation move – from UltraTech’s perspective the key challenge will be to ramp up its consolidated capacity utilisation and garner additional premium for products sold from acquired Jaypee plants. This implies improving base cement prices in these markets, which is a long-term structural positive for the sector.
- The most crucial issue, which may continue to overhang the industry in 2018, will be sand – and it will remain state-specific. Tamil Nadu does not seem to have a resolution in the medium term; hence, demand is likely to remain low in this state. Rajasthan has implemented fresh bans towards the end of November 2017. Availability issues in other states are yet to be fully resolved. The key takeaway from this issue in 2017 is that respective states are likely to roll out permanent measures to address the problem of sand availability (by installing more crush sand factories, issuing new licenses, monitoring sand mining more stringently). Though these measures will take time to fall in place, they should help to prevent sand issues cropping up again.
- The pet-coke ban overhang is over for now, but the learning for cement manufacturers is that their plant operations can be interrupted if they do not comply with environmental norms. It is fair to assume that all cement manufacturers are now making doubly sure that plants consistently remain environment friendly, as this will mean lesser complications in the future.
Overall, 2017 has set a roadmap for cement manufacturers and largely addressed or has brought clarity to many structural issues that were directly or indirectly affecting the sector over the last many years. Going forward, the focus of cement manufacturers will remain limited to core business issues. Their performance will be more consistent as norms are now prescribed or being prescribed for several issues which have been impacting them consistently in the past.2018 roadmap
Demand will pick up in 2018 with the pre-election period round the corner; general elections are due to be held in India by 2019 to constitute the seventeenth Lok Sabha. Therefore, 2018 is the only year left for the government to prove its on-theground execution. Construction activity picks up generally 15 months before general elections and this momentum sustains until about 2-3 months before elections. Historically, cement demand growth in pre-election years has been 5-7 per cent. The key risk to 2018 is that if demand does not revive in 2018, cement demand revival will remain questionable until the end of CY19.
With Aachar Sanhita (model code of conduct for political parties) being implemented before elections, new projects cannot be executed. Demand until the end of election will remain sustainable only from the existing projects. Even after the general elections are over, the new elected government usually remains preoccupied with the making policy agendas and cabinet formation. Hence, a good six months in 2019 can be written off with no incremental demand likely from any new projects except for projects that were already under execution before the Aachar Sanhita is announced.Ear to the ground
- Demand in many pockets such as Andhra Pradesh, Telangana, and the whole of east India remains robust. These regions continue to register double-digit yoy growth. Demand in Andhra Pradesh and Telangana is being driven by fast-track execution of irrigation and infrastructure projects while in east India, infrastructure, housing, and projects to build toilets are driving demand.
- Underperforming states like Karnataka have registered a near double-digit yoy growth in recent months. Recovery is seen as a given in Maharashtra and Gujarat.
- Tamil Nadu and Kerala are unlikely to turn around in 2018 because of lack of political stability and sand issues.
- Rajasthan was impacted by sand issues towards the end of November 2017. Still, the demand in this state remains reasonable. Building toilets has contributed significantly to demand in Rajasthan.
- Demand in other pockets of north India is also picking up. Demand in Uttar Pradesh has gained momentum after sand issues were been partially resolved. Strong revival is seen in this state in 2018.
- Overall, demand sentiment is seen rising in 2018 driven by infrastructure, housing, irrigation, and projects related to building toilets gathering pace. Signs of recovery are already visible in specific areas. The worst in terms of demand seems over and demand should improve from here.
What to expect
The industry has been able to gain clarity on several structural issues in 2017. The way forward in 2018 will only be consistency in performance, improvement in operating matrix, and improvement in overall operating parameters. There are still a few notable consolidation moves pending in the industry, which would be meaningfully favorable in the long term. Recent media articles have suggested a strong possibility of Binani Cement being taken over by few cement majors. Names such as UltraTech, Dalmia Bharat, Shree Cement, and a few PE funds have been in the limelight for this deal. Dalmia Bharat has also already confirmed through a press release that it is looking at acquiring Murli Industries. These deals are likely to be executed in 2018, but since these cases are referred to NCLT, the execution timelines may elongate.
Dalmia Bharat seems the strongest and most aggressive candidate to grow inorganically in 2018. Cement majors such as UltraTech and Shree may face the CCI hurdle in large acquisitions in north India. For other mid-tier cement manufacturers such as JK Cement, JK Lakshmi Cement, and India Cements, improving their operating-cost matrix, garnering better market shares through ramp up of utilisations and improving EBITDA contribution through better branding and cost savings will be
the key.
Composite cement is also likely to be a new and big change for the industry in 2018. Cement manufacturers such as Ambuja and JK Lakshmi have already taken this initiative in a few pockets of east India and have been able to garner a premium of Rs 15-20 per bag. Composite cement will add a big cost lever to the industry, as it significantly improves the blending ratio, though the prospects of manufacturing composite cement will be limited to markets where slag is available. 2018 should be a turnaround year for the cement industry and the beginning of a fresh upcycle. Stability of the cost curve, better brand premium and branding exercises, and steady ramp ups in utilisations are the key factors to watch. On the downside, if 2018 proves disappointing, the industry will continue to struggle until CY19.
The article is authored by Vaibhav Agarwal of PhillipCapital India
You may like
Economy & Market
Leonard Unveils Dual-Head Robotic Arm for Hazardous Industrial Demolition
Published
3 days agoon
October 30, 2026By
admin
Leonard unveils Descender Duo, a dual-head robotic demolition arm designed to improve industrial safety and reduce shutdown time by up to 50 per cent.
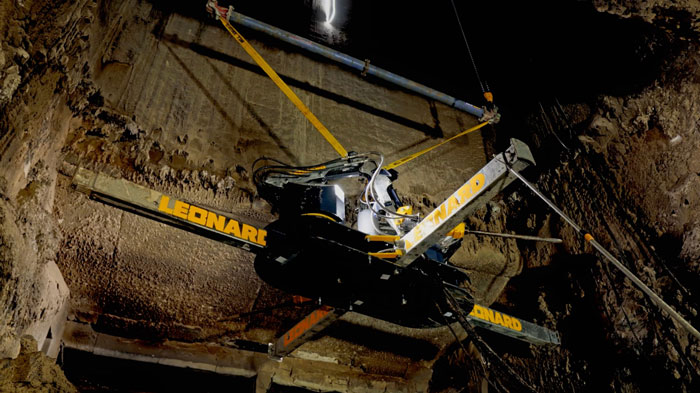
Industrial robotics and refractory services specialist Leonard has launched Descender Duo, a dual-head robotic demolition arm designed to improve safety, accelerate maintenance and reduce shutdown times in hazardous industrial environments. The system made its debut at Lisahally Power Station in Northern Ireland, removing 25 tonnes of slag material within hours.
Developed for the cement, metals, waste-to-energy and petrochemical industries, Descender Duo enables remote-controlled refractory demolition, anchor cutting and welding, and refractory spraying inside boilers, calciners and silos. Its vertical-access design eliminates the need for personnel to enter confined, high-risk spaces during these operations.
Weighing less than two tonnes, the pre-assembled system requires an access opening of just 1.2 m². Supported by an external overhead hoist, it uses electrically operated hydraulic stabilising legs to secure itself inside vessels. The robotic arm offers 360-degree rotation and is suited to vessels approximately 9 m in diameter, with its operating reach extendable through strategically positioned access points.
Equipped with two independently controlled robotic heads, Descender Duo can perform identical or different tasks simultaneously, including refractory demolition, anchor cutting and spraying. Its remote-control system incorporates live camera feeds, allowing operators to monitor operations without entering hazardous environments.
According to Leonard, the technology can deliver time savings of up to 50 per cent compared with manual methods. Its ability to operate at temperatures exceeding 100°C allows maintenance to begin as early as 24 hours after burner shutdown. An all-electric power supply further supports cleaner and more cost-efficient operations.
First Deployment Demonstrates Shutdown Efficiency
The system was first deployed at Burmeister & Wain Scandinavian Contractor’s (BWSC) Lisahally Power Station in Londonderry, Northern Ireland. The facility generates electricity from grade C waste wood, supplying approximately 40,000 homes and businesses.
Leonard and BWSC collaborated to develop a customised solution for the plant’s 26-metre furnace, where extensive external pipework created significant access challenges.
Mark Leonard, Managing Director, Leonard, said, “It required new thinking and rather than step away from the problem we were committed to solving it for the customer, with the customer. We’re relentless in our approach to tackling complex challenges, head-on. We took our years of cement plant experience, coupled with our working knowledge of the BWSC plant, and designed, engineered and tested a completely new vertical solution within just seven weeks from that initial conversation with the customer. That solution was the Descender Duo as we know it today.”
Traditionally, the furnace required a cooling period of up to 36 hours before preparatory work could begin, followed by manual slag removal using rope-access personnel. With Descender Duo, work commenced just 24 hours after shutdown, reducing downtime by up to one day.
The deployment removed 25 tonnes of slag within hours, eliminated the need for at least six workers to enter the hazardous furnace interior and saved 26 hours in the shutdown programme.
“The effectiveness exceeded expectation,” said Martin Doran, Plant Manager at Lisahally Power Station.
“When the Descender Duo concept was first discussed, we had to spend some time with the team from Leonard looking at how it was going to be moved into the furnace. Every site is different and that presented its own challenges, but nothing that the team couldn’t overcome. Once it was installed we were hugely impressed by its efficiency.”
Expanding Industrial Robotics Applications
Descender Duo joins Leonard’s existing portfolio of robotic maintenance solutions, including the Axis horizontal-access arm, Nano confined-space access arm, Charger cement mill media recharging system and Calibre cement mill media grading system.
Headquartered in Northern Ireland, Leonard provides robotic refractory demolition, installation, inspection and industrial maintenance services across the cement, metals, energy, biomass, glass and civil engineering sectors.
Formerly known as G Leonard, the company has more than 35 years of industry experience and operates across Europe, North America, the Middle East, Africa and Asia-Pacific.
The latest innovation reinforces Leonard’s focus on replacing hazardous manual processes with robotic systems that improve workforce safety, enhance operational efficiency and minimise industrial downtime.
Concrete
Martin Engineering Appoints Ashwini Khunte as India General Manager
Published
3 days agoon
October 30, 2026By
admin
Martin Engineering names Ashwini Khunte India General Manager to strengthen operations and drive growth across key bulk material handling sectors.
Pune
Martin Engineering, a global provider of bulk material handling solutions, has appointed Ashwini Khunte as General Manager of its India business, strengthening its leadership as the company expands its presence across the country’s cement, mining, steel, power and infrastructure sectors.
Khunte brings more than a decade of experience with Martin Engineering, having joined its Indian operations in 2013 as a Design Engineer, shortly after the company established its presence in the country in 2012.
A mechanical engineer by qualification, she spent her initial five years developing bulk material handling solutions in collaboration with the company’s operations team. During this period, she gained extensive experience addressing operational challenges in the steel, cement and coal industries. She subsequently moved into project engineering, managing major engineering, procurement and construction (EPC) and original equipment manufacturer (OEM) projects from initial enquiry to commissioning. Her responsibilities later expanded to overseeing Martin Engineering’s conveyor product portfolio in India, involving customer engagement, technical presentations and site visits across heavy industries.
In 2024, Khunte was promoted to Head of Sales & Marketing for the company’s Europe, Middle East, Africa and India (EMEAI) region. The position broadened her international market exposure and strengthened her strategic and commercial leadership capabilities.
Commenting on her appointment, Ashwini Khunte, General Manager, Martin Engineering India, said: “India represents a tremendous opportunity for Martin Engineering. The country’s continued investment in cement, mining, steel, power and infrastructure is creating increasing demand for safer, cleaner and more productive bulk material handling, and that’s exactly what we do. My priority will be to build on the strong foundations already established in India, while continuing to develop our people, strengthen customer relationships and bring practical solutions to the challenges faced by our industry.”
Robert Whetstone, Area Vice President – EMEAI, Martin Engineering, highlighted Khunte’s technical expertise, market understanding and leadership experience.
“Ashwini brings an exceptional combination of technical understanding, customer knowledge and commercial leadership. She has grown as Martin Engineering has grown, and has consistently demonstrated outstanding capability to transform her expertise into practical solutions. Her knowledge of the Indian market, together with her international experience, makes her ideally suited to lead our India business through its next stage of growth for years to come.”
Since establishing its Indian business in 2012, Martin Engineering has expanded its local workforce, manufacturing capabilities and dealership network. The company supplies conveyor products, transfer point solutions, material flow aids, training and technical support to bulk material handling industries. Khunte’s appointment positions the company to further strengthen customer relationships and expand its solutions portfolio in India’s growing industrial and infrastructure markets.
Concrete
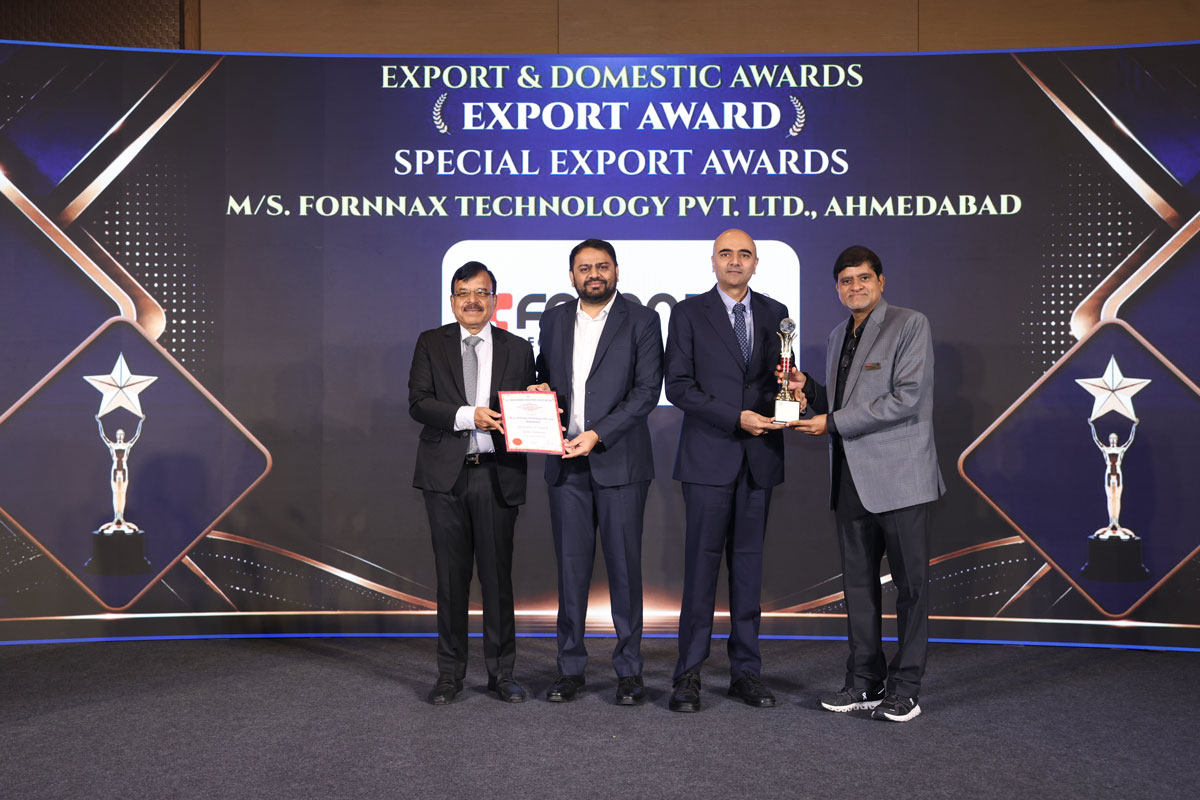
Fornnax Wins AIRIA’s Special Export Award for Rubber Machinery in 2025-26
Published
2 weeks agoon
October 19, 2026By
admin
Fornnax Technology Pvt. Ltd. has been honoured with the Special Export Award – Rubber Machinery for 2025–26 by the All-India Rubber Industries Association (AIRIA), in recognition of its highest exports of tyre recycling plants to the European region.
With more than a decade of experience in India’s tyre recycling industry, Fornnax has contributed to the development of advanced recycling technologies and infrastructure. The company currently holds a 90% market share in India’s domestic tyre recycling sector, while exports account for 30% of its business, spanning markets such as Europe, Australia and the GCC.
The award marks another milestone for Fornnax, whose tyre recycling lines and advanced shredding technologies are supporting the growth of the circular economy in India and international markets.
Commenting on the recognition, Mr. Jignesh Kundaria, Founder and Director of Fornnax, said:
“This honour from AIRIA is a reflection of an incredible journey we have undertaken over the years. When we started Fornnax, there was no established recycling industry in India to follow. We chose to build for the future instead. Today, when you see India’s tyre recycling sector, it has already transformed into a dynamic, high-growth industry and we are extremely proud to have played our part in building it.”
Unlike standalone equipment suppliers, Fornnax focuses on developing complete, high-capacity recycling infrastructure. Its integrated systems combine multiple stages of shredding and size reduction to enable efficient, continuous operations. This system-level engineering approach helps recycling operators improve throughput, equipment reliability and operational consistency.
The recognition reinforces Fornnax’s commitment to developing engineering technologies that contribute to a more efficient and circular recycling ecosystem.
Looking ahead, the company aims to expand its international presence while continuing to develop advanced shredding and recycling solutions to address the growing volumes and evolving requirements of the global recycling industry.
For more information, visit: www.fornnax.com
JK Lakshmi Cement Begins Rs 110 Billion Assam Plant Project
Leonard Unveils Dual-Head Robotic Arm for Hazardous Industrial Demolition
JK Lakshmi Cement to Expand EV Fleet to 120 Vehicles by March 2027
JK Lakshmi Cement Breaks Ground on Rs 110 bn Assam Plant
Martin Engineering Appoints Ashwini Khunte as India General Manager
JK Lakshmi Cement Begins Rs 110 Billion Assam Plant Project
Leonard Unveils Dual-Head Robotic Arm for Hazardous Industrial Demolition
JK Lakshmi Cement to Expand EV Fleet to 120 Vehicles by March 2027
JK Lakshmi Cement Breaks Ground on Rs 110 bn Assam Plant
Martin Engineering Appoints Ashwini Khunte as India General Manager
Trending News
-
Concrete4 weeks agoShiva Cement Merges with JSW Cement
-
Concrete4 weeks agoJSW Cement Boards Approve Proposed Shiva Cement Merger
-
Concrete4 weeks agoUltraTech becomes first Indian cement firm to cross 2 GW green energy
-
Concrete4 weeks agoJSW Cement commissions additional 1 MTPA grinding unit at Nagaur