India produced nearly 491 million tonne of cement in FY2026, however the next tonne will not look like the last. From LC3 and AI-run kilns to carbon capture and circular mining, we explore the innovations moving from pilot projects to the plant floor across the cement value chain.
India’s cement industry is at a critical juncture, with infrastructure investment, urbanisation and housing demand driving production growth. According to the India Brand Equity Foundation (IBEF), India’s cement production reached approximately 491.4 million tonne in FY2025–26. This growth is intensifying the need for greater energy efficiency and lower environmental impact, making AI, automation, advanced process control, low-carbon cement and alternative fuels increasingly important.
Decarbonisation remains a major challenge, as emissions arise from both fuel combustion and clinker production. According to NITI Aayog’s Roadmap for Cement Sector Decarbonisation, the sector emitted approximately 246 million tonnes of CO2 equivalent in 2023, with an emissions intensity of around 0.63 tonnes of CO2 equivalent per tonne of cement. Addressing this requires innovations in clinker substitution, waste heat recovery, renewable energy and carbon capture. The International Energy Agency (IEA) identifies carbon capture and low emissions production technologies as key to the sector’s net zero transition, making commercially viable innovation essential for balancing growth, competitiveness and sustainability.
Next generation cement and low carbon materials
Reducing clinker dependency is one of the most practical pathways to lowering cement’s carbon footprint. Traditional Ordinary Portland Cement (OPC) typically contains 90 per cent to 95 per cent clinker, whose production releases significant process emissions. According to NITI Aayog’s Roadmap for Cement Sector Decarbonisation, blended cements already account for approximately 73 per cent of India’s cement production, reflecting the growing role of alternatives such as fly ash and blast furnace slag. Supplementary cementitious materials (SCMs) can replace a portion of clinker, reduce emissions while supporting resource efficiency. The next wave of innovation includes limestone calcined clay cement (LC3), Portland limestone cement and multi component blends, which offer opportunities to reduce clinker content while maintaining the performance required for different construction applications.
The focus is now shifting towards expanding the range of low carbon materials available to manufacturers. NITI Aayog’s Scenarios Towards Viksit Bharat and Net Zero – Sectoral Insights: Buildings notes that LC3 can reduce the clinker ratio to approximately 50 per cent, compared with the 90 per cent to 95 per cent typically found in OPC. India also has an estimated 1.5 billion tonnes of utilisable calcined clay reserves, according to NITI Aayog’s cement decarbonisation roadmap, offering significant potential for wider adoption.
However, scaling these materials will require reliable supply chains, performance based standards, further research and industry acceptance. The long term opportunity lies in developing innovative cement formulations that reduce emissions while delivering the strength, durability and cost effectiveness required by India’s expanding construction sector.
Smart manufacturing: AI, automation and digital twins
Digitalisation is transforming cement plants from conventional production facilities into data driven operations. Artificial intelligence (AI), machine learning and advanced process control can optimise kiln temperatures, stabilise raw mill operations, improve fuel efficiency and reduce equipment downtime. Predictive maintenance uses sensor data to identify potential equipment failures before they disrupt production, while digital twins enable operators to simulate process changes and evaluate their impact. These technologies are particularly valuable in an energy intensive industry where even small improvements in process stability can translate into significant operational savings.
Prerak Manisha Shah, Founder and CTO, Cogniify.ai, says, “When unexpected breakdowns happen in manufacturing, it can produce a vast amount of disruption in manufacturing. With predictive maintenance, AI programmes use data about vibration, temperature of bearings, electric current of the motor and operating time of the equipment in order to determine when the machine is likely to break.”
The benefits are increasingly quantifiable: a study published in Energy and AI in September 2026 by researchers at Lawrence Berkeley National Laboratory estimated that AI deployment could potentially reduce primary energy demand and associated CO2 emissions in cement manufacturing by 3 per cent to 9 per cent, subject to the assumptions used in its scenarios. Meanwhile, the Cement Manufacturers’ Association highlights that advanced process control can reduce fuel consumption by 3 per cent to 5 per cent and increase throughput by 2 per cent to 3 per cent.
Digital twins, as demonstrated in Holcim’s 2023 launch of a real time virtual model of a cement plant in Switzerland, further combine sensor data, analytics and machine learning to support predictive maintenance and more reliable operations. Together, these innovations show how smart manufacturing can deliver measurable gains in productivity, energy efficiency and emissions performance.
Alternative fuels and renewable power
Energy innovation is central to reducing the cement industry’s dependence on coal and other conventional fossil fuels. Manufacturers are increasingly exploring refuse derived fuel (RDF), biomass and other waste derived fuels, alongside waste heat recovery systems that convert excess process heat into electricity. Renewable energy integration through solar and wind power can further reduce emissions associated with electricity consumption, while modern kiln technologies and improved combustion control help optimise thermal efficiency. Together, these solutions offer opportunities to reduce fuel costs, divert waste from landfills and strengthen the industry’s energy resilience.
Kiranmai Sanagavarapu, Director – Low Carbon Solutions, Fuller Technologies, says “ Flash calcination relies on rapid heating and short residence times, meaning the process responds quickly to changing conditions. For clays tested by Fuller, the useful activation range was about 750–850°C; however, the optimum varies with the clay. Insufficient thermal treatment can leave activation incomplete, while excessive heating can cause sintering and reduce reactivity. Gas-solids contact and residence-time distribution must also be controlled.”
According to NITI Aayog’s Roadmap for Cement Sector Decarbonisation, alternative fuels currently provide only around 4 per cent of the Indian cement industry’s total energy input, highlighting the potential to replace coal and pet coke with biomass and refuse derived fuel (RDF). The roadmap identifies municipal solid waste as a significant opportunity, projecting that its use could help meet approximately 20 per cent of the sector’s thermal energy requirements by 2030, provided collection, processing and supply chains are strengthened.
Dr SB Hegde, Professor, Jain College of Engineering and Technology, Hubballi, says, “Every major decarbonisation route, from alternative fuels and LC3 to carbon capture, depends on precise, data-driven control. A kiln that already wobbles on coal will wobble far more on refuse-derived fuel, and a carbon capture unit will only be as efficient as the kiln feeding it. In my view, the large wave of new Indian capacity is a once-in-a-generation chance to build plants that are digital from day one, rather than retrofitting them later at higher cost.”
Renewable power and waste heat recovery offer complementary opportunities to cut energy costs and emissions. According to the Confederation of Indian Industry’s energy benchmarking data, India’s cement industry has developed more than 1,000 MW of waste heat recovery capacity, while leading plants have achieved thermal substitution rates of up to 30 per cent, compared with an industry average of 2 per cent to 7 per cent. Scaling these solutions, alongside efficient kiln technologies and greater solar and wind power integration, will require investment, reliable fuel supplies and infrastructure that enables manufacturers to move towards cleaner, more resilient energy systems.
Breaking new ground in carbon capture and emissions control
Reducing emissions from cement plants requires solutions that address both fuel combustion and the chemical reactions involved in clinker production. Advanced electrostatic precipitators and bag filters help control particulate matter, while selective catalytic reduction (SCR) and selective non catalytic reduction (SNCR) technologies target nitrogen oxides (NOx). Sulphur oxide (SOx) emissions can be managed through process optimisation and suitable gas cleaning systems. Beyond conventional controls, carbon capture, utilisation and storage (CCUS) is emerging as a critical technology for tackling process emissions that cannot be eliminated through energy efficiency or fuel switching alone.
The scale of the opportunity is significant. NITI Aayog’s Roadmap for Cement Sector Decarbonisation identifies CCUS as a technology capable of mitigating up to 50 per cent of process emissions, provided it can be deployed at scale. The roadmap also highlights the need for demonstration projects, investment and supportive policies to accelerate adoption. For Indian cement manufacturers, combining advanced pollution control systems with carbon capture and utilisation technologies could help address both conventional air pollutants and hard to abate CO2 emissions, making emissions control a key frontier for industrial innovation.
Mining, raw materials and circular economy innovations
Innovation in mining and raw material management is helping cement manufacturers reduce dependence on virgin resources and improve resource efficiency. Advanced quarry planning, drone surveys and digital geological mapping can support more precise extraction, while industrial by products such as fly ash and blast furnace slag can replace a portion of conventional raw materials and clinker. According to the Ministry of Power’s Annual Report 2023–24, cement and concrete accounted for 29.96 per cent of India’s fly ash utilisation in 2022–23, highlighting the sector’s role in converting industrial waste into useful construction materials.
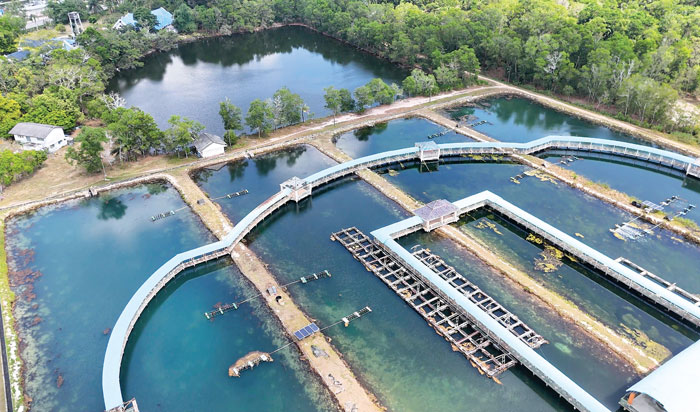
Dr KV Reddy, Chairman, CMA Committee, says “One of the most distinctive contributions of the cement industry to water stewardship comes from limestone mining operations, where responsibly managed mine pits can capture and store substantial quantities of monsoon rainfall, serving as water reservoirs for operational needs, reducing freshwater dependence and, where hydrogeologically appropriate, supporting groundwater recharge. The industry’s water stewardship experience includes mine pit reservoirs, check dams, percolation tanks, recharge shafts and rejuvenated village ponds as complementary water conservation measures. The distinction between harvested rainwater and groundwater is particularly important. Rainwater accumulated in mine pits is already being used for dust suppression, mining operations, greenbelt development and other purposes while reducing dependence on groundwater.”
The opportunity continues to grow: according to the Press Information Bureau, India generated 340.11 million tonnes of fly ash in 2024–25, of which 332.63 million tonnes was utilised; the cement industry accounted for 27 per cent of the total generated. Cement manufacturers are also investing in water recycling and reuse. For example, Dalmia Bharat’s Integrated Annual Report 2024–25 reports specific water consumption of 167 litres per tonne of cementitious material, down from 171 litres in FY2023–24. Together, circular material use, efficient quarrying and water recycling can conserve natural resources, reduce waste and strengthen the industry’s long-term resilience.
Innovations in logistics, quality and supply chains
Logistics and supply chain innovation is becoming increasingly important as cement manufacturers seek to reduce costs, improve delivery reliability and minimise material losses. According to the Cement Manufacturers’ Association (CMA), logistics costs can account for 30 per cent to 35 per cent of total costs in the cement industry, making efficient transportation and material handling critical to competitiveness. Technologies such as GPS enabled fleet tracking, RFID tags, automated weighbridges, digital dispatch systems and logistics control towers are helping manufacturers improve shipment visibility, optimise routes and reduce truck turnaround times.
Rüdiger Reckmann, Technical Sales Manager, HAVER & BOECKER, says, “Modernisation doesn’t just extend equipment life; it can also improve the day-to-day experience on the floor. Beyond digital and control system updates, plants can also realise major performance gains through targeted mechanical and safety upgrades. Fewer stoppages result from specific upgrades such as sealed or redesigned filling tubes that reduce spillage, improved dust collection and interlocks that limit dust accumulation. Smart diagnostics and alarm systems help maximise plant availability by avoiding unnecessary shutdowns. These same changes make it easier to meet safety and explosion-protection requirements while cutting the time spent clearing waste and responding to emergency maintenance requirements. Staff can concentrate instead on keeping the line moving, rather than dealing with failing controls.”
Digitalisation is also transforming quality assurance and supply chain planning. In its Integrated Report 2024–25, JSW Cement describes the use of GPS tracking, a Logistics Control Tower and a Yard Management System to improve fleet visibility, truck sequencing and internal material movement. Meanwhile, Ambuja Cements’ Integrated Report 2025–26 reports that logistics turnaround at 17 plants improved by approximately 25 per cent through digital and operational initiatives. Integrating these systems with automated quality testing, bag tracking and data driven inventory planning can help cement producers strengthen traceability, reduce dispatch errors and ensure consistent product quality from the plant to the customer.
Conclusion
Path breaking innovation in the cement industry is no longer confined to individual technological breakthroughs; it lies in integrating advances across materials, manufacturing, energy, emissions control, mining and logistics. From low carbon cement formulations and AI driven process optimisation to alternative fuels, carbon capture and circular resource utilisation, these developments offer opportunities to improve productivity while reducing environmental impact. However, translating innovation into measurable outcomes requires sustained investment in research and development, modern infrastructure, skilled talent and collaboration between cement manufacturers, technology providers, research institutions and policymakers.
As India’s cement demand continues to grow, the industry must focus not only on adopting emerging technologies but also on scaling solutions that are commercially viable, operationally reliable and environmentally effective. Greater emphasis on measurable performance, technology integration and industry wide knowledge sharing will be essential to accelerating this transition. The future of cement manufacturing will be shaped by companies that can balance production efficiency, cost competitiveness and decarbonisation, transforming innovation from a strategic ambition into a tangible driver of long-term industrial growth.










 Concrete4 weeks ago

 Concrete4 weeks ago

 Concrete4 weeks ago

 Concrete4 weeks ago