Economy & Market
Innovative Strategies for Cost Optimisation
Published
2 years agoon
By
admin
S Sathish, Partner and National Sector Leader – Industrial Manufacturing, KPMG India, explores key levers across energy, logistics, and manpower to drive efficiency and resilience.
Over the last two quarters, margins of cement players are under pressure and some of the players have shown a 25 to 30 per cent reduction in their EBITDA. While the key reasons can be attributed to the external situation of rising material prices and constraints to increase cement price, all the players are quite actively looking at strategies to enhance the bottom line to stay prosperous. The need of the hour for cement players is to think of innovative cost optimisation practices. We will deep dive into optimisation strategies for three major cost heads in this article.
Optimisation opportunities
A: Energy and fuel cost is one of the key costs for cement sector. While a lot of focus has been done on energy consumption optimisation, waste heat recovery areas, buying optimisation of coal and petcoke is a new area, which cement companies are focusing on.
Identifying the right import supplier and source country combination can help in optimising the buying cost. We have seen that if this aspect is intelligently done can lead to an optimisation of 8 to 10 per cent in fuel costs. This would entail mapping the importers in India, quantities they import, companies they supply and deciding the right contracting strategy with the right ones.
Analysing the quality of different sources of coal such as Indonesian, South African, Middle Eastern, American, etc. and deciding the right fit for your organisation based on equipment capability can help in optimisation.
Having an AI-based model to optimise the buying cost of fuel, based on petcoke price trends, price trends of coal from different sources, both import and domestic, quality variation analysis of different sources, etc. is a best practice adopted by some leading players to optimise fuel buying.
Exploration with green fuels and alternative fuel resources is another big area cement players are working on.
B: Logistics cost is the next biggest cost driver in cement sector. While prima facie this cost appears to be driven more by demand requirement and market conditions, a sharper focus on drivers of spend will help in optimising this cost.
Many companies operate with a long tail of transporters for each lane to de-risk themselves from the cost of unavailability of trucks. However, the share of business gets split across multiple transporters leading to lesser bargaining power. Some companies operate based on three quote negotiations even today where the breakup of price is opaque to the buyers. Leading companies adopt zero-based costing methodologies / should be cost modelling to build up the should be costs and use that for negotiation coupled with share of business optimisation. AI is used by some of the companies here as well in deciding the right share of business based on supplier price and transporter performance scores.
Synergy leverage between outbound, inbound, primary and secondary logistics is another innovative way of optimisation. Traditionally inbound and secondary logistics is managed by procurement function and outbound and primary transport is managed by sales function. This structurally does not allow for optimisation of spend and we have seen that the same transporter manages between two different functions and in some cases even with different rates for the same distance. Structured negotiation with the total spend share for the transporter can give substantial optimisation. Many companies have changed the logistics organisation structure between inbound and outbound logistics under a common reporting structure.
Load consolidations and right carrier/mode mix optimisation is a big lever. Based on analytics of load in a particular direction and the vehicle type used provides one with an option of increasing the vehicle capacity. An increased vehicle capacity can reduce the number of trips and at the same time reduces the logistics cost per ton. Loadability is often not measured which if optimised can help in reducing the costs. Evaluating the
right logistics mode in terms of road, rail and sea transport based on destination is another
lever used by different industries. Some of the leading cement players are exploring waterways to become more sustainable.
C: Manpower costs is one of the next biggest costs in cement sector. We can look at key strategies for contract manpower costs and white collar costs.
Typically contract manpower costs are a big contributor to manpower costs. Companies adopt the piece rate model or man-day rate model in areas such as packing where a daily output is involved. While a piece rate model may appear optimal, many companies don’t really get into details of how the piece rate is arrived at. Assumptions taken for piece rate calculation such as number of people planned to be deployed, skill levels of people considered, and wage rate assumed for each level leave a lot of room for optimisation. Once the value is unearthed, companies rationalise the number of contractors and increase share of business with a few contractors to realise the value unearthed.
Another innovative lever in white collar manpower is evaluating the people deployment/ cost incurred by core and non-core functions and exploring possibilities of managed services for non-core functions. Payroll/ IT service functions are mostly outsourced by many companies but companies today have started looking at other subfunctions/functions such as recruitment / tax / accounting where service providers are asked to reduce cost of service year on year through automation and digital interventions and. Another trend we see is even the non-core activities of core functions like procurement are being actively outsourced. The strategy here is to make variable the fixed costs, which helps companies in downturn to still stay profitable.
While we have deliberated on strategies for three top cost heads with a few levers, there are other cost heads such as indirect spend and packaging costs, which also provide more optimisation potential. The need of the hour for cement players is to think of an innovative approach to cost optimisation with new levers, to achieve higher order bottomline benefits.
About the author:
S Sathish, Partner and National Sector Leader- Industrial Manufacturing, KPMG, is responsible for increasing revenues for the industrial manufacturing sector, and increasing penetration in sector key accounts/corridors. He has rich experience in auto, industrial manufacturing and consumer market sectors. He has delivered more than 100+ engagements in India and abroad in his 27 years of experience.
Concrete
Nuvoco Vistas, CleanMax Partner for Wind-Solar Hybrid Project in Rajasthan
Published
7 days agoon
September 29, 2026By
admin
The project – comprising 20 MW of wind and 26.4 MWdc of solar capacity – will support Nuvoco’s cement operations with cleaner power while strengthening its renewable energy and decarbonisation strategy.
Mumbai, September 29, 2026
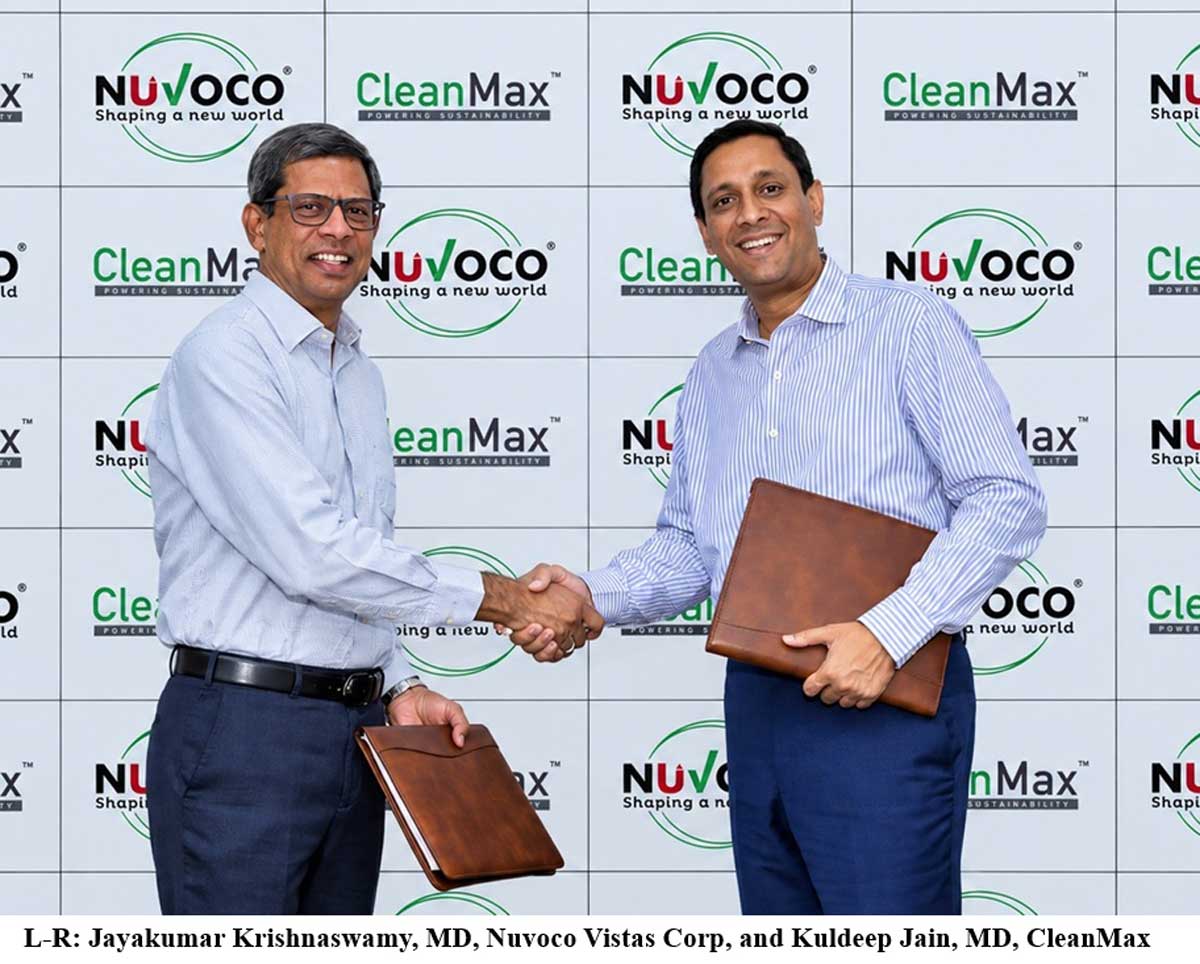
Nuvoco Vistas Corp Ltd, part of Nirma Group and one of India’s leading cement companies, has partnered with Clean Max Enviro Energy Solutions Limited (CleanMax), a renewable energy solutions provider for the commercial and industrial (C&I) sector, to develop a 46.4 MW wind-solar hybrid renewable energy project in Rajasthan.
The project will support Nuvoco’s cement operations with cleaner power while strengthening its renewable energy and decarbonisation strategy. It is expected to increase the share of renewable energy in Nuvoco’s power mix, reducing fossil fuel consumption and associated emissions.
Developed by CleanMax, an Independent Power Producer (IPP), at Bhikamkhore, Rajasthan, the project will comprise 20 MW of wind capacity and 26.4 MWdc of solar capacity, along with a 2-MWh Battery Energy Storage System (BESS). Power generated from the facility will be supplied to Nuvoco through the State Transmission Utility (STU) Open Access network.
The hybrid project is expected to generate approximately 100 million units (MU) of renewable electricity annually and help avoid around 1,25,485 tonnes of CO₂ emissions every year across Scope 1 and Scope 2 emissions.
The initiative supports Nuvoco’s ongoing efforts to reduce the carbon intensity of its manufacturing operations through renewable energy adoption, Waste Heat Recovery Systems (WHRS), energy-efficiency measures and increased use of alternative fuels. It also aligns with the company’s DIRE (Digitalisation, Innovation and Renewables) agenda, which focuses on climate action, renewable energy transition, water stewardship, circularity and biodiversity conservation across its manufacturing ecosystem.
Commenting on the initiative, Jayakumar Krishnaswamy, Managing Director, Nuvoco Vistas Corp Ltd, said, “This marks an important step in advancing Nuvoco’s journey towards more sustainable and resilient operations. Our collaboration with CleanMax will increase the share of renewable energy across our Rajasthan operations, strengthening our energy mix while improving long-term cost efficiency and reducing our dependence on conventional power sources. Initiatives such as these reinforce our commitment to operational excellence and responsible growth, while supporting our vision of Building a Safer, Smarter and Sustainable World.”
Kuldeep Jain, Founder and Managing Director, CleanMax, said, “Cement plants run continuously, so the power behind them has to be dependable for decades, not years. We’re seeing manufacturing industries view clean energy as an integral part of their core operations and long-term strategy. Our partnership with Nuvoco reflects that shift, and we’re pleased to support its decarbonisation journey. This wind-solar hybrid project is designed to deliver long-term cost certainty while supporting the Company’s transition to cleaner power.”
Nuvoco has been advancing its sustainability initiatives through renewable energy, operational efficiency and technology-driven solutions. The company operates across Cement, Ready-Mix Concrete (RMX) and Modern Building Materials (MBM) segments, with a presence across East, North and West India.
The company began operations in 2014 with a greenfield cement plant in Nimbol, Rajasthan, and later acquired Lafarge India Limited, which entered India in 1999, along with Emami Cement Ltd in 2020 and Vadraj Cement Limited in April 2025. With planned expansion initiatives, including a new grinding mill at the Arasmeta Cement Plant and multiple debottlenecking projects, Nuvoco aims to achieve a cement capacity of 35 MMTPA.
The company reported total income of Rs 113.62 billion in FY 2025-26, reflecting its continued growth trajectory. Its cement portfolio includes Concreto, Duraguard, Double Bull, PSC, Nirmax and Infracem brands, while its RMX business offers products under Concreto, Artiste, InstaMix, X-Con and Ecodure brands. Nuvoco also provides construction solutions under its Zero M range of modern building materials.
Concrete
UltraTech Cement achieves 100% green energy milestone at Chhattisgarh plant
Published
7 days agoon
September 29, 2026By
admin
UltraTech Cement’s Kukurdih Works becomes its first integrated unit to meet 100 per cent electricity needs through green energy every month.
Raipur (Chhattisgarh)
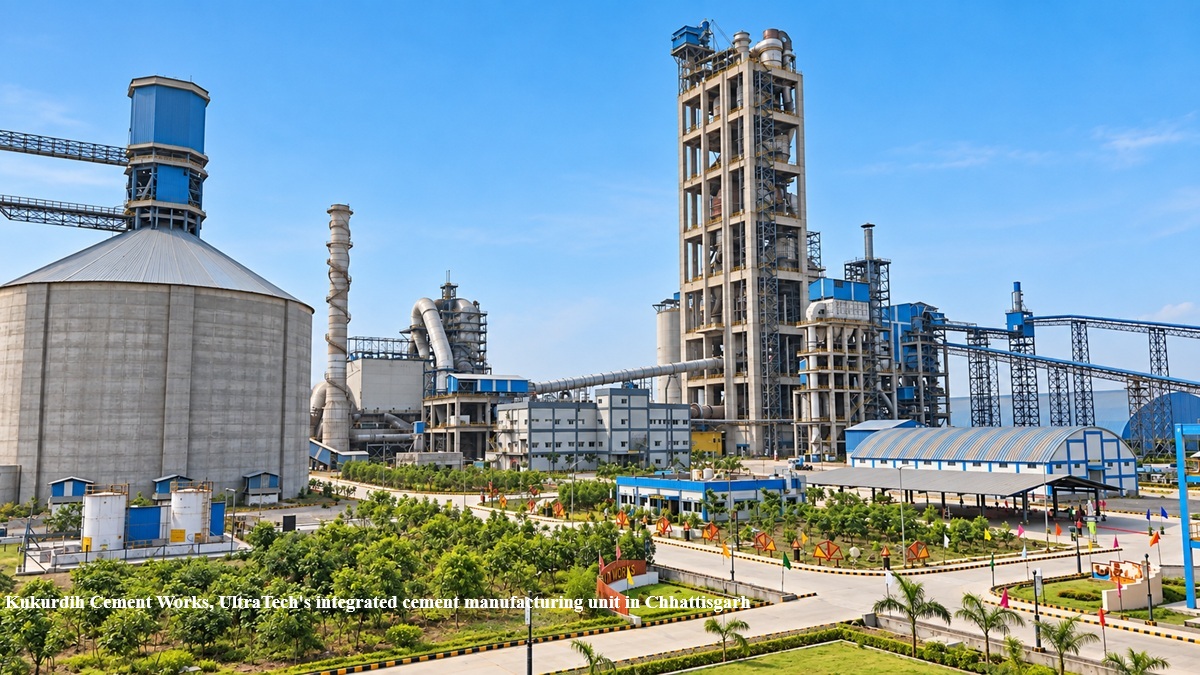
UltraTech Cement Limited, the world’s largest cement company outside China, has achieved a significant decarbonisation milestone, with its Kukurdih Cement Works integrated unit in Chhattisgarh meeting 100 per cent of its electricity requirement through green energy every month since April 2026.
Commissioned in 2024, Kukurdih Cement Works has an installed grey cement capacity of 3.3 million tonnes per annum. The unit achieved this milestone through a combination of renewable power sourcing and Waste Heat Recovery Systems (WHRS), which now collectively meet its entire electricity demand while ensuring operational reliability.
Since April 2026, nearly one-third of UltraTech’s 76 manufacturing units in India have maintained green energy utilisation above 50 per cent of their electricity requirements. Five units, including Kukurdih, have exceeded 95 per cent green energy utilisation. The company is also progressively deploying Battery Energy Storage Systems (BESS) across its network to enable deeper renewable energy integration.
As part of its decarbonisation strategy, UltraTech has not invested in additional captive thermal power capacity for greenfield projects or brownfield expansions at its integrated units for over a decade.
As of Q1FY27, the company’s captive green energy capacity stood at 1,897 MW, comprising 1,463 MW of renewable energy capacity from solar, wind and hybrid sources, along with 434 MW of WHRS capacity. Under its RE100 commitment, UltraTech aims to increase the share of green power in its total energy mix to 85 per cent by 2030 and achieve 100 per cent by 2050.
UltraTech Cement Ltd, the cement flagship company of the Aditya Birla Group, is a $10-billion building solutions company and the largest cement producer globally by sales volume outside China. The company has a total grey cement capacity of 210.1 MTPA and white cement/putty capacity of 3.5 MTPA. It is a signatory to the GCCA Climate Ambition 2050 and has committed to the Net Zero Concrete roadmap announced by GCCA.
Praveen Vashistha, Founder, Gxpress Solutions, speaks about building a holistic logistics network that encompasses latest technology and current challenges faced by logistics service providers.
Logistics may seem to only entail transporting a package from one location to another. However, there is more to this term than just that. Logistics refers to the entire process of controlling all movement, transfers and decisions in the correct way at the right time and cost and with the desired level of visibility.
People nowadays want to receive more than just the delivery. They want quick, efficient, reliable and transparent logistics service. On the other hand, companies are facing higher operating costs, broken supply chains, congested cities, changing habits of consumers and growing complexity of logistics services. In this situation, a full logistics package is gaining importance not only as a competitive advantage but also as a necessity for a successful business.
The main challenge lies in uniting the first mile, the middle mile and the last mile into one seamless process.
The journey begins before the package moves
First-mile logistics may be the least recognised part of the logistics chain, but they have a crucial influence on all that follows.
This stage starts from the moment the shipment leaves the manufacturer, supplier, farm, warehouse or distribution centre. Depending on the industry, first-mile logistics may involve grouping shipments from multiple suppliers, compiling paperwork and checking the inventory before sending the shipments to a central hub.
Flaws in first-mile logistics produce effects later down the supply chain. Delays in cargo pickup can affect warehouse operations; improper packaging can damage goods in transit; and incorrect inventory information may cause stockholding or unnecessary replenishments.
This is why building a reliable network involves simplifying the operations done at the beginning of the supply chain.
Companies require accurate demand forecasts, supplier visibility, standard procedures, and software to capture information from the moment a shipment enters the supply chain. Route planning and fleet management are also important at this stage, especially as it may involve contacting multiple suppliers.
The main goal is simply to make the first mile predictable.
The middle mile: Where scale meets complexity
When products leave the original site, they travel through the ‘middle mile,’ which connects fulfilment centres, warehouses, sorting centres, and regional distribution points. In this phase, logistics networks begin operating on a large scale. A shipment can pass through several facilities before reaching the final destination. Each additional transfer entails the risk of delay or damage and information losses. Accordingly, the ideal solution is not to minimise the number of transfers but rather to optimise them. The use of hub-and-spoke networks, regional distribution centres, and strategically placed distribution centres can help companies shorten transportation routes and optimise distribution costs. Besides, data can be used to determine the optimal placement of inventories.
For instance, a retailer may find that it takes more time and is more expensive to deliver goods to customers if everything is stored in a central warehouse. Meanwhile, regional distribution helps meet the customer’s needs quicker and more efficiently.
The last mile is where the customer judges you
When it comes to the logistics experience, the customer experience comes down to the delivery. While the last mile might comprise a small part of the entire journey in actual distance, it could also entail expensive and difficult processes. Delivery runs through densely populated cities, through traffic jams, through unsuccessful delivery attempts, and through changing consumer preferences and narrowed time frames.
Customers want to have control over their delivery. Delivery means that customers expect to know the exact moment when their order is delivered. They need to receive current updates about their orders and the ability to decide whether they want scheduled deliveries, or whether they want their order to be dropped off at a designated location far from their house.
As a result, last-mile logistics must incorporate both efficiency and experience. The technology may be used to ensure timely and accurate delivery, through such products as route optimisation and real-time delivery tracking.
However, technology is not enough to guarantee success in terms of last-mile delivery. Knowledge of the local area is still an important aspect that contributes to successful delivery.
One network, not three separate operations
First, the common mistake that organisations can make is treating the first mile, the middle, and the last mile separately.
An effective first mile of logistics does not matter much if the shipment waits in a hub for many hours. A perfectly working warehouse does not make a happy customer if the last-mile delivery fails. Therefore, even the fastest last-mile delivery can become an expensive operation if the supply is not well geographically positioned.
The three moments should work together as one whole system.
This implies having a common view on inventory, transport capacities, shipment statuses and demand. The Transportation Management System, Warehouse Management System and order management system should give information to each other instead of acting like separate islands.
That is where real-time information comes into play!
If something happens, such as a vehicle gets delayed, the company has to know that from the start. If not, someone from Customer Service should be informed about the situation.
Visibility is the new infrastructure
Previously, companies had to rely on physical assets, such as warehouses, trucks, and sorting facilities, to create their logistics networks. Today, they have an additional layer of technology providing visibility.
Command-and-control systems now include GPS tracking, Internet of Things devices, bar-coding, RFID, cloud computing, artificial intelligence, and analytics, which allow companies to know what the goods are doing, how well they are doing, and what is going to happen next.
Predictive analytics reveal possible delays. AI-powered forecasting increases availability. Digital dashboards enable the manager to monitor all operations in one place. The efficiency of such technologies is not measured in the amount of information they gather, but rather in their capability of converting data into knowledge.
Logistics managers should be able to answer the following questions: Where is it? When is it supposed to arrive? What causes the delay? What impact does it have? Can it be delivered some other way? How much will it cost?
The sooner the answers are given, the more resilient the logistics system is.
Resilience must be designed into the network
The events of recent years have highlighted the vulnerability of interconnected supply chains. Geopolitical tensions, bad weather, a lack of labour, poorly developed infrastructure and an unexpected spike in demand are some events that can cause problems for logistics systems without prior notice. Thus, companies should create an end-to-end network not just for normal times but also capable of functioning quickly in problematic situations. In order to create such a network, it is necessary to find alternative suppliers, use several means of transportation, create several routes of delivery, and establish inventory. It is also important to use scenario planning to define what to do if the main hub becomes unavailable or any means of transportation is blocked.
Sustainability: Part of the delivery equation
The future of logistics will also be shaped by environmental considerations.
As delivery volumes rise, businesses are under increasing pressure to reduce emissions without compromising service. Better route planning, load optimisation, electric vehicles, alternative fuels, renewable-energy-powered warehouses and consolidated deliveries can all contribute. The most sustainable shipment is often the one that does not require unnecessary movement in the first place.
Better demand forecasting and inventory placement can reduce empty miles and avoid repeated transportation. Consolidating deliveries can improve vehicle utilisation. Reverse logistics can ensure that products, packaging and materials return efficiently instead of becoming waste.
Sustainability, therefore, should not be treated as a separate initiative. It should be incorporated into network design itself.
The future belongs to connected logistics
An end-to-end logistics network ultimately seeks to close existing gaps between various processes.
Every mile of the process should be interconnected with the other miles. Warehouses should be aware of the restraints imposed by transportation. Delivery crews should be able to know at every moment the inventory at their disposal. Clients must have access to this useful information.
Companies that will be successful in this area will not necessarily be the ones with the biggest fleets or the most warehouses. They will simply be the ones that can employ their resources in the most effective manner.
The future of logistics will be represented by an ecosystem consisting of the combination of the physical aspect, digital intelligence, and personnel decisions. Every mile in the process of delivery is important. However, the key advantage here is getting those miles to work together.
For companies, it means having minimal resistance, enhancing their efficiency and improving customer care. For clients, it means simply having the right product delivered at the right time.
About the author: Praveen Vashistha, Founder, Gxpress Solutions,

UltraTech’s Kukurdih unit runs fully on green energy
Cement Prices Rise Rs. 7 per Bag in September; October Hikes Expected
Andhra Pradesh Clears Rs. 30 bn My Home Cement Plant
Nuvoco Vistas, CleanMax Partner for Wind-Solar Hybrid Project in Rajasthan
UltraTech Unit Runs Entirely on Green Energy
UltraTech’s Kukurdih unit runs fully on green energy
Cement Prices Rise Rs. 7 per Bag in September; October Hikes Expected
Andhra Pradesh Clears Rs. 30 bn My Home Cement Plant
Nuvoco Vistas, CleanMax Partner for Wind-Solar Hybrid Project in Rajasthan
UltraTech Unit Runs Entirely on Green Energy
Trending News
-
Concrete4 weeks agoKirby India Breaks Ground on Fourth PEB Plant in Tamil Nadu
-

Concrete4 weeks agoAditya Birla Group Launches Ultravolt Wires And Cables Business
-

Concrete4 weeks agoCentral Technical Team To Survey Sites For Bhadradri Kothagudem Airport
-
Concrete4 weeks agoCement Demand Strong As Prices Remain Stable