Connect with us

Concrete

Ready for the juggler’s act?

Published

on

Shares

Trade pundits had predicted a slow season for cement in the second quarter of 2022, primarily due to a decrease in construction activities. While cement companies were forewarned, what they did not expect was a severe cost inflation to make a grand entrance. This has negatively affected the profit margins for the September quarter. Increased input costs and straggling prices caused the tectonic plates of market dynamics to clash, resulting in a disheartening quarterly performance.
But the industry is not one to let setbacks derail its momentum. Most cement companies reported multi-year low margins, in terms of earnings before interest, taxes, depreciation, and amortisation (EBITDA) per tonne. However, once the monsoon season was behind us, and construction restarted in earnest, they were quick to recover. The following quarter is witnessing a rise in cement prices across the country, excepting parts of central India. Although the market response has not been as enthusiastic as it was in the previous year’s festive period, certain corrections are definitely being made. One of the important factors of these economic corrections is softening of input prices such as coal and pet coke. This combined with increase in cement prices can translate into a positive outlook for the cement sector in the current quarter. However, there is the big bull’ called ‘demand’ still to contend with! Softening of input costs and rising cement prices aren’t enough to bring the margins out of the red. The third ball that cement companies have to juggle with is the demand for cement.
To understand the demand quotient, we need to look at the socio-political scenario of our country. With the next general elections looming in 2024, the central government is likely to expedite several turnkey projects like the ones under the Pradhan Mantri Awas Yojana (PMAY)-Gramin. With the government likely to allocate an additional Rs.28,000 crore for the flagship rural housing programme, the social-political ball in this juggling act is likely to be the top most. Moreover, as the Russia-Ukraine war continues, there is the energy price volatility to contend with. And with that we have another ball to juggle!
Cement stocks’ performance largely depends on the growth of the economy as they are cyclical in nature. Cement companies are investing heavily in capex, thereby boosting the investor’s confidence.
With our expert eyes focussed on the economic trends of the cement industry, we are optimistically watching cement companies perform a juggling act by keeping the balls of input costs, demand, prices and socio-political influences, firmly in the air.

Concrete

Centre Defers Clearance for Limestone Mine Near Bustard Habitat

Panel seeks revised mining plan and safeguards for pipelines and wildlife
Published

on

By

Shares


The Centre has deferred environmental clearance for a proposed limestone mine near a Great Indian Bustard habitat in Ramgarh, Rajasthan’s Jaisalmer district. The critically endangered species has an estimated wild population of about 130 in India.

Continue Reading

Concrete

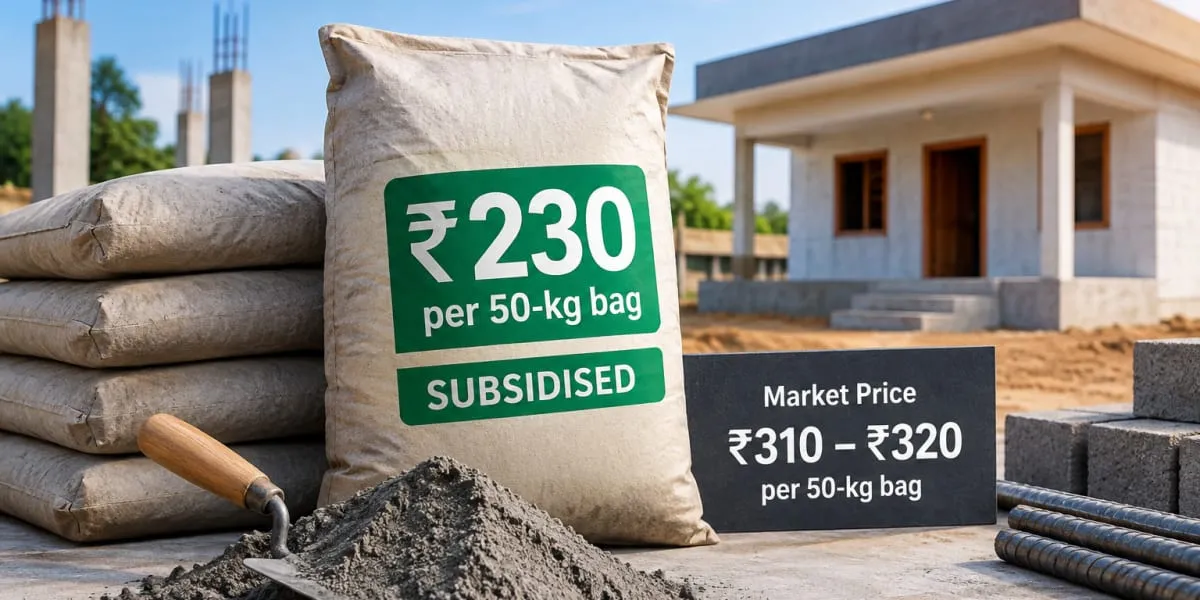
Telangana to Supply Subsidised Cement for Indiramma Houses

Poor families allotted Indiramma houses to receive cement at Rs. 230 per bag
Published

on

By

Shares


The Telangana government will supply cement at a subsidised price of Rs. 230 per 50-kg bag to poor and low-income families allotted Indiramma houses. The prevailing market price is between Rs. 310 and Rs. 320 per bag, the Assembly was informed on Thursday.

Continue Reading

Concrete

Cement Demand Strong As Prices Remain Stable

Volumes rise amid steady trade pricing and higher fuel costs

Published

on

By

Shares


Channel checks show cement demand remained healthy with volume growth estimated at six to seven per cent in July and August 2026. Trade prices were broadly stable while non-trade prices were volatile in the East, and attempted hikes were rolled back amid higher competition. Average fuel costs rose in August by five to nine per cent, lifting spot petcoke and coal prices.

All-India trade price remained flat month on month in August as increased rake supplies and competition offset early increases. Monsoon related demand softness limited sustained hikes and dealers indicated further attempts would depend on demand trends. Combined July and August volumes were estimated at six to seven per cent, supported by infrastructure spending while retail housing remained weather sensitive.

In the South, a Rs20 a bag hike in August did not hold and prices stayed flat month on month, while dealers planned Rs25 to Rs30 a bag from fifth September 2026 but with uncertain sustainability. In the East, trade prices were unchanged and non-trade prices corrected by Rs15 to Rs20 a bag amid weak construction in West Bengal, Jharkhand and Odisha.

The West remained most resilient on pricing and demand despite attempted hikes of Rs10 to Rs15 a bag, and Gujarat saw relatively better volumes in August. North and Central markets kept prices range bound as players focused on ramping up utilisation of new capacity, with schemes of up to Rs2 to Rs3 a bag used to meet month-end targets. Overall construction activity improved as the monsoon eased, aiding a pickup in several states.

Fuel cost pressures persisted, with South African coal at USD114 a t and petcoke around USD146 to USD147 a t in August, while spot imported petcoke and coal were higher. Imported coal consumption cost stood at Rs2.07 per Kcal and petcoke at USD2.11 per Kcal. Analysts estimate the all-India trade spread to decline by Rs90 to Rs100 a t quarter on quarter, weighing on near-term profitability and they prefer UltraTech Cement (UTCEM), JK Cement (JKCE) and Grasim Industries (GRASIM).

Continue Reading

Video Thumbnail

    SIGN-UP FOR OUR GENERAL NEWSLETTER

    Trending News

    SUBSCRIBE TO THE NEWSLETTER


    Don't miss out on valuable insights and opportunities to connect with like minded professionals.


      This will close in 0 seconds