Connect with us

Economy & Market

Consolidation in cement industry: Gobbling Up!

Published

on

Shares

The cement industry has been going through consolidation phase with large Indian cement players preying on smaller ones and foreign cement majors acquiring controlling stake in Indian majors. Prakash Patil looks at the M&A scenario and what it holds for the future of cement industry in India.It’s mergers and acquisitions season in the Indian cement industry and the latest big ticket deal is the acquisition of 51 per cent controlling stake by Irish cement major CRH in the two 2.4 MTPA plants of the Jaypee Group in Gujarat. A buoyant trend in prices could reportedly fetch the Jaypee Group at least $160 per tonne as replacement value, as it puts on the block its hived-off plants in western (2 units of 2.4 MT each) and southern India (1 unit of 5 MTPA). The deal for the two 2.4 MTPA plants is reportedly valued at Rs 4,200 crore. However, as Jaypee Group has its third plant with a capacity of 5 MTPA in Andhra Pradesh and the three plants would be valued at about Rs 9,000 crore. For CRH, this will be the second acquisition in India. The company had forayed into India in 2008 with the acquisition of 50 per cent stake in Hyderabad-based cement producer My Home Industries, which had an installed capacity of 4.2 MTPA.The latest CRH-Jaypee Group deal is an indication of the churning the Indian cement industry is going through over the last decade or so. The big fishes are on the prowl to gobble up smaller fries in the business and considering that there are 139 large cement plants and 365 mini cement plants in the country currently with 40 major and mid-size players having pan-India presence, the opportunities for acquisitions for the large cement players are enticing. And, it’s not just the small fries that are on the radar of the big players, even some of the biggest cement companies have been taken over in the past and many more are being wooed. After all, the cement business of Jaypee Group being acquired by CRH makes Jaypee Group the third largest cement player in India after UltraTech and Ambuja Cements.The big ticket dealsApart from the latest big ticket deal between the CRH-Jaypee Group, there have been quite a few large takeovers since 1999. When Gujarat Ambuja Cements (GACL) picked up 7.2 per cent stake in India’s then largest cement manufacturer ACC at a price of Rs 370 per share when the market price hovered around Rs 240 per share from the Tatas in December 1999, it created sensation. Later in 2000, GACL acquired the balance 7.2 per cent from the Tatas to become the largest shareholder in ACC. But the twist to this tale came when Swiss cement major Holcim picked up 14.8 per cent stake in Gujarat Ambuja Cements (later to merge with Ambuja Cements Eastern to become Ambuja Cements) for Rs 2,100 crore through the creeping acquisition route and later picked up another 20 per cent stake for Rs 2,400 crore. Subsequently, Holcim hiked its stake in Ambuja Cements to over 50 per cent, thereby acquiring complete management control over Ambuja Cements. The Holcim transaction and valuation provides an excellent indication of the extent to which investors and strategic players are ready to buy the India growth story. In 2005, Holcim acquired stake in ACC at an enterprise value (EV) of $111 per tonne and the next year Holcim acquired stake in Ambuja Cement at an EV of $193 per tonne. In 2007, Holcim again increased its stake in Ambuja Cements at an EV of $301 per tonne!With this acquisition, Holcim also acquired management control over ACC as Ambuja Cements had hiked its stake in ACC to more than 50 per cent. So, Holcim upped the ante for other global cement companies by acquiring majority stake and management control over two of India’s largest cement companies.Lafarge, the French cement major, got late into action in the M&A space and decided to take the acquisition route to fast track it cement business in India. The company declared in 2010 that it was open to consolidation in India and, according to Bruno Lafont, Chairman & CEO, Lafarge, the timeframe for acquisitions was the next five years. "We see consolidation happening (in the cement industry) in India in the mid term period. We are confident of our ability to deliver our investments in India and are open to seizing new opportunities, be it consolidation or greenfield projects," said Lafont while inaugurating the clinker line at Lafarge India’s cement plant in January 2010 at Sonadih in Chhattisgarh. The company entered the Indian market in 1999 with the acquisition of Tata Steel’s cement plant. This was followed by the purchase of the Raymond Cement facility in 2001 and the acquisition of L&T’s concrete business in 2008.The takeover of L&T’s cement business by Grasim Industries in June 2003 also created buzz in the market since this takeover catapulted Grasim Industries (later its cement division being merged into UltraTech Cement) from the third position to the numero uno position in India. After the takeover, UltraTech’s installed capacity went up from 13 MTPA to 31 MTPA. Grasim Industries had to shell out Rs 2,200 crore over a period of three years for a majority stake in Ultratech Cement. Today, UltraTech maintains its leadership position with an installed capacity of 52 MTPA, with Holcim at the no. 2 position with combined capacity of 45 MTPA through ACC and Ambuja Cement.These are just a few samples of big ticket deals that have happened in the cement sector in India since late nineties. There have been many more big and small takeovers and mergers by domestic players since mid-1990s and by foreign players since late-1990s (see box). According to the data published by the Department of Industrial Policy and Promotion, the cement sector attracted foreign direct investments (FDI) worth US$ 2.62 bn between April 2000 to May 2012, which is an ample indication of the fact that the cement sector has been attracting foreign investors in droves.The key M&A triggersClearly, the cement biggies have gone on a shopping spree since during the last decade or so. And not without reason. There are compelling reasons why domestic and foreign cement majors appear to be so bullish on India. "Major reasons for consolidation were excess capacity and entry of foreign players who wanted a pie of untapped Indian market…Apart from above two reasons, another factor that is leading to consolidation is the rising cost of greenfield capacity which also tends to have longer gestation period. Existing players are eyeing companies who are unable to meet rising cost of raw materials due to increasing imported coal prices. On the other hand, the top players who want to spread their reach are tapping such companies as it saves on time factor of greenfield capacities," says Alok Sanghi, Director, Sanghi Industries.
Commenting on the reasons for consolidation, Jailesh Dalal, Director, JAYCEE Buildcon (India), says "The Indian cement industry is fragmented and large domestic and international players would try to consolidate their position going forward for geographical diversification, concentrated focus on operational efficiency, challenges in acquiring land/limestone resources, exit of smaller players and divesture of cement businesses by diversified groups."Now, let’s look at each of these reasons why Indian cement industry is passing through the consolidation phase.Overcapacity

During 2007-12, cement producers added capacity to the tune of 150 MTPA, thereby almost doubling the total installed capacity to 303 MTPA in FY2012-13. According to a report by research firm RNCOS, "It is anticipated that the cement industry players will continue to increase their annual cement output in coming years and the country’s cement production will grow at a compound annual growth rate (CAGR) of around 12 per cent during 2011-12 to 2013-14." According to projections, by 2017 the total capacity nationally would add up to 470 MTPA.The increase in capacities by many of the Indian companies was in anticipation of demand from the infrastructure sector which failed to materialise. In a situation where demand fails to keep pace with supply, the capacity utilization rate is bound to decelerate. The capacity utilisation rate for the cement industry in India has dropped from 93 per cent in FY2006-07 to 75 per cent in FY2011-12. The fall-out of such overcapacity situation is that the cement prices are likely to come under downward pressure which would make survival difficult for smaller cement companies with capacities less than 1 MTPA and therefore vulnerable for takeover. However, the fact that cement majors have built up capacities in advance is an indication that these companies expect demand for cement to remain firm due to construction activity, which is expected to gather momentum due to government’s policy to boost investments in infrastructure.Infrastructure PotentialIndia’s high housing and infrastructure deficits points to the huge potential for development of housing and infrastructure. The cement sector will benefit hugely as and when the momentum in housing and infra development picks up. This potential for development has been attracting major players in hordes from across the world. The demand for cement, being a derived demand, primarily depends on the industrial construction, real estate business, construction activities and investments in the infrastructure sector.Currently, the housing sector consumes 55-60 per cent of cement produced in India and this is expected to change in the next few years when the emphasis will shift on infrastructure development such as roads, bridges, airports, and railways, which will consume a significant percentage of cement produced in the country. The consumption of cement in agriculture is negligible today; but with a greater thrust on agriculture and the suggested ‘second green revolution’, this sector too will extensively use cement to build warehouses and other logistics.But instead of opting to set up cement plants themselves, it makes sense for the foreign players to take the acquisition route not just to make foray into India but also ramp up capacity quickly. The high potential for growth in demand for cement is amply evident from the fact that the per capita cement consumption in India was 230 kg in 2010, which is almost half of the global average of around 450 kg and way below the Chinese average per capita consumption of 1220 kg. Hence, domestic and foreign cement companies remain bullish on the prospects of cement industry in India.High capital cost & long gestation periodA cement plant is typically a capital intensive business and to establish a greenfield project takes about three years. The cost of setting up a greenfield capacity has reportedly shot up from $120 per tonne to $160 per tonne in just two years. Besides, the cement business has a long gestation period and, depending on the market situation, the break-even point may extend to three-four years at an operating level of 70-75 per cent. The high capital cost and long gestation period makes establishing a new cement plant an unattractive business proposition. Hence, established and large players may prefer to poach on the existing and established players to beat the competition and increase their market share. "The cement sector is slowly heading for a major consolidation as greenfield projects are becoming difficult to set up due to increased hassles in areas like mineral concession, land acquisition and related environmental and operational issues. This may lead the cement industry in India to be consolidated in the hands of a few major giant cement companies and only a few cement companies with single or smaller capacity plants shall continue to operate purely due to regional and local factors," says P K Ghosh, Chairman, Ercom Engineers.Entry barriers & cumbersome proceduresDifficulty in accessing limestone reserves, which is a key input in cement production, acts as a significant entry barrier for new entrants. To overcome this difficulty, takeover of companies with access to limestone reserves is the easiest route to crossing the entry barrier. No wonder, none of the foreign cement majors tried to set up a greenfield cement plant as prospecting for limestone reserves is a time-consuming process. Even if the limestone reserves are established, getting the mining rights, railway siding, etc. can reportedly take upto 7-8 years, with only 25 per cent chance of striking enough limestone reserves to last for the entire economic life-span of the plant. Hence, acquisition is bound to pick up further momentum as more cement majors enter the Indian market.The benefits of consolidationThe consolidation in the cement industry would prove to be beneficial both for the acquiring companies as well as for the cement industry. Some of the benefits that would ensue from consolidation are as follows:
Economies of scale
A large cement company enjoys the benefits of economies of scale. Mergers and acquisitions bring about consolidation of capacities which adds up the benefits of scale. The economies of scale enable the company to reduce the production costs so that it can reduce the cement price to maintain an edge over the competitors.Extended reach and increased revenuesWhen a company takes over the production and distribution facilities of another company, it immediately extends its geographical reach and increases its market share on account of expansion of the market for its product. The market expansion helps in ramping up the revenues of the company within a short span of time. The enhanced geographical reach may also result in substantial reduction in transportation costs which are quite high as cement is a bulk commodity.Technological upgradationThe new energy-efficient but capital-intensive "dry" production technology offers to the companies efficiencies that provide vital edge over the companies not deploying such technologies. Small manufacturers may not possess the requisite financial resources or production volumes to be able to afford the most efficient technology, which puts them at a competitive cost disadvantage. The entry of foreign players has led to technological upgradation and innovation in Indian cement industry. "Despite the fact that the technology used by Indian cement companies is among the best in the world, more innovation is required to ensure that cement plans are not only environment-friendly, but also low-cost in nature. M&As in last decade has helped Indian firms propel to global standards. Foreign firms who took over Indian firms have made most of the investments in India in the last decade for upgrading technology and raising capacity. With higher spend on technology, existing players are likely to focus more on ready mix concrete, bulk sales and blended cement to ensure improvement in quality as well as environment consciousness with sustainable construction," says Sanghi.The Road AheadGoing forward, the acquisitions space is going to get hotter, with lot of small and mid-sized cement companies up for grabs. Once the economies of scale kick in on account of consolidation, the cement prices are likely to remain competitive yet remunerative. This would benefit both the cement companies as well as cement consumers. Summarising the benefits of consolidation, Dalal says, "M&As would largely have a positive impact in the cement industry in India on account of value creation, economies of scale and cost efficiencies, operational and supply chain efficiencies, higher competitiveness, technology transfer, better research and development and high quality products, financial leveraging and optimization of profitability and increased focus on health, safety and environment. In the future as well, M&As would augur well for the industry as it would bring world-class technology, products and operational efficiencies into India." Sanghi too feels that M&As would be beneficial and says, "M&As in cement industry is likely to bring pricing power, improve profitability and reduce cost of branding for top players. Through M&As, top players would have higher vertical integration and locational advantage with respect to sourcing raw materials and market reach."Of course, there is always the possibility of major companies forming a cartel to keep the cement prices artificially high, but with the Competition Commission of India keeping a vigil over the production figures, capacity utilization and cement prices, the cement companies would be wary of indulging in such malpractices. Sanghi too dismisses fear of cartelization saying, "If there was (cartelisation) as is claimed, cement companies would not have reported losses in any quarter. Also, prices would have been same across the year, if there was cartelization. But every year, cement prices fall during monsoon because there is a slowdown in demand; while prices rise on and around Diwali due to surge in demand from real estate."To sum up, consolidation is good for the cement industry and there are sunny days ahead for the industry in times to come.

Continue Reading
Click to comment

Leave a Reply

Your email address will not be published. Required fields are marked *

Concrete

Nuvoco Vistas, CleanMax Partner for Wind-Solar Hybrid Project in Rajasthan

Published

on

By

Shares

The project – comprising 20 MW of wind and 26.4 MWdc of solar capacity – will support Nuvoco’s cement operations with cleaner power while strengthening its renewable energy and decarbonisation strategy.

Mumbai, September 29, 2026

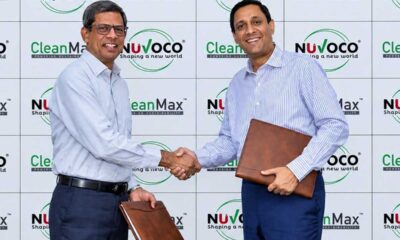
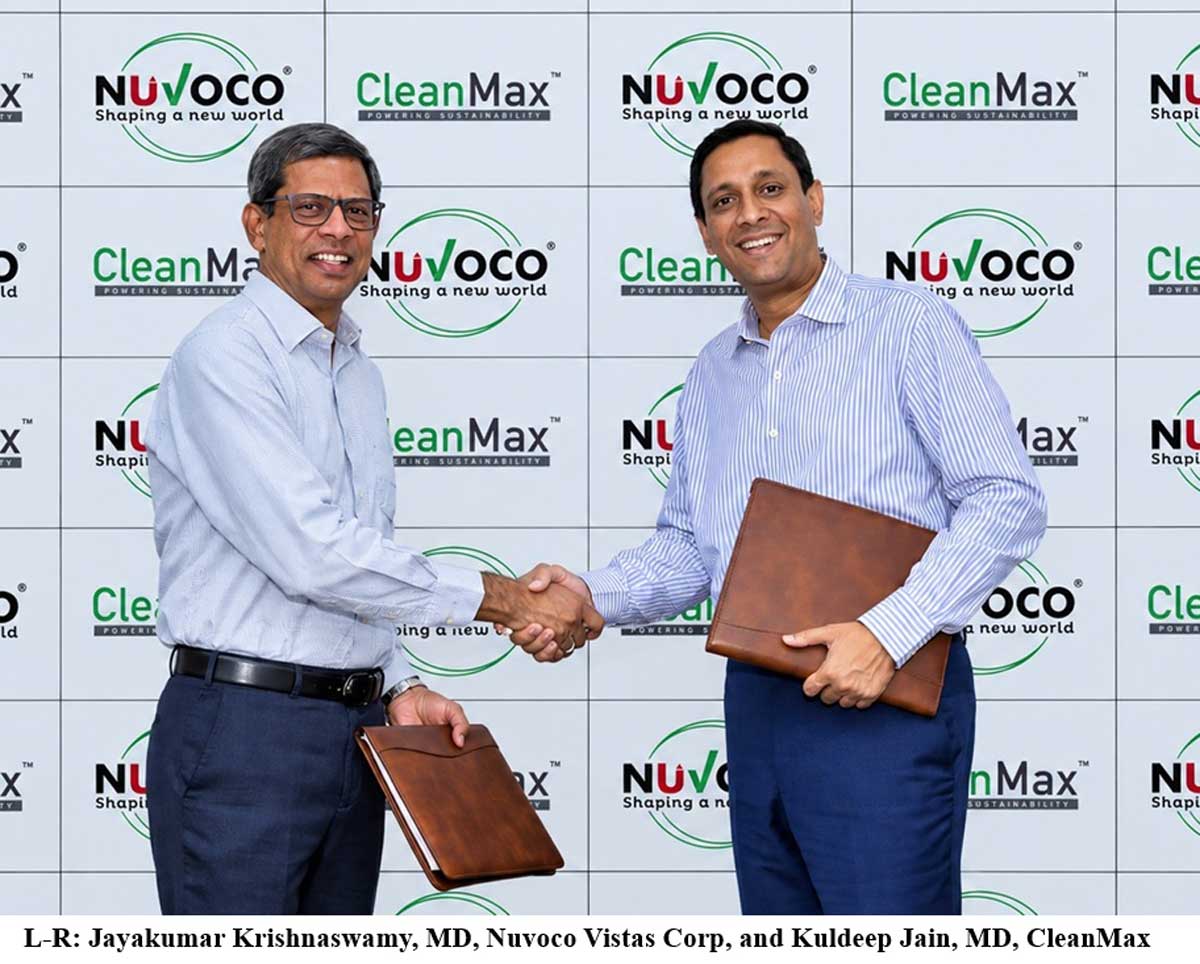
Nuvoco Vistas Corp Ltd, part of Nirma Group and one of India’s leading cement companies, has partnered with Clean Max Enviro Energy Solutions Limited (CleanMax), a renewable energy solutions provider for the commercial and industrial (C&I) sector, to develop a 46.4 MW wind-solar hybrid renewable energy project in Rajasthan.

The project will support Nuvoco’s cement operations with cleaner power while strengthening its renewable energy and decarbonisation strategy. It is expected to increase the share of renewable energy in Nuvoco’s power mix, reducing fossil fuel consumption and associated emissions.

Developed by CleanMax, an Independent Power Producer (IPP), at Bhikamkhore, Rajasthan, the project will comprise 20 MW of wind capacity and 26.4 MWdc of solar capacity, along with a 2-MWh Battery Energy Storage System (BESS). Power generated from the facility will be supplied to Nuvoco through the State Transmission Utility (STU) Open Access network.

The hybrid project is expected to generate approximately 100 million units (MU) of renewable electricity annually and help avoid around 1,25,485 tonnes of CO₂ emissions every year across Scope 1 and Scope 2 emissions.

The initiative supports Nuvoco’s ongoing efforts to reduce the carbon intensity of its manufacturing operations through renewable energy adoption, Waste Heat Recovery Systems (WHRS), energy-efficiency measures and increased use of alternative fuels. It also aligns with the company’s DIRE (Digitalisation, Innovation and Renewables) agenda, which focuses on climate action, renewable energy transition, water stewardship, circularity and biodiversity conservation across its manufacturing ecosystem.

Commenting on the initiative, Jayakumar Krishnaswamy, Managing Director, Nuvoco Vistas Corp Ltd, said, “This marks an important step in advancing Nuvoco’s journey towards more sustainable and resilient operations. Our collaboration with CleanMax will increase the share of renewable energy across our Rajasthan operations, strengthening our energy mix while improving long-term cost efficiency and reducing our dependence on conventional power sources. Initiatives such as these reinforce our commitment to operational excellence and responsible growth, while supporting our vision of Building a Safer, Smarter and Sustainable World.”

Kuldeep Jain, Founder and Managing Director, CleanMax, said, “Cement plants run continuously, so the power behind them has to be dependable for decades, not years. We’re seeing manufacturing industries view clean energy as an integral part of their core operations and long-term strategy. Our partnership with Nuvoco reflects that shift, and we’re pleased to support its decarbonisation journey. This wind-solar hybrid project is designed to deliver long-term cost certainty while supporting the Company’s transition to cleaner power.”

Nuvoco has been advancing its sustainability initiatives through renewable energy, operational efficiency and technology-driven solutions. The company operates across Cement, Ready-Mix Concrete (RMX) and Modern Building Materials (MBM) segments, with a presence across East, North and West India.

The company began operations in 2014 with a greenfield cement plant in Nimbol, Rajasthan, and later acquired Lafarge India Limited, which entered India in 1999, along with Emami Cement Ltd in 2020 and Vadraj Cement Limited in April 2025. With planned expansion initiatives, including a new grinding mill at the Arasmeta Cement Plant and multiple debottlenecking projects, Nuvoco aims to achieve a cement capacity of 35 MMTPA.

The company reported total income of Rs 113.62 billion in FY 2025-26, reflecting its continued growth trajectory. Its cement portfolio includes Concreto, Duraguard, Double Bull, PSC, Nirmax and Infracem brands, while its RMX business offers products under Concreto, Artiste, InstaMix, X-Con and Ecodure brands. Nuvoco also provides construction solutions under its Zero M range of modern building materials.

Continue Reading

Concrete

UltraTech Cement achieves 100% green energy milestone at Chhattisgarh plant

Published

on

By

Shares

UltraTech Cement’s Kukurdih Works becomes its first integrated unit to meet 100 per cent electricity needs through green energy every month.

Raipur (Chhattisgarh)

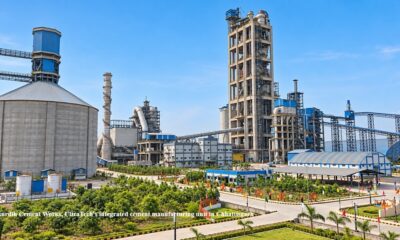
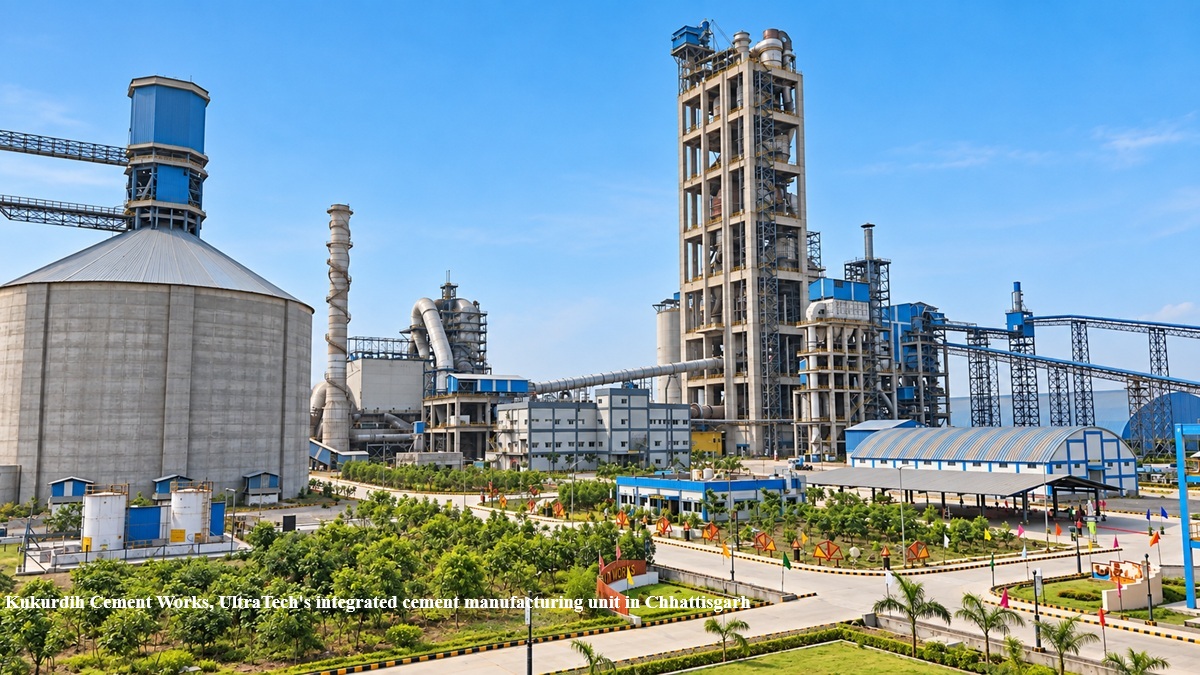
UltraTech Cement Limited, the world’s largest cement company outside China, has achieved a significant decarbonisation milestone, with its Kukurdih Cement Works integrated unit in Chhattisgarh meeting 100 per cent of its electricity requirement through green energy every month since April 2026.

Commissioned in 2024, Kukurdih Cement Works has an installed grey cement capacity of 3.3 million tonnes per annum. The unit achieved this milestone through a combination of renewable power sourcing and Waste Heat Recovery Systems (WHRS), which now collectively meet its entire electricity demand while ensuring operational reliability.

Since April 2026, nearly one-third of UltraTech’s 76 manufacturing units in India have maintained green energy utilisation above 50 per cent of their electricity requirements. Five units, including Kukurdih, have exceeded 95 per cent green energy utilisation. The company is also progressively deploying Battery Energy Storage Systems (BESS) across its network to enable deeper renewable energy integration.

As part of its decarbonisation strategy, UltraTech has not invested in additional captive thermal power capacity for greenfield projects or brownfield expansions at its integrated units for over a decade.

As of Q1FY27, the company’s captive green energy capacity stood at 1,897 MW, comprising 1,463 MW of renewable energy capacity from solar, wind and hybrid sources, along with 434 MW of WHRS capacity. Under its RE100 commitment, UltraTech aims to increase the share of green power in its total energy mix to 85 per cent by 2030 and achieve 100 per cent by 2050.

UltraTech Cement Ltd, the cement flagship company of the Aditya Birla Group, is a $10-billion building solutions company and the largest cement producer globally by sales volume outside China. The company has a total grey cement capacity of 210.1 MTPA and white cement/putty capacity of 3.5 MTPA. It is a signatory to the GCCA Climate Ambition 2050 and has committed to the Net Zero Concrete roadmap announced by GCCA.

Continue Reading

Economy & Market

From First Mile to Last Mile

Published

on

By

Shares

Praveen Vashistha, Founder, Gxpress Solutions, speaks about building a holistic logistics network that encompasses latest technology and current challenges faced by logistics service providers.

Logistics may seem to only entail transporting a package from one location to another. However, there is more to this term than just that. Logistics refers to the entire process of controlling all movement, transfers and decisions in the correct way at the right time and cost and with the desired level of visibility.

People nowadays want to receive more than just the delivery. They want quick, efficient, reliable and transparent logistics service. On the other hand, companies are facing higher operating costs, broken supply chains, congested cities, changing habits of consumers and growing complexity of logistics services. In this situation, a full logistics package is gaining importance not only as a competitive advantage but also as a necessity for a successful business.

The main challenge lies in uniting the first mile, the middle mile and the last mile into one seamless process.

The journey begins before the package moves

First-mile logistics may be the least recognised part of the logistics chain, but they have a crucial influence on all that follows.

This stage starts from the moment the shipment leaves the manufacturer, supplier, farm, warehouse or distribution centre. Depending on the industry, first-mile logistics may involve grouping shipments from multiple suppliers, compiling paperwork and checking the inventory before sending the shipments to a central hub.

Flaws in first-mile logistics produce effects later down the supply chain. Delays in cargo pickup can affect warehouse operations; improper packaging can damage goods in transit; and incorrect inventory information may cause stockholding or unnecessary replenishments.

This is why building a reliable network involves simplifying the operations done at the beginning of the supply chain.
Companies require accurate demand forecasts, supplier visibility, standard procedures, and software to capture information from the moment a shipment enters the supply chain. Route planning and fleet management are also important at this stage, especially as it may involve contacting multiple suppliers.

The main goal is simply to make the first mile predictable.

The middle mile: Where scale meets complexity

When products leave the original site, they travel through the ‘middle mile,’ which connects fulfilment centres, warehouses, sorting centres, and regional distribution points. In this phase, logistics networks begin operating on a large scale. A shipment can pass through several facilities before reaching the final destination. Each additional transfer entails the risk of delay or damage and information losses. Accordingly, the ideal solution is not to minimise the number of transfers but rather to optimise them. The use of hub-and-spoke networks, regional distribution centres, and strategically placed distribution centres can help companies shorten transportation routes and optimise distribution costs. Besides, data can be used to determine the optimal placement of inventories.

For instance, a retailer may find that it takes more time and is more expensive to deliver goods to customers if everything is stored in a central warehouse. Meanwhile, regional distribution helps meet the customer’s needs quicker and more efficiently.

The last mile is where the customer judges you

When it comes to the logistics experience, the customer experience comes down to the delivery. While the last mile might comprise a small part of the entire journey in actual distance, it could also entail expensive and difficult processes. Delivery runs through densely populated cities, through traffic jams, through unsuccessful delivery attempts, and through changing consumer preferences and narrowed time frames.

Customers want to have control over their delivery. Delivery means that customers expect to know the exact moment when their order is delivered. They need to receive current updates about their orders and the ability to decide whether they want scheduled deliveries, or whether they want their order to be dropped off at a designated location far from their house.

As a result, last-mile logistics must incorporate both efficiency and experience. The technology may be used to ensure timely and accurate delivery, through such products as route optimisation and real-time delivery tracking.

However, technology is not enough to guarantee success in terms of last-mile delivery. Knowledge of the local area is still an important aspect that contributes to successful delivery.

One network, not three separate operations

First, the common mistake that organisations can make is treating the first mile, the middle, and the last mile separately.

An effective first mile of logistics does not matter much if the shipment waits in a hub for many hours. A perfectly working warehouse does not make a happy customer if the last-mile delivery fails. Therefore, even the fastest last-mile delivery can become an expensive operation if the supply is not well geographically positioned.

The three moments should work together as one whole system.

This implies having a common view on inventory, transport capacities, shipment statuses and demand. The Transportation Management System, Warehouse Management System and order management system should give information to each other instead of acting like separate islands.

That is where real-time information comes into play!

If something happens, such as a vehicle gets delayed, the company has to know that from the start. If not, someone from Customer Service should be informed about the situation.

Visibility is the new infrastructure

Previously, companies had to rely on physical assets, such as warehouses, trucks, and sorting facilities, to create their logistics networks. Today, they have an additional layer of technology providing visibility.

Command-and-control systems now include GPS tracking, Internet of Things devices, bar-coding, RFID, cloud computing, artificial intelligence, and analytics, which allow companies to know what the goods are doing, how well they are doing, and what is going to happen next.

Predictive analytics reveal possible delays. AI-powered forecasting increases availability. Digital dashboards enable the manager to monitor all operations in one place. The efficiency of such technologies is not measured in the amount of information they gather, but rather in their capability of converting data into knowledge.

Logistics managers should be able to answer the following questions: Where is it? When is it supposed to arrive? What causes the delay? What impact does it have? Can it be delivered some other way? How much will it cost?

The sooner the answers are given, the more resilient the logistics system is.

Resilience must be designed into the network

The events of recent years have highlighted the vulnerability of interconnected supply chains. Geopolitical tensions, bad weather, a lack of labour, poorly developed infrastructure and an unexpected spike in demand are some events that can cause problems for logistics systems without prior notice. Thus, companies should create an end-to-end network not just for normal times but also capable of functioning quickly in problematic situations. In order to create such a network, it is necessary to find alternative suppliers, use several means of transportation, create several routes of delivery, and establish inventory. It is also important to use scenario planning to define what to do if the main hub becomes unavailable or any means of transportation is blocked.

Sustainability: Part of the delivery equation

The future of logistics will also be shaped by environmental considerations.

As delivery volumes rise, businesses are under increasing pressure to reduce emissions without compromising service. Better route planning, load optimisation, electric vehicles, alternative fuels, renewable-energy-powered warehouses and consolidated deliveries can all contribute. The most sustainable shipment is often the one that does not require unnecessary movement in the first place.

Better demand forecasting and inventory placement can reduce empty miles and avoid repeated transportation. Consolidating deliveries can improve vehicle utilisation. Reverse logistics can ensure that products, packaging and materials return efficiently instead of becoming waste.

Sustainability, therefore, should not be treated as a separate initiative. It should be incorporated into network design itself.

The future belongs to connected logistics

An end-to-end logistics network ultimately seeks to close existing gaps between various processes.

Every mile of the process should be interconnected with the other miles. Warehouses should be aware of the restraints imposed by transportation. Delivery crews should be able to know at every moment the inventory at their disposal. Clients must have access to this useful information.

Companies that will be successful in this area will not necessarily be the ones with the biggest fleets or the most warehouses. They will simply be the ones that can employ their resources in the most effective manner.

The future of logistics will be represented by an ecosystem consisting of the combination of the physical aspect, digital intelligence, and personnel decisions. Every mile in the process of delivery is important. However, the key advantage here is getting those miles to work together.

For companies, it means having minimal resistance, enhancing their efficiency and improving customer care. For clients, it means simply having the right product delivered at the right time.

About the author: Praveen Vashistha, Founder, Gxpress Solutions,

Continue Reading

Video Thumbnail
▶

    SIGN-UP FOR OUR GENERAL NEWSLETTER

    Trending News

    SUBSCRIBE TO THE NEWSLETTER


    Don't miss out on valuable insights and opportunities to connect with like minded professionals.


      This will close in 0 seconds