Economy & Market
Challenging Days Ahead
Published
15 years agoon
By
admin
Bad news never comes singly. India’s economic growth has slumped to its lowest in more than two years while output expansion at key industries tumbled to a six-year low and even the finance minister, Pranab Mukherjee, has warned that there are tough times ahead. There has been a sharp deceleration in industrial growth with output growth in eight core industries, including steel, cement and coal, dropping to near-zero in October, a sharp decline from 7.2 per cent one year back. Under the circumstances, the cement sector needs to remain vigilant and while bracing itself for weaker growth, seek out newer strategies to ensure that targeted capacity and production stays on line while staying in line with environmental demands and limitations in raw material availability.It is worrying indeed that fiscal deficit for the first seven months of the year has already reached 75 per cent of the year’s estimate. Experts concur with the finance minister that a combination of domestic and international issues are going to impact the country’s growth. GDP data released by the government on in the last week of November 2011 has revealed broad-based weakness in the economy, with mining contracting 2.9 per cent and manufacturing rising by 2.7 per cent in the last quarter. Despite the gloomy outlook, the finance ministry is hopeful that the economy will recover some of its lost momentum and is expecting 7.3 per cent GDP as against last year’s 8.5 per cent.According to Research & Markets report on the Indian cement sector, economic recovery, which had gained momentum in the first half of FY11, started showing signs of moderation in the second half. The biggest hindrance to growth momentum, however, has been high inflation. Inflation refuses to abate and has forced RBI to pursue monetary tightening measures even at the cost of growth. Rising energy prices and interest rates will continue to pose a challenge for businesses in the near future. Despite these short term challenges, the overall economic sentiment remains healthy and a good growth rate for the next year is expected.FY11 was quite challenging for the cement industry. On the one hand, demand growth weakened due to lower realty and infrastructure spending, while on the other, extended monsoons and logistical constraints dampened construction activity.On the supply front, overcapacity continued to plague the industry. During the year, the industry witnessed capacity addition of around 28 million TPA in addition to the 60 million TPA added in the previous year. Industry capacity utilization was at 75 per cent against 84 per cent recorded in the previous year. Surplus cement scenario together with sluggish demand and volatile prices adversely impacted domestic realizations which were lower by 4 per cent as compared to the previous year. On the cost front, the higher price of both domestic and imported coal resulted in a 25 per cent increase in energy costs, which rose substantially from 671 per ton to 838 per ton. During the year, imported coal prices rose by 36 per cent from CIF $ 89 per ton to $ 121 per ton. In addition to the normal price hike in domestic coal, there was a further increase in domestic coal prices in the range of 30 per cent -150 per cent from 1st March, 2011, according to the report.While the larger economic issues play out a crucial role on the industry’s performance, it is left to the sector to analyse the various other shortcomings it faces and seek remedies for the same.PRESENT STATUS
- Capacity and Production:
The installed capacity of cement in the country has grown during the period 1991 to 2011 at an average rate of 8.3 per cent CAGR while the production has grown at the rate of 8 per cent during the same period. The table -1 gives the installed capacity and production of cement between 1991-2011.
- Thermal Energy:
The weighted average of thermal energy consumption of major 26 plants is shown in figure – 1. It would be seen that very little improvement is made over the years between 2005-2006 to 2007-2008. The world’s best ranges between 680-690 Kcal/kg clinker. Though there are some cement plants in India which are able to fall in this category but industry as a whole has challenge before it to further improve on this account.
- Electric Energy Efficiency:
The weighted average of consumption of electric energy of 26 plants is given in figure – 2. The electric consumption has virtually reached at plateau and showing very little further improvement. The best operated plants have brought down the consumption in the range of 65-68 kwh/t cement, however, industry as a whole has scope for further improvement. Environmental Performance of Cement Plants:The National Ambient Air Quality Requirement as per CPCB is given in table – 2.The modern cement plants are able to adhere to these norms. The new generation plants with capacity 8000TPD and above are even excelling the norms.
- Product Mix:
The Indian cement industry has undergone major shift in product mix especially during the last decade. The environmental and sustainability issues may demand same trend to continue in the future. The table -3 gives product mix during the different periods;CHALLENGES AHEAD
- Lime Stone:
Lime stone will continue to be the life line of cement manufacture. As per thumb rule, for every ton of clinker produced, 1.75 tonnes mineable line stone deposits of proven variety should be available. For 350 million tons installed targeted capacity by the end of XI plan (2012), nearly 600 mn.t of cement grade lime stone have to be made available annually. Keeping in view the rapid expansion of Indian Cement Industry, NCB initiated the task of preparation of national inventory of cement grade lime stone. As on 31st March, 2002, India’s total reserves have been estimated as given in table – 4.Table – 4 Lime Stone ReservesSizable reserves are located in inaccessible areas, difficult terrains reserved forests, bio-zones and coastal regulatory Zones, etc. The proven category reserves are only 22,476mn.t which are likely to last for next 35 to 40 years at the present rate of production.Apart from limited availability of measured reserve for green field projects, about 27 per cent of total reserves are of marginal grade which can only be utilized with sweetener or after up-gradation through beneficiation. Availability of cement grade limestone will be becoming a major challenge for the cement industry in the future.
- Coal :
Availability of coal is proving another bottleneck in the growth of cement industry. The coal demand of cement industry is given in table -5.During the last decade the coal demand has gone almost four times. The infrastructure deficiencies at ports are causing problems in importing coal and availability of indigenous coal to cement industry is not assured. The first preference is being given to Thermal Power Plants and then to steel industry in allocation of coal by the Govt. The cost of coal is escalating every year and posing challenge before the cement industry. The situation is likely to aggravate in future.BLENDING MATERIALS
- Fly Ash:
Large quality of fly ash is generated in India but in many cases, the location of major Thermal Power Plants is far away from cement plants and in absence of proper infrastructure for transportation and handing of fly ash, most of it cannot be utilized. The availability of fly ash is given in table – 6The cost of fly ash is continuously increasing due to transportation and permission given to thermal power plants to charge for it instead of giving free. The mega thermal plants located in East UP, West Bengal, North Bihar and generally in Eastern part of India have very few cement plants in close vicinity. The mismatch in location of Thermal Power Plants and cement plants is shown in Figure – 3The availability of good quality fly ash at reasonable cost is also going to be major factor before the cement industry in coming years.
- GGBS
Ground Granulated Blastfurnace Slag (GGBS) cement is a by-product of the steel industry. Molten slag lying on top of the molten iron in the blastfurnace comprises silicates (glass), and is the raw material for GGBS cement. The molten slag – of no use to the steel making process – is cooled and then finely ground to form GGBS cement. Currently around 200 kg of slag is generated for each ton of steel produced in India making it 11 to 12 mt slag annually. Most of the slag is produced in the eastern part of the country where it is used in production of slag cement. The availability of blast furnace slag will continue to remain limited and possibilities need to be explored to use slags other than blast furnace like zinc slag, copper slag, steel slag for manufacture of slag cement. At present these slags are not permitted by BIS for production of slag cement.HIGH INPUT COSTS AND INFRASTRUCTURAL WEAKNESS
At present, the cement industry is facing two fold problems of high input costs and infrastructural weakness. The inputs with spiraling cost increase are coal, power and transport by rail or road. The coal from public sector is of poor quality, high ash and low calorific value content and at times costlier than imported coal. There is need to introduce competition for improving quality, regularity in supply and reduced prices. The power from public utilities is of poor quality due to frequent power cuts and fluctuating voltage. Power sector reforms if taken up seriously will enable quality power to cement plants at reasonable cost.Transport by rail or road is a cost-intensive component and amounts to almost 15 per cent to 20 per cent of the delivered cost to the consumers. The railway tariff is high and need to be rationalized for an essential product like cement. Road transport on the other hand, provides limited alternative because of inadequacy of road network and rising cost of road transport due to continuously rising fuel cost. Inland water transport is a low investment, eco-friendly and cheap mode especially for bulk commodities like cement. Coastal shipping and inland waterways will help in bringing down the transportation cost. Due to increasing use of cement in bilk, more and more bulk terminals will be needed in the years to come and inland water transport and coastal shipping can be of great help in this regard.TO INCREASE USE OF CEMENTCement is not the end-use product for the consumer. Concrete and mortar are the real end-products. Use of concrete at present is very low, about 0.5t per head annually against World’s average of 1.0t. Use of concrete and cement based products need to be promoted especially in the following sectors to increase the demand of cement.
- Concrete roads
- White topping over existing bitumen roads
- Cement based bricks/blocks for walling in lieu of clay bricks
- Pre-fab components for mass housing in lieu of conventional systems for roofing, flooring, walling etc.
- Cement concrete lining to canals to reduce seepage losses.
- Development of inland water ways and linking of rivers.
The average consumption of cement per head is very low in India, in the range of 180-190 kg while world average is about 400kg and in developed countries it is 600-800kg. Cement-concrete is more durable than other conventional materials and the use of concrete in construction will bring down the life cycle of civil works and will be more eco-friendly and sustainable.ENVIRONMENTAL CONSCIOUSNESS AND CUSTOMER ORIENTATION
The main global concerns at present are conservation of energy and pollution control. In future pressure will mount on the industry to reduce energy and GHG emissions. The energy consumption of many of the cement plants in India is comparable with the "best practices". However, there is still a scope to bring down the energy consumption by improving operational efficiency and plant technology. Though many plants have won environmental excellence awards but industry as a whole can still achieve better results on this front.The future initiatives have to be directed for using hazardous or waste materials (pet coke, used tyres, municipal and agricultural waste etc.) as fuel and larger use of fly ash, ggbs and other industrial waster like Zinc-lead slag, copper slag, steel slag etc. Both these ventures would contribute to environmental improvement and legislative and statutory authorities should support these initiatives.The customers have to be educated in proper use of cement and to avoid wastages at site. The inhibition to use mineral admixtures like fly ash, ggbs and blended cements should be removed through proper training and demonstrations at construction sites. The new code on concrete mix proportioning IS 10262 has been issued by BIS in 2009, rationalizing the use of binding materials and to avoid excessive use of cementing materials in concrete. The good construction practices should be encouraged by upgrading the skills of construction professionals for increasing the life of construction and to avoid the wasteful consumption of materials in repairs and rehabilitation. The mechanization in construction is another area which would need focus in future. The promotion of RMC during the last decade has brought numerous benefits in making concrete more reliable, durable and cost effective material. Similarly the pre-cast industry, which is in very nascent stage has potential to provide speed, quality and sustainability to construction projects. Promotion of these technologies and practices would provide additional impetus to the growth of cement industry in the coming decade.TOUGH TIMES CALL FOR TOUGH MEASURESThe industry has to overcome new challenges to be vibrant and healthy in future. The major hurdles are likely to be availability of quality raw materials at reasonable cost, energy sources, compatible infrastructure for movement of raw materials and finished goods, skilled man power and commensurate financial resources for continued technological up-gradations and innovations to meet the future aspirations of the construction industry and the society at large. These challenges can be met by combined efforts of industry friendly legislative frame work, boost of infrastructure by government, adoption of technologies to increase demand for cement and the cement industry by continuously striving for technological excellence and innovations in all fields of its operation. The Indian cement industry will emerge stronger, more efficient, sustainable and vibrant in future by virtue of its dedication and an intense urge to serve the construction industry in best possible manner.A.K. Jain is Technical Advisor, Ultratech Cement Ltd
You may like
-
In spite of company’s optimism, demand weakness in cement is seen in the 4% y-o-y drop in sales volume. (Reuters)
-
Earnings of cement firms may recover from September
-
Siam Cement to lift capacity by 4.5 mta
-
igus’ roller links
-
April price hikes indicative of improved profitability | Analysts
-
Coal India’s e-auction prices for coal rise
Concrete
Nuvoco Vistas, CleanMax Partner for Wind-Solar Hybrid Project in Rajasthan
Published
5 days agoon
September 29, 2026By
admin
The project – comprising 20 MW of wind and 26.4 MWdc of solar capacity – will support Nuvoco’s cement operations with cleaner power while strengthening its renewable energy and decarbonisation strategy.
Mumbai, September 29, 2026
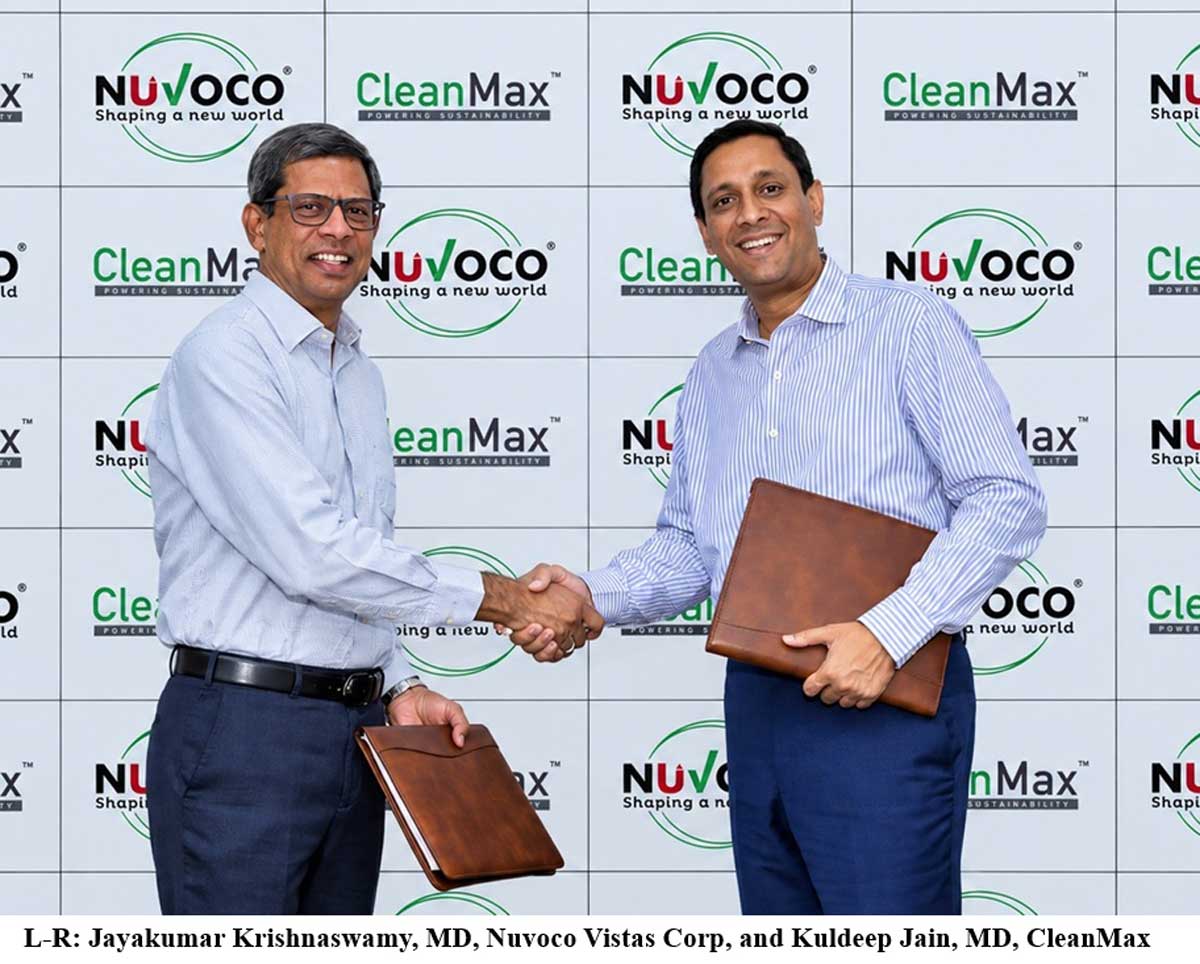
Nuvoco Vistas Corp Ltd, part of Nirma Group and one of India’s leading cement companies, has partnered with Clean Max Enviro Energy Solutions Limited (CleanMax), a renewable energy solutions provider for the commercial and industrial (C&I) sector, to develop a 46.4 MW wind-solar hybrid renewable energy project in Rajasthan.
The project will support Nuvoco’s cement operations with cleaner power while strengthening its renewable energy and decarbonisation strategy. It is expected to increase the share of renewable energy in Nuvoco’s power mix, reducing fossil fuel consumption and associated emissions.
Developed by CleanMax, an Independent Power Producer (IPP), at Bhikamkhore, Rajasthan, the project will comprise 20 MW of wind capacity and 26.4 MWdc of solar capacity, along with a 2-MWh Battery Energy Storage System (BESS). Power generated from the facility will be supplied to Nuvoco through the State Transmission Utility (STU) Open Access network.
The hybrid project is expected to generate approximately 100 million units (MU) of renewable electricity annually and help avoid around 1,25,485 tonnes of CO₂ emissions every year across Scope 1 and Scope 2 emissions.
The initiative supports Nuvoco’s ongoing efforts to reduce the carbon intensity of its manufacturing operations through renewable energy adoption, Waste Heat Recovery Systems (WHRS), energy-efficiency measures and increased use of alternative fuels. It also aligns with the company’s DIRE (Digitalisation, Innovation and Renewables) agenda, which focuses on climate action, renewable energy transition, water stewardship, circularity and biodiversity conservation across its manufacturing ecosystem.
Commenting on the initiative, Jayakumar Krishnaswamy, Managing Director, Nuvoco Vistas Corp Ltd, said, “This marks an important step in advancing Nuvoco’s journey towards more sustainable and resilient operations. Our collaboration with CleanMax will increase the share of renewable energy across our Rajasthan operations, strengthening our energy mix while improving long-term cost efficiency and reducing our dependence on conventional power sources. Initiatives such as these reinforce our commitment to operational excellence and responsible growth, while supporting our vision of Building a Safer, Smarter and Sustainable World.”
Kuldeep Jain, Founder and Managing Director, CleanMax, said, “Cement plants run continuously, so the power behind them has to be dependable for decades, not years. We’re seeing manufacturing industries view clean energy as an integral part of their core operations and long-term strategy. Our partnership with Nuvoco reflects that shift, and we’re pleased to support its decarbonisation journey. This wind-solar hybrid project is designed to deliver long-term cost certainty while supporting the Company’s transition to cleaner power.”
Nuvoco has been advancing its sustainability initiatives through renewable energy, operational efficiency and technology-driven solutions. The company operates across Cement, Ready-Mix Concrete (RMX) and Modern Building Materials (MBM) segments, with a presence across East, North and West India.
The company began operations in 2014 with a greenfield cement plant in Nimbol, Rajasthan, and later acquired Lafarge India Limited, which entered India in 1999, along with Emami Cement Ltd in 2020 and Vadraj Cement Limited in April 2025. With planned expansion initiatives, including a new grinding mill at the Arasmeta Cement Plant and multiple debottlenecking projects, Nuvoco aims to achieve a cement capacity of 35 MMTPA.
The company reported total income of Rs 113.62 billion in FY 2025-26, reflecting its continued growth trajectory. Its cement portfolio includes Concreto, Duraguard, Double Bull, PSC, Nirmax and Infracem brands, while its RMX business offers products under Concreto, Artiste, InstaMix, X-Con and Ecodure brands. Nuvoco also provides construction solutions under its Zero M range of modern building materials.
Concrete
UltraTech Cement achieves 100% green energy milestone at Chhattisgarh plant
Published
5 days agoon
September 29, 2026By
admin
UltraTech Cement’s Kukurdih Works becomes its first integrated unit to meet 100 per cent electricity needs through green energy every month.
Raipur (Chhattisgarh)
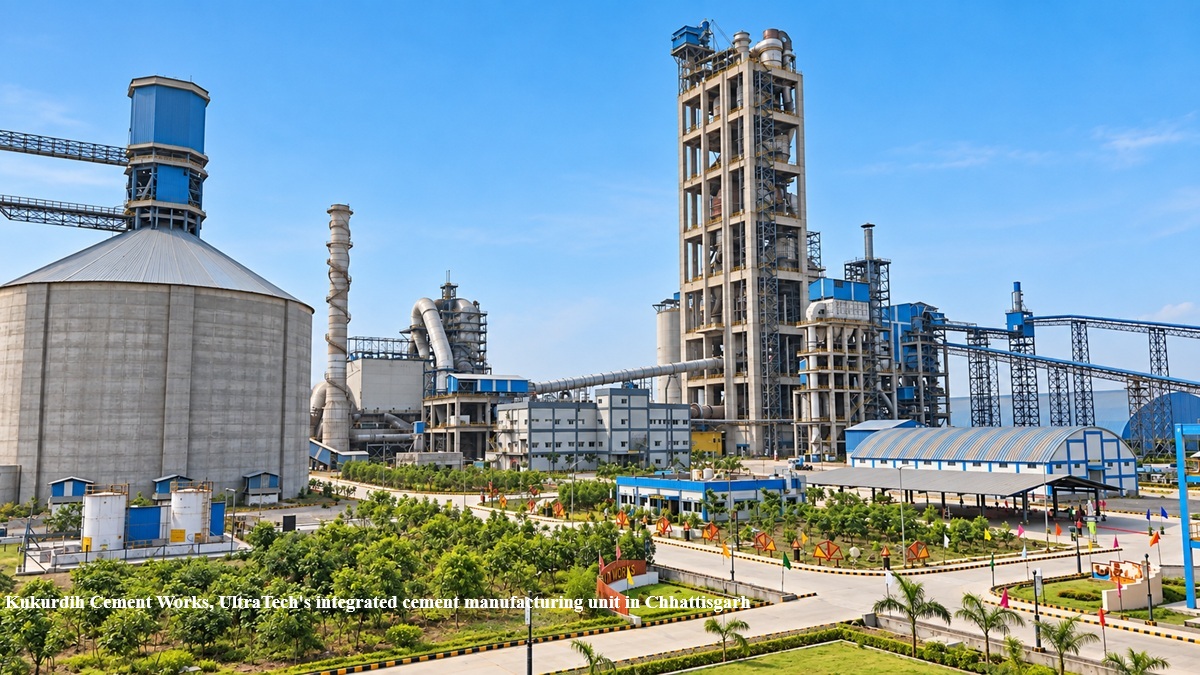
UltraTech Cement Limited, the world’s largest cement company outside China, has achieved a significant decarbonisation milestone, with its Kukurdih Cement Works integrated unit in Chhattisgarh meeting 100 per cent of its electricity requirement through green energy every month since April 2026.
Commissioned in 2024, Kukurdih Cement Works has an installed grey cement capacity of 3.3 million tonnes per annum. The unit achieved this milestone through a combination of renewable power sourcing and Waste Heat Recovery Systems (WHRS), which now collectively meet its entire electricity demand while ensuring operational reliability.
Since April 2026, nearly one-third of UltraTech’s 76 manufacturing units in India have maintained green energy utilisation above 50 per cent of their electricity requirements. Five units, including Kukurdih, have exceeded 95 per cent green energy utilisation. The company is also progressively deploying Battery Energy Storage Systems (BESS) across its network to enable deeper renewable energy integration.
As part of its decarbonisation strategy, UltraTech has not invested in additional captive thermal power capacity for greenfield projects or brownfield expansions at its integrated units for over a decade.
As of Q1FY27, the company’s captive green energy capacity stood at 1,897 MW, comprising 1,463 MW of renewable energy capacity from solar, wind and hybrid sources, along with 434 MW of WHRS capacity. Under its RE100 commitment, UltraTech aims to increase the share of green power in its total energy mix to 85 per cent by 2030 and achieve 100 per cent by 2050.
UltraTech Cement Ltd, the cement flagship company of the Aditya Birla Group, is a $10-billion building solutions company and the largest cement producer globally by sales volume outside China. The company has a total grey cement capacity of 210.1 MTPA and white cement/putty capacity of 3.5 MTPA. It is a signatory to the GCCA Climate Ambition 2050 and has committed to the Net Zero Concrete roadmap announced by GCCA.
Praveen Vashistha, Founder, Gxpress Solutions, speaks about building a holistic logistics network that encompasses latest technology and current challenges faced by logistics service providers.
Logistics may seem to only entail transporting a package from one location to another. However, there is more to this term than just that. Logistics refers to the entire process of controlling all movement, transfers and decisions in the correct way at the right time and cost and with the desired level of visibility.
People nowadays want to receive more than just the delivery. They want quick, efficient, reliable and transparent logistics service. On the other hand, companies are facing higher operating costs, broken supply chains, congested cities, changing habits of consumers and growing complexity of logistics services. In this situation, a full logistics package is gaining importance not only as a competitive advantage but also as a necessity for a successful business.
The main challenge lies in uniting the first mile, the middle mile and the last mile into one seamless process.
The journey begins before the package moves
First-mile logistics may be the least recognised part of the logistics chain, but they have a crucial influence on all that follows.
This stage starts from the moment the shipment leaves the manufacturer, supplier, farm, warehouse or distribution centre. Depending on the industry, first-mile logistics may involve grouping shipments from multiple suppliers, compiling paperwork and checking the inventory before sending the shipments to a central hub.
Flaws in first-mile logistics produce effects later down the supply chain. Delays in cargo pickup can affect warehouse operations; improper packaging can damage goods in transit; and incorrect inventory information may cause stockholding or unnecessary replenishments.
This is why building a reliable network involves simplifying the operations done at the beginning of the supply chain.
Companies require accurate demand forecasts, supplier visibility, standard procedures, and software to capture information from the moment a shipment enters the supply chain. Route planning and fleet management are also important at this stage, especially as it may involve contacting multiple suppliers.
The main goal is simply to make the first mile predictable.
The middle mile: Where scale meets complexity
When products leave the original site, they travel through the ‘middle mile,’ which connects fulfilment centres, warehouses, sorting centres, and regional distribution points. In this phase, logistics networks begin operating on a large scale. A shipment can pass through several facilities before reaching the final destination. Each additional transfer entails the risk of delay or damage and information losses. Accordingly, the ideal solution is not to minimise the number of transfers but rather to optimise them. The use of hub-and-spoke networks, regional distribution centres, and strategically placed distribution centres can help companies shorten transportation routes and optimise distribution costs. Besides, data can be used to determine the optimal placement of inventories.
For instance, a retailer may find that it takes more time and is more expensive to deliver goods to customers if everything is stored in a central warehouse. Meanwhile, regional distribution helps meet the customer’s needs quicker and more efficiently.
The last mile is where the customer judges you
When it comes to the logistics experience, the customer experience comes down to the delivery. While the last mile might comprise a small part of the entire journey in actual distance, it could also entail expensive and difficult processes. Delivery runs through densely populated cities, through traffic jams, through unsuccessful delivery attempts, and through changing consumer preferences and narrowed time frames.
Customers want to have control over their delivery. Delivery means that customers expect to know the exact moment when their order is delivered. They need to receive current updates about their orders and the ability to decide whether they want scheduled deliveries, or whether they want their order to be dropped off at a designated location far from their house.
As a result, last-mile logistics must incorporate both efficiency and experience. The technology may be used to ensure timely and accurate delivery, through such products as route optimisation and real-time delivery tracking.
However, technology is not enough to guarantee success in terms of last-mile delivery. Knowledge of the local area is still an important aspect that contributes to successful delivery.
One network, not three separate operations
First, the common mistake that organisations can make is treating the first mile, the middle, and the last mile separately.
An effective first mile of logistics does not matter much if the shipment waits in a hub for many hours. A perfectly working warehouse does not make a happy customer if the last-mile delivery fails. Therefore, even the fastest last-mile delivery can become an expensive operation if the supply is not well geographically positioned.
The three moments should work together as one whole system.
This implies having a common view on inventory, transport capacities, shipment statuses and demand. The Transportation Management System, Warehouse Management System and order management system should give information to each other instead of acting like separate islands.
That is where real-time information comes into play!
If something happens, such as a vehicle gets delayed, the company has to know that from the start. If not, someone from Customer Service should be informed about the situation.
Visibility is the new infrastructure
Previously, companies had to rely on physical assets, such as warehouses, trucks, and sorting facilities, to create their logistics networks. Today, they have an additional layer of technology providing visibility.
Command-and-control systems now include GPS tracking, Internet of Things devices, bar-coding, RFID, cloud computing, artificial intelligence, and analytics, which allow companies to know what the goods are doing, how well they are doing, and what is going to happen next.
Predictive analytics reveal possible delays. AI-powered forecasting increases availability. Digital dashboards enable the manager to monitor all operations in one place. The efficiency of such technologies is not measured in the amount of information they gather, but rather in their capability of converting data into knowledge.
Logistics managers should be able to answer the following questions: Where is it? When is it supposed to arrive? What causes the delay? What impact does it have? Can it be delivered some other way? How much will it cost?
The sooner the answers are given, the more resilient the logistics system is.
Resilience must be designed into the network
The events of recent years have highlighted the vulnerability of interconnected supply chains. Geopolitical tensions, bad weather, a lack of labour, poorly developed infrastructure and an unexpected spike in demand are some events that can cause problems for logistics systems without prior notice. Thus, companies should create an end-to-end network not just for normal times but also capable of functioning quickly in problematic situations. In order to create such a network, it is necessary to find alternative suppliers, use several means of transportation, create several routes of delivery, and establish inventory. It is also important to use scenario planning to define what to do if the main hub becomes unavailable or any means of transportation is blocked.
Sustainability: Part of the delivery equation
The future of logistics will also be shaped by environmental considerations.
As delivery volumes rise, businesses are under increasing pressure to reduce emissions without compromising service. Better route planning, load optimisation, electric vehicles, alternative fuels, renewable-energy-powered warehouses and consolidated deliveries can all contribute. The most sustainable shipment is often the one that does not require unnecessary movement in the first place.
Better demand forecasting and inventory placement can reduce empty miles and avoid repeated transportation. Consolidating deliveries can improve vehicle utilisation. Reverse logistics can ensure that products, packaging and materials return efficiently instead of becoming waste.
Sustainability, therefore, should not be treated as a separate initiative. It should be incorporated into network design itself.
The future belongs to connected logistics
An end-to-end logistics network ultimately seeks to close existing gaps between various processes.
Every mile of the process should be interconnected with the other miles. Warehouses should be aware of the restraints imposed by transportation. Delivery crews should be able to know at every moment the inventory at their disposal. Clients must have access to this useful information.
Companies that will be successful in this area will not necessarily be the ones with the biggest fleets or the most warehouses. They will simply be the ones that can employ their resources in the most effective manner.
The future of logistics will be represented by an ecosystem consisting of the combination of the physical aspect, digital intelligence, and personnel decisions. Every mile in the process of delivery is important. However, the key advantage here is getting those miles to work together.
For companies, it means having minimal resistance, enhancing their efficiency and improving customer care. For clients, it means simply having the right product delivered at the right time.
About the author: Praveen Vashistha, Founder, Gxpress Solutions,

UltraTech’s Kukurdih unit runs fully on green energy
Cement Prices Rise Rs. 7 per Bag in September; October Hikes Expected
Andhra Pradesh Clears Rs. 30 bn My Home Cement Plant
Nuvoco Vistas, CleanMax Partner for Wind-Solar Hybrid Project in Rajasthan
UltraTech Unit Runs Entirely on Green Energy
UltraTech’s Kukurdih unit runs fully on green energy
Cement Prices Rise Rs. 7 per Bag in September; October Hikes Expected
Andhra Pradesh Clears Rs. 30 bn My Home Cement Plant
Nuvoco Vistas, CleanMax Partner for Wind-Solar Hybrid Project in Rajasthan
UltraTech Unit Runs Entirely on Green Energy
Trending News
-
Concrete4 weeks agoKirby India Breaks Ground on Fourth PEB Plant in Tamil Nadu
-

Concrete4 weeks agoAditya Birla Group Launches Ultravolt Wires And Cables Business
-

Concrete4 weeks agoCentral Technical Team To Survey Sites For Bhadradri Kothagudem Airport
-
Concrete3 weeks agoCement Demand Strong As Prices Remain Stable