Connect with us

Economy & Market

Cement Financing Systematic approach

Published

on

Shares

Cement is among the most vital ingredients required for the growth of an economy. A growth in demand for cement reflects an uptick in the activities in the business, financial, real estate and infrastructure sectors of the economy. In the last decade, cement demand has grown consistently at a multiple of over 1-1.2 times of GDP growth underpinned by the rising demand for housing and infrastructure. To meet this demand, cement companies invested briskly in expanding capacities leading to increased fund need. However, innovative methods of financing is still evolving in this brick and mortar industry. The cement industry requires financing for its working capital and capital expenditure requirement. Working capital cycle starts right from the time of material procurement, production and sale of finished goods till the realisation of sales proceeds. The primary requirement is in building up raw materials, additives, fuels, stores & spares, clinker and finished goods inventory. Debtors are generally in non-trade segment of business. The sector incurs capital expenditure for its regular capex requirement, expansion of existing capacities and setting up of new capacities.The development of industry post decontrol was dependant on fiscal incentives, financing from international institutions (IBRD, etc) and local developmental financial institutions. With the passage, just as the industry has evolved, the development financial institutions too have become banks.During the early stages, capacity addition was dependent on promoters and leveraging capabilities. The debt equity ratio of sector used to be 2 to 2.5 times of debt to equity. The sector profitability was weak so promoter/companies used to survive on fiscal incentives provided by the government. The construction activities were weak and companies were not having the financial motivation to expand. Thus, despite being one of the oldest industry, no company could acquire/add sizeable capacities to reckon with.With the opening up of the economy in 2001, together with a flourish in information technology, communication and entertainment (ICE) sectors, the demand for cement saw a sustainable growth of over 8 per cent. The profitability improved which was ploughed back in further capacity addition.
Working Capital Financing
Working capital needs are met through traditional banking channels. Companies opt for working capital arrangements through (i) consortium banking arrangement or (ii) multiple banking arrangement. The common modes of financing working capital are cash credit, WCDL, export packing credit, etc. However, the following two products also help companies in managing working capital.Apart from use of cash credit, WCDL & packing credit, companies also use buyers credit and supplier’s credit facilities provided by various banks. Under the buyers credit facility, banks pay to the company’s import vendors and company pays to the bank on a pre-determined date with interest. Similarly companies also use supplier’s credit facility.
Channel financing: To reduce debtors in their books, companies use channel financing for its large dealers. Bankers do their own due diligence and provide credit facilities to dealers which are exclusively used for payment or clearing dues of the company. The onus on the company is the continuity of dealership. If there is disruption, companies are required to inform the banks.
Financing of Capital Expenditure
Long term financing usually takes the form of (i) equity (ii) debt and (iii) hybrid (mix of debt & equity).
Equity: It is a permanent form of money which is mobilised by the promoters and through public participation. In case of an established company promoters can invite private equity funds. Besides companies issue ADRs/GDRs in foreign capital markets.
Debt: Companies raise debt through banks and other FIs. Depending on the financial strength, companies evaluates the various debt raising options. Debt raising can be done in (i) foreign currency and (ii) rupee, and can be further segregated into secured and unsecured borrowings depending on whether any collateral has been provided to the lender.
Common Modes of Long Term Financing
For raising long term funds the industry uses various instruments in the domestic as well as the foreign capital markets depending on the interest cost, accessibility to various markets and risk appetite, etc.Debentures: Over the years industry has reduced the use of debentures as a mode of financing due to high interest as well as compliance cost. Proportion of debentures has reduced drastically from 34 per cent in FY06 to 14 per cent in FY10.
FC/Rupee Term Loan: Foreign currency loans in the form of ECBs appeals the industry due to its low cost and rupee term loan due to its relatively low cost and flexible end use. Requirement has increased as is evident from the increase in its proportion of 48 per cent in FY 06 to 57 per cent in FY10.
Sales Tax Deferment Loan: Appeal of incentives provided by various government has attracted the industry. Interest free sales tax deferment loan also improves the overall weighted average cost of theborrowings.Foreign Currency Convertible Bonds (FCCB): Some players also access international markets by issuing FCCB. It has an option to convert the bonds into equity at a pre-determined price on a specific date. Many players tie up with IFC for financing their capex needs. Companies also access ECA financing from the Exim Banks of the countries from where they are importing major equipments, ie, Hermes and Coface.
MNC’s generally borrow in local markets for local expansion and for acquisition financing they opt for offshore financing based on cost benefit analysis.
Challenges faced by the industry

  • With rise in capital cost and longer time for implementation, judicious mix of internal accrual, equity and debt became critical.
  • Locally long term maturity debt papers can be placed only with life insurance companies or some banks.
  • Cost of borrowing in foreign currency (ECBs) is still competitive with full hedging as compared to domestic borrowings. But keeping the currency risk and interest rate risk unhedged may result/put companies into deep trouble.
  • With over capacity in the sector, the equity route for mobilising money is also not cheap. Equally PE money is costlier funds require exit route at a higher price.
  • Hence companies should have systematic approach of risk management relating to leveraging and debt servicing.

Continue Reading
Click to comment

Leave a Reply

Your email address will not be published. Required fields are marked *

Concrete

Wonder Cement appoints Mahesh Singh as VP Corporate Brand Communication 

Published

on

By

Shares

Singh brings 20+ years of brand and marketing experience, and will lead integrated corporate brand communication initiatives at Wonder Cement 

New Delhi

Wonder Cement, a leading cement manufacturer, has appointed Mahesh Singh as Vice President – Corporate Brand Communication. In his new role, he will oversee corporate brand strategy and communication, including digital and performance marketing, public relations, trade, events, exhibitions, sports and experiential marketing. 

Singh brings over two decades of experience across marketing and communications, with roles spanning the automotive industry, agencies and entrepreneurship. He spent more than a decade with Honda Motorcycle & Scooter India, working across integrated communication, media, digital, retail and consumer engagement. His stint also included helping build the company’s digital marketing capabilities. 

He moved to dentsu X India as Vice President – Strategy & Planning, working across categories such as automotive, auto components, electric vehicles, FMCG, consumer electronics, BFSI, apparel and brand consulting. His responsibilities included media and marketing strategy, product launches, content, performance marketing and consumer activations. 

Singh subsequently took an entrepreneurial route with Radiant Brands before joining Shriram Ltd (SPR Autotech) as Head – Marketing & Communications. There, his remit included brand and corporate strategy, communications, PR and ORM, retail identity, loyalty programmes and events. 

At Wonder Cement, Singh will be responsible for bringing together the company’s corporate brand communication initiatives across digital, performance marketing, PR, trade, sports and experiential platforms. The role will focus on creating an integrated approach to communication across consumers, trade partners and other key stakeholders. 

The appointment brings to Wonder Cement a marketer whose career has spanned the brand, agency and entrepreneurial sides of the communications ecosystem. 

Wonder Cement, part of the RK Group, is a cement manufacturer with roots in Rajasthan and a focus on quality, trust and transparency. The company has grown to six manufacturing plants, and a cement capacity of 21.5 MTPA. With more than 2,000 employees and a network of over 5,000 dealers, its operations span manufacturing, distribution and customer engagement, with a focus on consistent product quality and efficient execution. 

Continue Reading

Concrete

JSW Cement commissions additional 1 MTPA grinding unit at Nagaur

Published

on

By

Shares

With this commissioning, JSW Cement’s total cement grinding capacity has increased to 25.10 MTPA, 
Mumbai

JSW Cement, one of India’s leading green cement producers and part of the diversified JSW Group, today announced the successful commissioning of an additional 1.00 MTPA cement grinding unit at Nagaur, Rajasthan. The commissioning marks another significant milestone in the Company’s growth strategy.

With this commissioning, JSW Cement’s total cement grinding capacity has increased to 25.10 MTPA, while its total clinker manufacturing capacity, including clinker capacity at its joint venture, JSW Cement FZC, stands at 9.74 MTPA.

JSW Cement had commenced operations in North India in March 2026 with the Nagaur Integrated Plant, comprising a 3.30 MTPA clinkerisation unit and 2.50 MTPA cement grinding unit. With the commissioning of the additional 1.00 MTPA cement grinding unit, the plant’s total cement grinding capacity has increased to 3.50 MTPA, enhancing the company’s ability to cater to the growing cement demand across Rajasthan, Haryana, Punjab and the National Capital Region (NCR). The expansion has been funded through a strategic mix of equity and long-term debt.

During the quarter ended 30th September 2026, JSW Cement has also commissioned the Alternate Fuel Handling System and the Waste Heat Recovery system (WHRS) at the Nagaur Integrated Plant.

Nilesh Narwekar, CEO, JSW Cement, said: “The commissioning of additional 1.00 MTPA grinding capacity at Nagaur is a key strategic priority for us and will accelerate JSW Cement’s expansion into North India. We look forward to servicing the growing needs of the region and contributing to the economic growth of Rajasthan, Haryana, Punjab and the NCR area. I am delighted to share that the company has commissioned this grinding unit within the expected timeline, showcasing our project execution capabilities. Further, the Alternate Fuel Handling System and the Waste Heat Recovery system (WHRS) are expected to substantially reduce our production costs going forward.”

Continue Reading

Concrete

UltraTech becomes first Indian cement firm to cross 2 GW green energy

Published

on

By

Shares

UltraTech Cement has crossed 2 GW of captive green energy capacity, with renewables and waste heat recovery meeting 48 per cent of its power needs.

Mumbai

UltraTech Cement Limited has surpassed 2 GW of installed green energy capacity for captive use, becoming the first cement company in India to achieve the milestone. The Aditya Birla Group company commissioned 116.55 MW of wind capacity at its Inter-State Transmission System-connected wind-solar hybrid project in Barmer, Rajasthan, along with 10 MW of Waste Heat Recovery System capacity at Sarlanagar Cement Works in Karnataka.

With these additions, UltraTech’s cumulative installed green energy capacity has reached 2,024 MW. This includes 1,580 MW of renewable energy capacity and 444 MW of waste heat recovery capacity, together meeting around 48 per cent of the company’s current power requirements.

The company said the milestone reflects the progress of its long-term energy transition strategy. In FY27 so far, nearly one-third of UltraTech’s 76 manufacturing units in India have maintained green energy utilisation above 50 per cent of their electricity requirements, while five units have crossed 95 per cent.

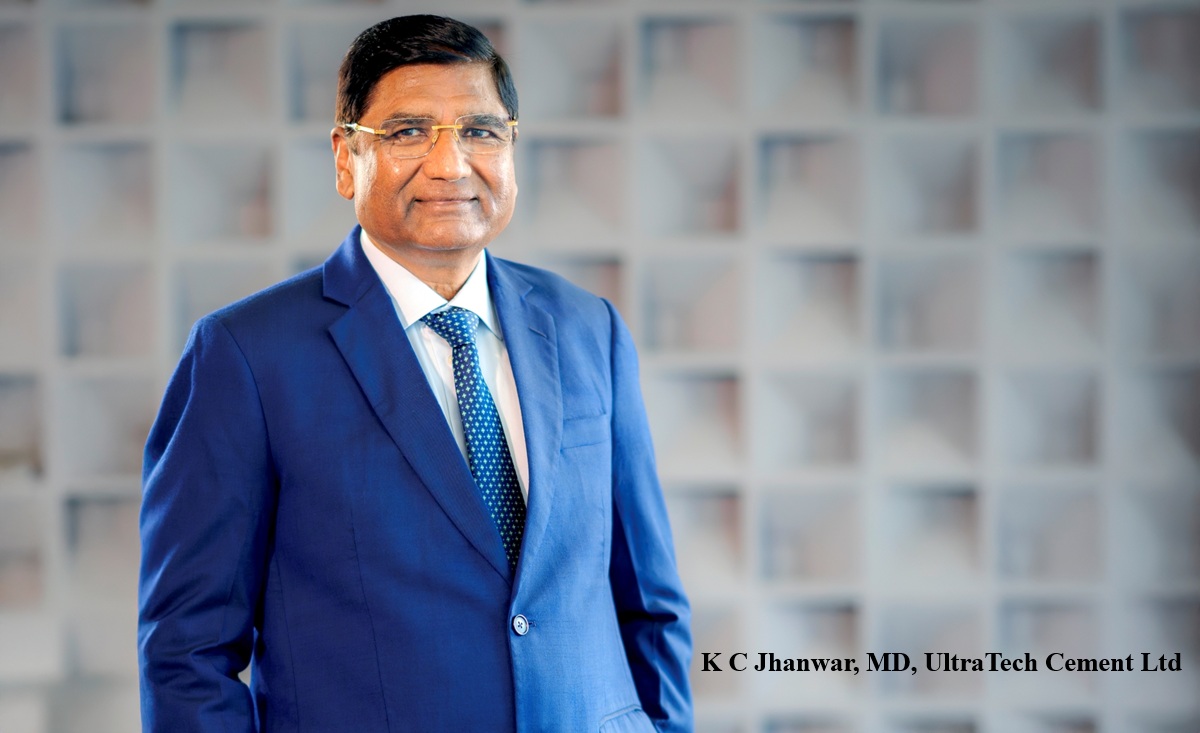
K C Jhanwar, Managing Director, UltraTech Cement Limited, said, “Crossing the 2 GW green energy milestone is the result of a strategy we have pursued consistently over the past decade. Cement is an energy-intensive, hard-to-abate sector, and showing that reliability and growth can go hand in hand with a rapid shift to green energy sets a benchmark for the industry. With nearly half of our power needs now met through green energy, we are significantly less exposed to fossil fuel supply constraints and power price volatility. As we scale up renewables, waste heat recovery and battery storage across our operations, we are building an energy foundation for stable, long-term growth.”

UltraTech commissioned 430 MW of green energy capacity in FY26 and continues to expand its renewable energy and waste heat recovery portfolio.

The company is also progressively integrating Battery Energy Storage Systems across its operations to improve renewable energy utilisation and supply reliability.

In 2025, UltraTech operationalised what it described as India’s first on-site hybrid round-the-clock renewable energy project at Sewagram Cement Works in Gujarat. The project combines solar, wind and battery storage.

As part of its decarbonisation strategy, UltraTech said it has not invested in new captive thermal power capacity for either greenfield projects or brownfield expansions at its integrated units for more than a decade.

The company said its expanding green energy portfolio is helping reduce dependence on conventional grid electricity and fossil fuel-based power, while lowering exposure to fluctuations in coal and electricity prices.

UltraTech aims to increase green energy’s share in its total power mix to 85 per cent by 2030. As a member of RE100, it has also committed to meeting 100 per cent of its electricity requirement through renewable sources by 2050.

UltraTech Cement, the cement flagship of the Aditya Birla Group, has a total grey cement capacity of 210.1 MTPA and white cement and putty capacity of 3.5 MTPA. The company is also a signatory to the GCCA Climate Ambition 2050 and has committed to the GCCA Net Zero Concrete roadmap.

Continue Reading

Video Thumbnail
▶

    SIGN-UP FOR OUR GENERAL NEWSLETTER

    Trending News

    SUBSCRIBE TO THE NEWSLETTER


    Don't miss out on valuable insights and opportunities to connect with like minded professionals.


      This will close in 0 seconds