Connect with us

Concrete

Global Aggregates Production

Published

on

Shares

Jim O’Brien, President, GAIN, on strengthening the global aggregates industry through collaboration, data sharing and a commitment to sustainability.

GAIN™ is the trade-marked acronym of the Global Aggregates Information Network. Founded in 2010, it is an entirely voluntary network of the major national and regional aggregates associations of the world. The mission of GAIN is to openly share experiences and industry best practices in the interests of promoting the greater sustainability and performance of the aggregates industry globally. GAIN has no commercial interests and vigorously enforces an anti-trust policy.
Starting with just five members in 2010, GAIN now has over 20 members spread across all the six continents, its members representing 75 per cent of global aggregates production of just 39 billion metrictonnes(bnt).
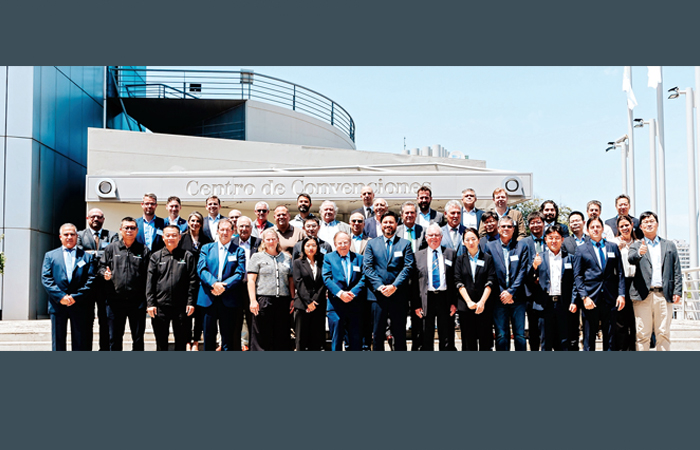
GAIN is uniquely successful in its highly-interactive global membership, thanks to the very positive cooperation of its members. The most recent physical GAIN meeting, its seventh global meeting, was held in Córdoba, Argentina, kindly hosted by the Argentine Association Federación de la Piedra, with most GAIN regions in attendance. The wide-ranging agenda focused on sharing best practice on key industry challenges, and found the industry to be in resilient recovery post-pandemic and poised to address and benefit from future sustainability challenges and opportunities.
The next physical meeting of GAIN is planned for October 19-22, 2025, to be held in Córdoba, Spain, hosted by the Spanish Aggregates Federation. The 2026 physical meeting will be hosted in Shanghai by the China Aggregates Association. In parallel, virtual GAIN meetings are held every two months and are widely attended (including India) across many time zones and these too are marked by lively open exchanges of best practice on specific topics.

Taking stock
One ambition of GAIN is to compile the best annual estimates of aggregates production from data provided by GAIN members, the situation as of April 2025. This data reflects the best estimates available to each region, and while not claiming to be perfect, is probably the best data available anywhere on global aggregates production. The GAIN total of 34.1bnt in 2019 has actually declined to 29.4bnt in 2024, the significant decline of 4.7bnt being due to a combination of the impacts of the pandemic, the economic slowing in China and the wars in Ukraine and in the Middle East. When estimates for non-GAIN countries are added (based on their national populations x their estimated tonne/capita), the global totals of 44.0bnt in 2019 has actually declined by 11.4 per cent to 39.0bnt in 2024, the trend being shown in Figure 2. The estimates given for 2025 must at this stage be regarded as preliminary and are very subject to the unpredictable geopolitics now in play, but point towards 2025 being a similar year to 2024 with 39.0bnt global total aggregates production.
The breakdown by region is illustrated in
Figure 1, still dominated by China at 39 per cent, with India coming second at 15 per cent, followed by Europe at 7 per cent and the USA at 6 per cent, these top four comprise 67 per cent of the global demand. Adding in the other GAIN member countries brings the GAIN total to 75 per cent of global production. It is hoped that many more countries will join GAIN in the coming years, bringing its representation towards 100 per cent of the global aggregates industry. The global average is 4.8t/c; for GAIN members the average is 6.5t/c and the non-GAIN average is 2.6t/c. For any country, the demand in tonnes per capita can be empirically related to GDP per capita – or more precisely, the rate of change in GDP/capita –plus upward adjustments for national terrain ruggedness and local
climatic severity.
Looking ahead towards 2030, assuming a positive global geopolitical outlook with resultant economic growth, coupled with the twin demands of population growth and urbanisation, there is a possibility for global demand to reach 40bnt by 2030. These figures demonstrate that aggregates are indeed by far the most used bulk product on the planet, with the industry having an economic value similar to that of the cement sector, both points often overlooked.
Looking specifically at India, as shown in Figure 2, production suffered a significant decline in 2020 during the pandemic, but is now back into strong growth with an estimated 5.9bnt for 2024, hopefully further rising to 6.4bnt in 2025. That will correspond to a demand of 4 tonnes/capita; while still well below that of developed regions, this can portend significant further growth in the years to come. Overall, India should be proud that it is the second largest and fastest growing aggregates market globally. The current growth is being driven principally by massive infrastructural investments in roads, railways, ports and airports; long may it continue.
The author hopes that India will soon benefit from forming a much-needed fully-fledged national aggregates association, similar to those very professionally representing the Indian cement and concrete sectors. A national aggregates association, benefitting from sharing of international best practices within GAIN, can then bring world class excellence to the aggregates industry in India.

About the author:
Jim O’Brien, President, GAIN, is a veteran of the building materials industry. He has spent 39 years at CRH plc, and has spearheaded the formation of the Global Aggregates Information Network (GAIN), a voluntary liaison network of regional and national aggregates associations around the world. More details on www.gain.ie.


Concrete

India’s Cement Sector Cuts Energy Use, but Worker Safety Worsens

iFOREST finds efficiency gains alongside water and safety concerns

Published

on

By

Shares

India’s cement sector has improved its energy and carbon efficiency, but rising groundwater use in water-stressed regions and deteriorating worker safety remain significant concerns, according to a report by the International Forum for Environment, Sustainability & Technology (iFOREST). The findings also highlighted weak policy implementation and gaps in sustainability reporting.

India, the world’s second-largest cement producer, uses about 2.54 gigajoules of energy per tonne (GJ/t), below the global average of 2.88 GJ/t. However, renewable sources accounted for only 5.1 per cent of the sector’s energy mix, indicating continued dependence on conventional sources.

The report assessed 18 cement companies against 107 Business Responsibility and Sustainability Reporting indicators for FY24 and FY25. The companies covered 87 per cent of India’s cement production. Carbon emissions intensity declined from 0.58 to 0.57 tonnes of carbon dioxide per tonne, but total emissions increased 4 per cent to 224.3 mn t, equivalent to about 6 to 7 per cent of India’s overall emissions.

Overall water withdrawal declined 9.5 per cent during the study period, while withdrawals in water-stressed areas, mainly in Rajasthan, increased by more than 20 per cent. Groundwater’s share of withdrawals in these areas rose from 27 per cent to 38 per cent, raising concerns about the sector’s impact on vulnerable water resources.

The sector employs about 228,000 people, including 63 per cent contractual workers, 3.1 per cent women and 0.07 per cent persons with disabilities. Women in key managerial roles earned 26.8 per cent less than men, while median pay for women workers fell 11.1 per cent in FY25 as men’s pay increased. Worker injuries rose 36.5 per cent to 359, and fatalities increased from 17 to 22, with workers accounting for more than 90 per cent of deaths.

iFOREST recommended cement-specific reporting guidance, standardised metrics, mandatory production disclosure and third-party verification. It also called for environmental, social and governance policies to be integrated into business strategies and implemented more effectively on the ground.

Continue Reading

Concrete

Ambuja Cements Expects Volume Growth to Outpace Industry in H2

Ambuja Cements sees stronger trade and institutional demand in H2 FY27.

Published

on

By

Shares

Ambuja Cements expects its sales volumes to grow faster than the cement industry during the second half of fiscal year 2027, as it seeks a recovery in institutional demand after a weak first half. The Gautam Adani-owned company is aiming to rebuild volumes while protecting profitability.

The company reported a 90 per cent year-on-year decline in consolidated net profit attributable to owners of the parent to Rs. 1.93 bn for the quarter ended 30 September, from Rs. 17.74 bn a year earlier. The previous year’s profit included a reversal of income-tax provisions worth Rs. 16.97 bn. Revenue from operations rose marginally to Rs. 91.66 bn from Rs. 91.3 bn.

Trade volumes increased 8.6 per cent year-on-year in the September quarter, but weaker institutional sales left overall volumes broadly unchanged. Ambuja Cements expects both trade and institutional sales to turn positive in the third and fourth quarters. Trade sales are made through dealers and distributors, while institutional or business-to-business sales involve bulk supplies to infrastructure developers, government projects and real estate companies.

The company had earlier reduced institutional sales that did not generate adequate returns. It now plans to rebuild the business selectively, while continuing to prioritise trade sales and higher-value products. Trade accounted for 74 per cent of sales in the quarter, up six percentage points from a year earlier, while premium products increased to 37 per cent of trade sales from 35 per cent. Blended cement’s share rose to 82 per cent from 77 per cent.

Ambuja Cements commissioned 4.6 mn t of capacity during the quarter. Another 3.2 mn t at Bathinda in Punjab and Jodhpur has stabilised, with the facilities expected to ramp up in the second half. A further 2.4 mn t facility at Varkala in Bihar is scheduled for commissioning during the period. Higher fuel and logistics costs remain a challenge, while the company has realised a cement price increase of about Rs. 10 per bag in October and is targeting operating costs of Rs. 4,250 per t for the full year.

Continue Reading

Concrete

JK Lakshmi Cement Begins Rs 110 Billion Assam Plant Project

The 2.5 MTPA integrated cement plant is expected to be completed by FY2029.

Published

on

By

Shares
JK Lakshmi Cement has recently laid the foundation stone for Project Kamakshi, its first integrated cement manufacturing facility in Assam, marking its entry into Northeast India. The groundbreaking ceremony was held at Umrangso village in Dima Hasao district in the presence of Assam Chief Minister Himanta Biswa Sarma.
The project involves an investment of Rs 110 billion, including the mining lease, and will have an annual cement production capacity of 2.5 million tonnes, supported by a 1 million tonne clinkerisation unit. Scheduled for completion by FY2029, the facility is expected to generate employment for over 2,000 people while catering primarily to the growing Northeast market.
The integrated plant will feature dedicated railway sidings to facilitate efficient transportation of raw materials and finished cement, strengthening supply chain reliability and regional distribution.
Vinita Singhania, Chairperson and Managing Director, JK Lakshmi Cement, said, “”Project Kamakshi is the start of a long-term relationship with Assam and the wider North East. This is a region that is building fast, and it deserves quality cement made close to home. With this plant, we want to bring scale, jobs, and dependable supply to the region. At JK Lakshmi Cement, we believe that building a stronger India goes beyond infrastructure. It is also about growing together with the communities we serve.””
The investment aligns with the company’s strategy to expand into high-growth markets beyond its established presence in Northern, Western and Eastern India. The project is also expected to support regional economic development and infrastructure growth.
JK Lakshmi Cement aims to pursue its expansion plans while working towards its long-term target of achieving net-zero emissions by 2047.

Continue Reading

Video Thumbnail
▶

    SIGN-UP FOR OUR GENERAL NEWSLETTER

    Trending News