Connect with us

Concrete

India follows Japanese tech in manufactured sand segmen

Published

on

Shares

Manufactured sand is fulfilling 50 per cent of the total demand for sand being used in concrete mixtures in the country.

Manufactured sand is fulfilling 50 per cent of the total demand for sand being used in concrete mixtures in the country. Sanjay Nikam, CEO and Principal Business Consultant with Suru09 Business Services, feels that with the shortfall in river sand, the demand for m-sand will accelerate manifolds.

Can you explain the different types of sand?

There are different kinds of sands. For instance, the crush stone sand is a fine aggregate produced by crushing hard stone. The crush grail sand is a fine aggregate produced by crushing natural gravel; mix sand is a mix of the two. Then there is manufactured sand which is produced from resources other than natural resources

What are the key challenges faced by the manufactured sand industry?

The industry is facing many challenges. First and foremost is the challenge being the paucity of a uniform regulation pan India. Presently, different state governments have different licensing provisions, norms for royalty payments, sand dredging, etc. This results in disparity, cost undercutting and the easy availability of low-grade sand at cheaper rates in the market. Secondly, the crush quarry are smaller in size (25-50 acres) as compared to a cement mining area that can range beyond 1000 acres. That means one cannot have bigger area of operations. The output from these crusher plants range from 25,000 to 40,000 tons a month. Thirdly, logistics and local issues play a key role in this industry essentially because we are located very close to the city.

What is the ratio of aggregates and m-sand used in concrete?

In concrete, for every ton of cement used, the ration of aggregates used is 7 to 10 times higher. Of this, 50 percent is sand. For e.g., if the requirement of sand is 15,000 million tons, manufactured sand constitutes 50 percent.

Manufactured sand consumption has picked up from 2008, and the uptake was faster because of a decline in the volume of supplied river sand. While river sand registered a negative CAGR (-2 percent), the manufactured sand is registering a CAGR of 35 percent for the past couple of years. Fine aggregate offers better benefit and value than the coarse aggregator.

What kind of investments or expansion plans are you witnessing in the m-sand segment?

Realizing the poetical of the segment, there is a steady flow of investments. The number of players in m-sand segment has increased which encourages healthy competition. Also, there are players who are looking at aggregators and m-sand as apart of portfolio diversification. Globally if you take the leading cement players, they are present in the cement, RMC and aggregator segments. The trend will soon follow in India.

You mentioned changing global trends in the usage of m-sand. Can you elaborate further?

Globally, Japan is the first country to develop technology in the engineered sand segment because of the shortage of river sand. In Asia, China took the first move in the same direction because of the shortfall faced. Now that India also has challenges with river sand, the country has adopted Japanese technology to manufacture m- sand in the country. The adoption of m-sand in Europe and US is comparatively lower as governments in these continents have not imposed restriction on river sand dredging.

Renjini Liza Varghese

Continue Reading
Click to comment

Leave a Reply

Your email address will not be published. Required fields are marked *

Concrete

JSW Cement Announces Merger with Shiva Cement

Merger aims to create a unified cement platform and simplify operations
Published

on

By

Shares


JSW Cement has announced a scheme of arrangement to merge its listed subsidiary Shiva Cement with itself, creating a single unified cement platform. The boards of both companies have approved the proposal, which will require clearances from stock exchanges, the Securities and Exchange Board of India, the National Company Law Tribunal, Odisha Industrial Infrastructure Development Corporation and other applicable authorities.

The transaction is expected to be completed within 12 to 14 months, subject to the necessary approvals from regulators, shareholders and creditors. Under the scheme, JSW Cement will issue 5 equity shares with a face value of Rs. 10 each for every 41 equity shares with a face value of Rs. 2 each held by Shiva Cement shareholders other than JSW Cement.

The company said the merger would consolidate financial, managerial, technical, distribution and marketing resources while reducing administrative duplication and compliance requirements. It would also provide greater funding flexibility, potentially lower financing costs and eliminate inter-company guarantees.

The consolidation is expected to strengthen backward integration by enabling JSW Cement to use Shiva Cement’s clinker manufacturing facility. This would reduce dependence on external clinker procurement and improve supply-chain efficiency. Public shareholders of Shiva Cement would receive direct ownership in JSW Cement, which has a broader institutional investor base and a more liquid listed presence.

JSW Cement acquired a controlling stake in Shiva Cement through transactions that began in January 2017. Shiva Cement operates a clinker facility in Odisha, near the borders of Odisha, Chhattisgarh and Jharkhand, and commissioned a 1 mtpa cement grinding unit at Sambalpur in FY26 through a commercial arrangement with Bhushan Power and Steel.

JSW Cement has 24.10 mtpa of cement grinding capacity and 9.74 mtpa of clinkerisation capacity. Its Indian operations comprise nine plants, including two integrated units, one clinker unit and six grinding units. The proposed merger is intended to simplify the corporate structure and align the financial statements of the two companies.

Continue Reading

Concrete

UltraTech’s Kukurdih unit runs fully on green energy

The Chhattisgarh plant has met 100 per cent of its electricity needs through green energy since April 2026.
Published

on

By

Shares


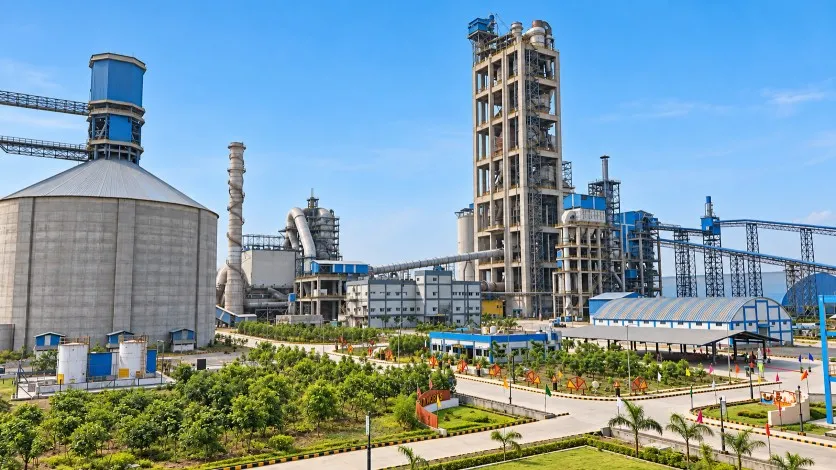
UltraTech Cement’s Kukurdih Cement Works in Chhattisgarh has met 100 per cent of its electricity requirement through green energy every month since April 2026. Commissioned in 2024, the integrated cement manufacturing unit has an installed grey cement capacity of 3.3 million tonnes per annum.
The plant meets its electricity requirement through a combination of renewable power sourcing and Waste Heat Recovery Systems (WHRS). UltraTech said the combination enables the unit to meet its power needs through green energy while maintaining operational reliability.
Since April 2026, nearly a third of UltraTech’s 76 manufacturing units in India have maintained green energy utilisation above 50 per cent of their electricity requirement. Five units, including Kukurdih, have exceeded 95 per cent green energy utilisation.
The company is also progressively deploying Battery Energy Storage Systems (BESS) across its manufacturing network to support greater integration of renewable energy. UltraTech said it has not invested in new captive thermal power capacity at its integrated units, including greenfield projects and brownfield expansions, for more than 10 years.
As of Q1FY27, UltraTech’s captive green energy capacity stood at 1,897 MW, comprising 1,463 MW of renewable capacity from solar, wind and hybrid sources, and 434 MW of WHRS capacity.
Under its RE100 commitment, the company aims to increase the share of green power in its total power mix to 85 per cent by 2030 and 100 per cent by 2050.

Continue Reading

Concrete

Cement Prices Rise Rs. 7 per Bag in September; October Hikes Expected

Cement prices rose in September as companies weighed further increases.
Published

on

By

Shares


Cement companies may seek to raise prices by Rs. 5 to Rs. 20 per bag across most markets in October, although the ability to sustain the increases will depend on demand recovery and dealer acceptance, according to a report by Centrum Broking. The outlook follows a pickup in pricing momentum during September after largely stable prices in July and August.

The all-India average trade price increased by Rs. 7 per bag month-on-month to Rs. 356 in September. Centrum Broking’s channel checks indicated gains across both trade and non-trade segments, with non-trade prices recording sharper increases in most markets. However, higher company billing rates were not fully passed on to customers in several regions because dealers continued selling at earlier prices to meet quarter-end volume targets.

The brokerage said demand weakness in Q2FY27 was less pronounced than the usual seasonal trend, with construction activity improving in several markets towards the end of the quarter. Demand remained range-bound across several markets in July and August, while September produced mixed regional trends. Higher rainfall affected activity in some areas, whereas lower rainfall supported construction work elsewhere.

South India recorded the largest price increase in September, at Rs. 11 per bag, followed by West India at Rs. 9. Central, East and North India each reported increases of Rs. 5 per bag. Despite the September recovery, the average all-India trade price for Q2FY27 stood at Rs. 351 per bag, down Rs. 1 sequentially, as weaker pricing in July and August offset the later gains.

Centrum Broking said the success of any October increases would depend on the pace of demand recovery and dealers’ willingness to accept higher prices. Fuel prices have also risen sharply in recent weeks, making the implementation and sustainability of price increases a key factor for the cement industry’s pricing outlook.

Continue Reading

Video Thumbnail
â–

    SIGN-UP FOR OUR GENERAL NEWSLETTER

    Trending News

    SUBSCRIBE TO THE NEWSLETTER


    Don't miss out on valuable insights and opportunities to connect with like minded professionals.


      This will close in 0 seconds