

Concrete
Opportunities for MSW in India

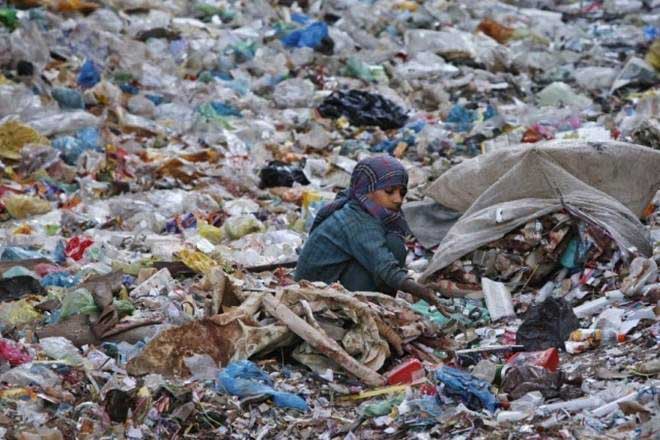
With urbanisation and industrialisation increasing around the world (despite a temporary COVID-19 setback), the issue of waste management and particularly of municipal solid waste will be a critical challenge to sustainable development.
Global waste production is expected to reach 27 billion tonnes per year by 2050, a third of which will be generated in Asia.1 India will be a major contributor: it currently generates more than 150,000 tonne per day of solid waste, approximate 54.75 million tonne (MT) per year.2
The government steps in To tackle this growing pile of waste ??much of which has traditionally ended up in landfills ??the Indian government has issued two directives:
Guidelines on Usage of Refuse Derived Fuel in Various Industries
Central Public Health and Environmental Engineering Organisation; Ministry of Housing and Urban Affairs (September 2018).
Guideline Document Uniform Framework for Extended Producers Responsibility
Under Plastic Waste Management Rules, 2016; Ministry of Environment, Forest and Climate Change (June 2020)
The first of these ??which is now in force ??aims to prevent the landfill of waste that are ??ombustible in nature but are not recyclable such as soiled paper, soiled cloth, contaminated plastics, multi-layer packaging materials, other packaging materials, pieces of leather, rubber, tyre, polystyrene, wood, etc.??
The second of ??which is still in consultation stage ??deals with plastic waste. Among other things, it will make companies that use plastic packaging for their products responsible for collecting and disposing of that packaging.4 One solution to both of these challenges is the substitution of fossil fuels by alternative refusederived fuels (RDF) at cement plants and thermal power plants.
The use of waste as an alternative fuel in the cement industry has a longstanding history, particularly in Europe, where substitution rates can reach well over 50 per cent and companies are pushing to reach 100 per cent. This is supported by generous gate fees paid by waste producers to cement companies and tight carbon emissions regulations (some alternative fuels are considered carbon neutral under EU regulations). Indeed, the use of RDF and other alternative fuels is acknowledged as a key step in the cement industry?? path to carbon neutrality, alongside energy efficiency and the use of supplementary cementitious materials.5
To encourage the use of RDF, the expenses so incurred for transportation of RDF, beyond 100 km distance may be booked by industries under their Corporate Social Responsibility (CSR) commitment as per Section 135 of the Companies Act, 2013.3 RDF in India
The Cement Manufacturers Association (CMA) had expressed its commitment towards disposal of wastes and plastics and use of alternate fuels and raw materials.6 The past President (2018 to 2020) of CMA, Mr. Mahendra Singhi, commented; ??he Indian cement industry has been able to use almost 75 million tonnes of waste as a replacement of raw materials and fuels??
Mr. Singhi, who is also the MD and CEO of Dalmia Cement (Bharat) Ltd, added that the Indian cement sector has played an important role in the transition to a low carbon economy and is fully committed towards efficiency in terms of clean and green operations.
As part of the new guidelines, cement companies are now required to utilise RDF in any kiln located within 400 km of an RDF production facility.
Unusually, it is also the cement companies that are required to bear the cost of this rule, for example; there are no gate fees payable for taking waste and cement companies have to pay the transportation fees for the first 100 km radius of the plant.
Managing the increasing quantity of MSW generating in India is a big challenge. A high percentage of MSW including non-recyclable combustible fraction ends up in landfills. In spite of enough demand a supply of RDF by vibrant private sector in waste management and cement industry and existence of enabling policy framework of SWM Rules 2016, current on ground situation is not very promising due to several challenges as depicted below:

The regulation envisages a rising scale of substitution rate from 6 per cent in the first year up to 15 per cent in the third year, although an evaluation of the amount of available RDF vs the energy needs of the cement industry suggest that a thermal substitution rate of 7.1 per cent may be the maximum achievable (Table 1).
The data captures the details of daily exposed garbage. There is a significant quantum of legacy wastes which needs to be processed to make it usable RDF.
A Partner for Sustainable Waste Management
The new regulations position the cement industry as a key partner in solving India?? waste challenges.
However, there are certain challenges in its processing. Notably, the quality of RDF currently produced in India is much lower than that of in other regions, with lower calorific value and much higher moisture content. In worst scenario the ??ombustible wastes??which ??hould at least be heat neutral??and ??hould not affect the Clinker quality??
The requirement for Indian cement companies to finance the capex required to begin using RDF has also focused the market on economically viable, simple and standard alternative fuels feeding systems to meet the possible substitution rate up to 7 per cent. Going forward, to increase substitution rates, the cement industry needs accuracy in feeding and dosing system, efficient process and alternative fuel material analysis. To support these requirements, cement industry demands proven technologies like; rotor weigh-feeders, a HOTDISC? Combustion Device with solid alternative fuel ash exaction possibilities and utilisation of solid alternative fuel ash, chlorine gas by-pass system and utilisation of chlorine rich dust.

Cement manufacturers like, Dalmia Cement, which targets higher levels of alternative fuel substitution rates, reportedly up to 100 per cent, as part of a corporate ambition to manufacture the greenest cement in the world.7 FLSmidth is supporting this ambition as the supplier of Dalmia Cement?? new plant at Rajgangpur, where the equipment and design of the plant were carefully selected to maximise the potential for alternative fuels and raw materials use, as well as to reduce energy efficiency and heat loss.Tackling plastics Plastic waste has garnered recent attention due to littering of crucial ecosystems, most notably that of oceans. According to one estimate, between 4.8 MT and 12.7 MT of plastic waste enters the oceans each year.8 Reversing this damaging pattern has been recognised as integral to sustainable development and is a key target of the fourteenth UN Sustainable Development Goal.9 As part of the solution to this challenge, the Indian government has introduced rules that make use and disposal of plastic packaging as the responsibility of the generator. This impacts the Indian cement industry in a couple of different ways.
Firstly, as a user of plastic packaging for its products ??and with bagged cement playing a larger role in the Indian cement market than in other regions ??the industry is faced with the need to set up systems to collect that plastic or switch to alternative paperbased packaging.However, the industry may also find itself (again) as a crucial part of the solution, due to its ability to utilise plastic waste as an alternative fuel. One opportunity arising from the regulations may be for the cement industry to partner with others that use plastic packaging to create efficient collection and processing systems for plastic waste that sees the non-recyclable elements made available for use in cement kilns.
Conclusion
Waste is a serious challenge to sustainable development. Finding ways to use the non-recyclable elements in a productive way is therefore key to
setting humanity on a path to a cleaner, greener future. With its huge capacity to utilise RDF, the cement industry has a vital role in doing this. And the benefits of doing so reach far beyond (emptier) landfills. RDF substitution of fossil fuels reduces both the cement industry?? carbon emissions, as well as the necessity to mine fossil fuels. Supporting the use of alternative fuels is therefore a priority for FLSmidth through our MissionZero ambitions to enable zero-emissions cement production.
As part of this, we have committed to providing cement producers the solutions needed to operate with 100 per cent alternative fuels. This goes beyond the provision of equipment to include our significant process experience ??from initial reception and handling of alternative fuels through their impact on conditions in the kiln and on the final chemistry of cement. This deep understanding of the process enables us to assist any plant in solving the challenges that alternative fuels bring ??whether just starting out or reaching for 100 per cent.
References
1. KUMAR, S., et at., 2017, ??hallenges and opportunities associated with waste management in India?? R. Society open sci. https://doi. org/10.1098/rsos.160764
2. AGGARWAL, M., 2019, ??umbai and Delhi generate most solid waste among metro cities??The Wire. https://thewire.in/environment/indias-megacities-mumbai-and-delhi-sitting-ona-pile-of-waste
3. Ministry of Housing and Urban Affairs, 2018,Guidelines on Usage of Refuse Derived Fuels in Various Industries, p. X.
4. This principal is known as ??xtended Producer Responsibility??
5. For example, see: IEA, 2018, Technology Roadmap:
Low-Carbon Transition in the Cement Industry, p. 28.
6. Indian cement industry commits towards waste management. https://www.outlookindia.com/ newsscroll/indian-cement-industry-commitstowards- waste-management/1630881
7. Global Cemfuels, 2019, ??almia Cement commits itself to 100 per cent RDF and biofuels by 2030?? https://www.cemfuels.com/news/item/3150-dalmia-cement-commits-itself-to-100-rdf-andbiofuels- by-2030
8. JAMBECK, J.R., et al., (2015) ??lastic waste inputs from land into ocean?? Science vol. 347, issue 6223, pp. 768-771. https://science.sciencemag. org/content/347/6223/768
9. Goal 14: Conserve and Sustainable Use theOceans, Seas and Marine Resources. https://www.un.org/sustainabledevelopment/oceans/
ABOUT THE AUTHOR: The article is authored by Dr Alka Mishra, Head of Sustainability Solutions, FLSmidth India


Concrete
Cement Firms to Invest Rs. 130 bn in Green Energy by FY28
Cement companies plan to expand clean energy capacity to 6 GW by FY28
Concrete
Centre Defers Clearance for Limestone Mine Near Bustard Habitat
Panel seeks revised mining plan and safeguards for pipelines and wildlife
Concrete
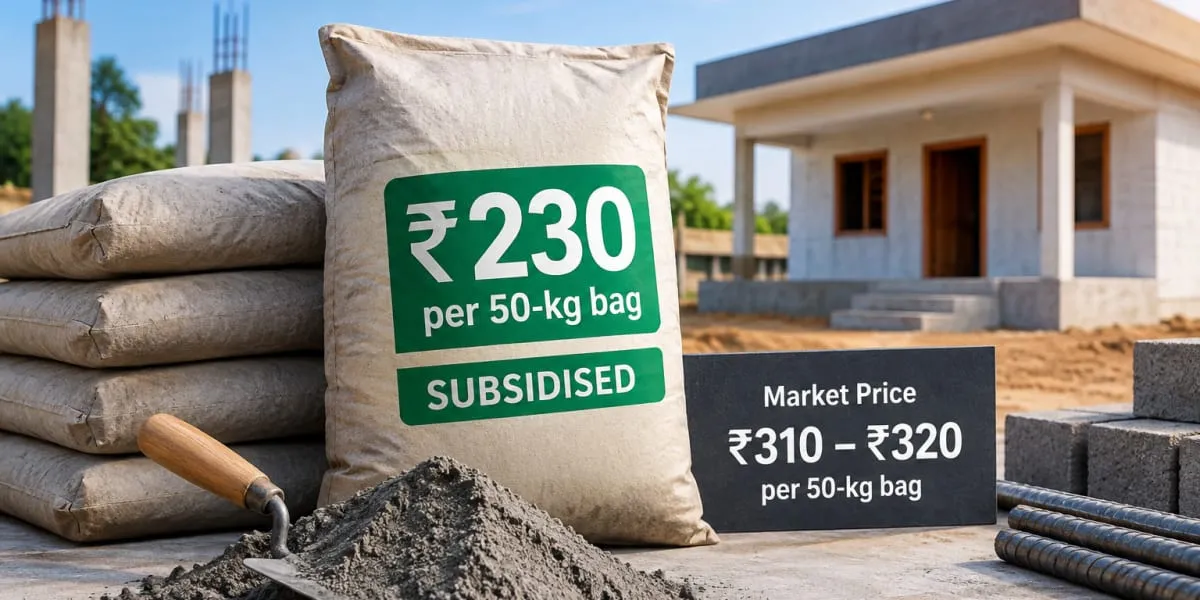
Telangana to Supply Subsidised Cement for Indiramma Houses
Poor families allotted Indiramma houses to receive cement at Rs. 230 per bag


Cement Firms to Invest Rs. 130 bn in Green Energy by FY28

Centre Defers Clearance for Limestone Mine Near Bustard Habitat

Telangana to Supply Subsidised Cement for Indiramma Houses

Cement Demand Strong As Prices Remain Stable

Aditya Birla Group Launches Ultravolt Wires And Cables Business
Cement Firms to Invest Rs. 130 bn in Green Energy by FY28
Centre Defers Clearance for Limestone Mine Near Bustard Habitat
Telangana to Supply Subsidised Cement for Indiramma Houses
Cement Demand Strong As Prices Remain Stable
Aditya Birla Group Launches Ultravolt Wires And Cables Business
-

 Concrete3 weeks ago
Predictive maintenance minimises the risk
-

 Concrete3 weeks ago
AI is solving longstanding challenges
-

 Concrete3 weeks ago
Fuller Technologies QCX® Lab Automation Systems
-
 Concrete3 weeks ago
Beyond the Gearbox: How a Holistic Lubrication Strategy Reduces Total Cost of Ownership in Cement Plants